The Ground Reality of Personal Loan Settlement.
Personal Loan Settlement, Bank Waivers & Resolution Guide
Personal loan default is not a crime. In India, personal loans can realistically be waived off by 50% to 80% based on the banks. But it deteriorates your CIBIL score. Here is the ground reality on Top 10 bank waivers, court summons, arbitration, and recovery agent harassment.
Personal loan settlement can waive off 50% to 80% of your total balance depending on the bank. It severely deteriorates your CIBIL score for 5 to 7 years (marked as “Settled”). The bank can file a case and release court summons, but if you do not sign or accept the summon, you are fine. Arbitration is a normal proceeding to negotiate and agree on settlement terms through an arbitrator.
Personal Loan 50% to 80% Settlement Truth
No Collateral Attached
Personal loans are unsecured. The bank has no asset, house, or vehicle to seize. Because they have zero collateral leverage, they are forced to negotiate settlements once payments stop.
NPA Write-Offs
When a loan stays unpaid past 90–180 days, it is marked as a bad debt on the bank's books. Recovering 20% to 50% in cash is far better for them than getting zero.
100% Fee Waivers
Much of your inflated outstanding amount is just accumulated late charges, bounce fees, and compound interest. Banks waive these fees almost entirely during settlement.
Waiver Percentage Stages:
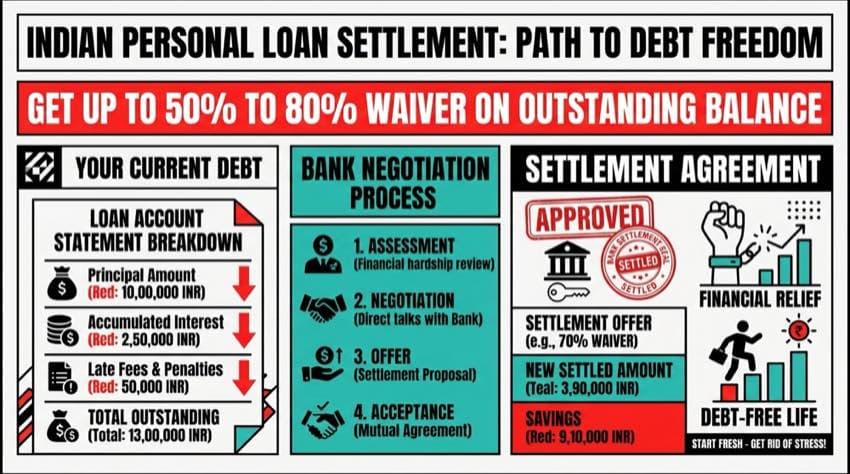
Visual 1.0: Breakdown of personal loan settlement negotiation, 50%–80% waiver ranges, and debt relief roadmap in India.
Personal Loan Settlement Calculator
Select your outstanding loan balance and your lender to see your estimated realistic settlement payout and waiver range:
Personal Loan Settlement Calculator
Estimate your realistic One-Time Settlement (OTS) payable amount based on your bank and default stage.
Personal Loan Default Impact on CIBIL Score
Settlement comes with a heavy cost to your credit profile. Here is the ground reality:
Your CIBIL report will show “SETTLED” or “POST WRITE-OFF SETTLED” instead of “CLOSED”. This informs every bank that you did not pay the full amount.
- Your CIBIL score drops by 100 to 200 points.
- You will not get new credit cards or unsecured loans for 5 to 7 years.
- Secured loans (Gold loans or Fixed Deposit backed cards) are the only way to rebuild.
If your personal loan has a co-borrower (spouse, parent) or guarantor, both credit files will be marked as “SETTLED”, causing an immediate 150+ point drop in both CIBIL scores.
Top 10 Personal Loan Bank Waiver Benchmarks
Below is the settlement data for the Top 10 most popular Indian banks and NBFCs in order of popularity:
HDFC Bank
Top Private BankGround Reality: Minimum 50% waiver possible in 180+ DPD stage. In Lok Adalat or written-off pools, waivers routinely touch 75%–80% for principal + interest.
Axis Bank
Top Private BankGround Reality: Minimum 50% waiver standard for unserviceable accounts. Closes quickly at 65%–75% discount when negotiated directly with PNO/Zonal heads.
State Bank of India (SBI)
PSU BankGround Reality: Runs periodic official "Rin Samadhan" OTS schemes. Highly structured process through Lok Adalat with clean No Dues Certificates.
ICICI Bank
Top Private BankGround Reality: High average waiver on unsecured personal loans and credit cards once transferred to central debt management recovery pools.
Kotak Mahindra Bank
Private BankGround Reality: Aggressive initial collection cadence, but provides substantial waivers (upwards of 55%) once legal notices are calmly responded to in writing.
Bajaj Finance
NBFCGround Reality: High volume lender with active field agents. Direct email escalation to Grievance cell unlocks 50%+ waivers on penal interest.
IDFC FIRST Bank
Private BankGround Reality: Professional digital-first approach. Settles amicably via virtual Lok Adalat hearings or written hardship representations.
IndusInd Bank
Private BankGround Reality: Personal loan accounts see deep discounts (50%+) once past 180 days delinquent and assigned to regional recovery clusters.
RBL Bank
Private BankGround Reality: Frequent co-branded cards and unsecured loans. Very flexible in year-end / quarter-end settlement drives (March/September).
Tata Capital
NBFCGround Reality: Reputable NBFC adhering strictly to RBI fair practices. Settles without extreme harassment when presented with medical or job loss proof.
Genuine Personal Loan Settlement Letter Verification
The #1 trap in personal loan settlement is paying based on verbal agent promises or WhatsApp texts. If you pay without an official letter, the bank treats it as a partial overdue payment, not a settlement!
- ✓1. Unique Reference Number: Must have an internal bank settlement ID (e.g.
HDFC/SAM/2026/SET-99420). - ✓2. Full & Final Waiver Clause: Explicit text stating that upon payment of ₹X by [Date], the account stands settled and remaining ₹Y is permanently written off.
- ✓3. Direct Loan Account Payment: Payment must be made strictly to your own Loan Account number (NEFT/RTGS), never to any agent's personal UPI.
- ✓4. Official Bank Email & Stamp: Issued on bank letterhead from an official bank domain (e.g.
@hdfcbank.com,@axisbank.com).
- ✗Verbal or WhatsApp text promise: “Pay ₹25,000 today and we will close your ₹5 Lakh loan.”
- ✗Asking payment to personal QR / UPI: Agents pocketing commission or paying minimum token dues.
- ✗The Result: The bank credits the ₹25,000 as a normal partial EMI, leaving your remaining ₹4,75,000 active, overdue, and accruing penal charges!
Personal Loan Summons, Section 25 & Arbitration Facts
Banks try to scare you with court talk and notices. Here is the ground reality:
Court Summons Ground Reality
The bank can file a case against you and the court can release summons for you.
Arbitration: Don't Get Scared
Normal ProceedingAn arbitration can be scheduled-don't get scared of that. Arbitration is just a normal proceeding where the bank and the consumer negotiate and agree on settlement terms through an arbitrator.
The arbitrator is not a judge and cannot send police or arrest you. In fact, arbitration and Lok Adalat proceedings are often the easiest way to negotiate and lock in a 50% to 75% waiver with formal settlement terms.
Real Court Notice vs Fake WhatsApp Threat
“POLICE SEIZURE TEAM VISITING IN 2 HOURS. PAY IMMEDIATELY.”
Sent on WhatsApp, 2-hour deadline, threats of public arrest. 100% Fake agent threat.“IN THE COURT OF MM: CC 1294/2026. SUMMONS ISSUED FOR [DATE 45 DAYS AWAY].”
Sent via Registered Post with official case number and official court stamp.Personal Loan Recovery Agent Harassment Tactics
Collection agents use dirty psychological tactics to force panic payments. Here is what they do:
Agents show up at your house unannounced to embarrass you in front of family or neighbors.
Automated dialers ringing your phone 50+ times a day from different numbers.
Harassment skyrockets in the last week of every month because recovery agents are desperate to meet their monthly collection targets and get commissions.
Sometimes an unauthorized minimum due payment (like ₹500 or ₹1,000) is made for you in your loan account without your knowledge.
Personal Loan Settlement Request Email Generator
Send this formal written email notice to the bank to request settlement, explain your financial hardship, and ask them to stop sending agents to your home:
Settlement Request Email Generator
Fill your details below to create an official email notice for your bank to request OTS and legally halt home visits.
5-Step Personal Loan Settlement Protocol & NOC Escalation
Cancel active auto-debits / e-mandates in your net banking to avoid continuous bounce charges.
Use our free tool above to generate your settlement request email and send it to the bank.
When agents call, state: “I have emailed my hardship request to the bank. Please reply on email.”
Never pay based on verbal promises or WhatsApp texts. Always insist on an official settlement letter on bank letterhead with unique reference number.
Pay only directly into your loan account number and follow up for your No Dues Certificate (NDC).
The 30-Day NOC Delay Escalation Ladder
Banks often delay releasing the No Dues Certificate (NDC). Use this 3-step escalation:
Personal Loan Settlement FAQs
Can I settle my loan for a 50% to 80% waiver?+
50% to 80% Waiver: Yes, unsecured personal loans routinely settle at 50% to 80% waivers once accounts remain unpaid for 6+ months.
Top Banks: HDFC Bank (35.3% avg, up to 80%), Axis Bank (38.3% avg, up to 75%), ICICI (46.3% avg), SBI (40.4% avg), Kotak Mahindra Bank (up to 80% waiver), and Bajaj Finance (up to 65% waiver) prefer recovering discounted amounts over zero recovery.
How badly does settlement hurt my CIBIL score?+
100–200 Point Drop: Causes an immediate drop in score and marks the loan as “SETTLED”.
5–7 Year Impact: No fresh credit cards or personal loans for 5–7 years unless rebuilt with FD-backed secured cards.
Does settlement hurt my co-borrower or guarantor CIBIL?+
Both Scores Impacted: Yes. If your loan has a co-applicant or guarantor, the “SETTLED” status is reported on both credit files, dropping both CIBIL scores by 150+ points.
What if the bank delays giving my No Dues Certificate (NDC)?+
Escalation Path: Email payment UTR receipt to Branch Manager. If delayed past 30 days, escalate to Principal Nodal Officer. Past 45 days, file a complaint on the RBI CMS portal.
Is the 50% waived loan amount taxable in India?+
Not Personal Income: For individual consumer personal loans, the waived amount is an internal write-off/compromise by the bank and is not taxed as personal income.
Can police arrest me for defaulting?+
Civil Dispute: Inability to pay an unsecured loan is purely a civil dispute in India, not a crime.
No Police Power: Police cannot arrest you or seize your property for personal loan default.
What if the bank issues a court summon?+
Summons Reality: The bank can file a case and release summons, but if you just do not sign or accept the summon, then you are fine and they cannot easily proceed against you.
Check Authenticity: 95% of WhatsApp threat messages are fake collection agent threats, not real court summons.
Should I fear an Arbitration notice?+
Do Not Fear It: Arbitration is a normal proceeding where bank and consumer negotiate and agree on settlement terms through an arbitrator.
Best Venue: It is one of the safest places to finalize a 50% to 75% settlement agreement.
Why did an agent deposit ₹500 into my account?+
Agent Target Trick: That is the recovery agent secretly paying out of their own pocket to meet their monthly collection targets.
Settlement Delay: It resets your default status and delays your 50%–80% settlement waiver.