WARNING: THIS IS NOT LEGAL ADVICE. THIS IS SURVIVAL ADVICE BASED ON REAL BORROWER EXPERIENCE.
UPDATED: SEPTEMBER 2026
Tata Capital Loan Settlement: Personal Loan OTS & Borrower Defense
Tata Capital Personal Loan OTS, Arbitration & Waiver Rules
A clear guide for Tata Capital borrowers. Learn how to negotiate 40% to 70% One-Time Settlements (OTS) on personal loans, stop agency threats using the Tata Code of Conduct, and challenge one-sided arbitration notices under Supreme Court rules.
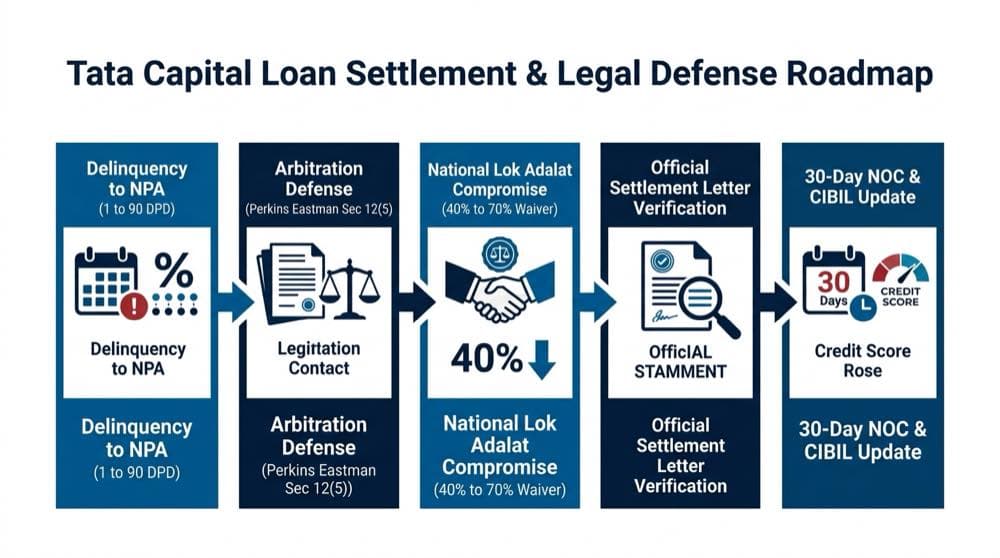
Visual Roadmap: Five simple steps to stop recovery calls, challenge arbitration, and settle your Tata Capital loan.
Quick Answer Summary
Can Tata Capital seize your salary or assets without a court trial? No. Tata Capital is an NBFC regulated by the RBI. For personal loans past 180 days default, borrowers with real hardship can settle dues at 40% to 70% discounts. If you receive an arbitration notice from a sole arbitrator picked in Mumbai, that notice is void under Section 12(5) of the Arbitration Act. Settle safely in Lok Adalat or via an official OTS letter.
⚡ Empirical CalculatorUNSECURED 180+ DPD
Tata Capital Settlement & Haircut Estimator
Calculate realistic One-Time Settlement (OTS) compromise ranges based on Tata Capital Central Collections and Lok Adalat recovery mandates.
Unsecured retail personal advance up to ₹35 Lakhs. Stressed accounts past 180 DPD qualify for Centralized Collections Desk OTS.
₹4,50,000
₹25K₹15 Lakh₹35 Lakh
Estimated Settlement Range:50% to 65% Haircut
Realistic Payoff Amount
₹1,57,500 - ₹2,25,000
Projected Savings
₹2,25,000 - ₹2,92,500
✓Penal Relief: 100% waiver of penal interest, late payment fees, and bounce charges.
✓Strategic Advice: Never settle over verbal calls. Demand an official settlement letter on Tata Capital letterhead with a unique settlement ID.
⚖️ Perkins Eastman Arbitration Defense:If Tata Capital sends you an arbitration notice from a sole arbitrator appointed in Mumbai without your mutual consent, that appointment is void ab initio under Supreme Court rulings and Section 12(5) of the Arbitration Act. Object immediately to halt unilateral proceedings.
1. Tata Capital Institutional Reality: Upper Layer NBFC Recovery
Tata Capital Limited is an Upper Layer NBFC regulated by the Reserve Bank of India. It follows strict rules for bad loans and capital health, similar to big banks.
When you default on a personal loan, your file moves through clear stages: SMA-0 (1 to 30 days late), SMA-1 (31 to 60 days late), and SMA-2 (61 to 90 days late). After 90 days, the loan becomes a Non-Performing Asset (NPA).
After 180 days of default, RBI rules force Tata Capital to write off the loan on its balance sheet. To recover cash, the company offers One-Time Settlement (OTS) options. Because it belongs to the Tata Group, it must follow fair collection rules.
Who Approves Discounts:Branch managers and telecallers cannot waive loan balances. All settlement discounts must be approved by the Central Collections Committee in Mumbai.
2. Tata Code of Conduct (TCOC) vs Outsourced Telecallers
The Tata Group follows the Tata Code of Conduct (TCOC). Its fair recovery rules strictly ban abuse, physical threats, workplace visits, and calls outside 8:00 AM to 7:00 PM.
However, outside collection agencies work on commission. When month-end targets approach, agency callers often break Tata rules by calling relatives, sending rude WhatsApp notes, and making fake arrest threats.
When recovery callers cross the line, report them using the Tata Code of Conduct. An email to the Principal Nodal Officer and Group Ethics Officer forces the company to stop abusive calls quickly.
When a loan defaults, Tata Capital often sends notices naming a sole arbitrator in Mumbai. They ask you to join online hearings or face an ex-parte order.
Under Supreme Court rulings in TRF Ltd. and Perkins Eastman (2020), a lender cannot pick an arbitrator on its own. Under Section 12(5) of the Arbitration Act, any arbitrator chosen by only one party without your agreement has zero legal power.
In Tata Capital vs. Jaikishan Subramanian (2026), the Bombay High Court held that one-sided arbitration awards cannot be enforced. Sending a written objection under Section 12(5) stops these threats.
4. Unsecured Personal Loans: 40% to 70% Haircut Dynamics
Personal loans with Tata Capital have no collateral attached. Knowing how bad loans are handled helps you time your settlement for maximum savings:
Early Delinquency (1 to 90 Days): Zero discounts. Tata Capital demands full payment and late fees.
NPA Stage (90 to 180 Days): Agency pressure rises, but settlement discounts remain small.
Loss Pool (180+ Days): Full loan write-off applies. To recover cash, senior managers can approve One-Time Settlements with 40% to 70% waivers and 100% late fee cuts.
Starting talks after 180 days puts you in contact with managers who have the authority to grant deep discounts.
5. Tata Capital Housing Finance (TCHFL) & SARFAESI Limits
Home loans from Tata Capital Housing Finance Limited (TCHFL) are backed by property mortgages. If a home loan defaults, SARFAESI Act rules apply.
Under Section 13(2) of the SARFAESI Act, the lender sends a demand notice giving you sixty days to pay overdue installments. If unpaid, they can issue a Section 13(4) notice to take possession of the home.
You have the right to file a written reply within fifteen days under Section 13(3A). You can also challenge illegal possession actions before the Debt Recovery Tribunal (DRT) under Section 17.
6. Tata Neu Credit Cards & Co-Brand Recovery Separation
Many borrowers confuse the Tata Neu credit card with a Tata Capital loan.
The Tata Neu credit card is issued and managed entirely by HDFC Bank. Tata Capital has no control over it.
If your Tata Neu credit card defaults, you must negotiate directly with HDFC Bank Credit Card Collections under HDFC settlement rules. Tata Capital cannot settle this card for you.
7. Business Loans & MSME Working Capital Compromise
Tata Capital offers business loans and MSME credit lines. If your business suffers losses, you have options for relief.
Under RBI MSME restructuring rules, distressed businesses can ask for longer loan tenures or temporary payment pauses.
If the business closes, unsecured business loans can be settled through a One-Time Settlement with 40% to 60% discounts based on real proof of loss.
8. National Lok Adalat: Compromise with Judicial Immunity
National Lok Adalat is the safest place to settle a defaulted Tata Capital loan. Held every quarter across India by NALSA, Lok Adalat offers dispute talks under the Legal Services Authorities Act, 1987.
Senior Tata Capital officers attend these sessions. Judges act as neutral helpers who review your hardship and encourage fair settlements, including big waivers on late interest and fees.
A Lok Adalat order acts as a final civil court decree under Section 21 of the Legal Services Authorities Act. It is binding on both sides and cannot be challenged in appeal. Settling through Lok Adalat gives you complete legal safety against future recovery calls.
When EMIs bounce, Tata Capital law panels send notices threatening Section 25 PSS Act actions or one-sided arbitration hearings in Mumbai.
Follow these clear steps to respond:
Section 25 Reply: Reply within fifteen days. State your financial hardship and willingness to resolve dues. This is a civil money dispute, not a non-bailable crime.
Object to Arbitration: Challenge sole arbitrator appointments in Mumbai citing Section 12(5) and the Perkins Eastman precedent.
Demand Loan Ledger: Ask for your complete loan statement to check for unfair interest and penalty charges.
10. Central Collections Sanction Audit, 30-Day NOC & CIBIL
Never pay money without checking the settlement letter first. Follow these safety rules:
Official Letterhead: The letter must come on official Tata Capital letterhead from the Central Collections Desk in Mumbai.
Verify Details: Check that your name, loan number, PAN, and settlement amount match your records exactly.
Full Discharge: The letter must state that once you pay the agreed sum, all remaining dues are waived in full.
Pay Direct: Transfer money into official Tata Capital bank accounts. Never pay cash to an agent.
Get Your NOC: Under RBI rules, Tata Capital must issue your formal No Dues Certificate within 30 days of payment.
Settling a loan drops your CIBIL score by 75 to 150 points. You can rebuild your credit back above 750 within 18 to 24 months by getting a secured fixed-deposit credit card and paying all bills on time.
11. Tata Capital Loan Default & Settlement FAQs
Verified answers on Tata Capital loan default, recovery limits, and credit rebuilding.
Can Tata Capital freeze my bank accounts through arbitration without my consent?▼
No. Under Supreme Court rulings in Perkins Eastman and Bombay High Court orders, an arbitrator picked by only one side has no legal power under Section 12(5) of the Arbitration Act. Such an award cannot freeze your bank accounts without a civil court order.
How much waiver can I negotiate on a defaulted Tata Capital personal loan?▼
On personal loans past 180 days default (NPA pool), Tata Capital managers can grant One-Time Settlements (OTS) with 40% to 70% waivers on total dues, plus full waivers on late fees and extra interest.
Can Tata Capital recovery agents visit my home or workplace after 7 PM?▼
No. Under RBI rules and Section 351 of the Bharatiya Nyaya Sanhita (BNS, 2024), collection agents cannot call or visit before 8:00 AM or after 7:00 PM. They cannot call your family or use threats.
Can I settle my Tata Neu credit card through Tata Capital?▼
No. The Tata Neu credit card is run and issued by HDFC Bank. Tata Capital does not manage it. To settle a Tata Neu card, you must negotiate directly with HDFC Bank Credit Card Collections.
Is an education loan or personal loan default with Tata Capital a criminal offense?▼
No. Defaulting on a personal loan is a civil matter under Indian law. Police cannot arrest you or call you to a police station for an unpaid loan balance. An auto-debit bounce notice is a money recovery tool, not a jail warrant.
Can Tata Capital seize my house under SARFAESI for an unpaid personal loan?▼
No. The SARFAESI Act applies only to secured mortgage loans backed by registered property deeds. Unsecured personal loans have no claim on your house and cannot trigger SARFAESI property auctions.
How can I settle my Tata Capital loan through National Lok Adalat?▼
Tata Capital sends stressed loan files to quarterly National Lok Adalat drives under NALSA. You can ask your loan manager to list your file. Settlements passed by a Lok Adalat bench act as a civil court decree and give you permanent legal closure.
How do I verify that a Tata Capital settlement sanction letter is genuine?▼
A real letter comes on official Tata Capital letterhead from the Central Collections Desk in Mumbai. It shows your loan number, PAN, and exact settlement sum. Pay only into your official Tata Capital loan account, never to an agent.
How long does Tata Capital take to issue a No Dues Certificate (NOC) after settlement?▼
Under RBI rules, lenders must give you a formal No Dues Certificate within thirty days of full settlement payment. Any unfair delay beyond 30 days entitles you to delay compensation of ₹5,000 per day.
How does a Tata Capital loan settlement affect my CIBIL credit score?▼
Settling for a discount marks the loan as Settled in credit bureau files. This drops your score by 75 to 150 points. You can rebuild your score back above 750 in 18 to 24 months by using a secured credit card backed by a fixed deposit.
Statutory Redressal
Tata Capital 4-Tier Grievance Escalation Ladder
Follow the statutory protocol when recovery telecallers breach RBI conduct rules or you receive unilateral arbitration notices.
Tier 1Customer Service & Branch Operations Desk
SLA: 7 Days
Jurisdiction: Home Branch / Retail Loan Processing Unit
Action: Log formal hardship representation. Request statement of account separating base principal from penal interest and late fees.
Tier 2Grievance Redressal Officer (GRO)
SLA: 14 Days
Jurisdiction: Centralized Escalations Unit (Level 2)
Channel: Official Web Escalation: tatacapital.com/contact-us/customer-grievances.html
Action: Escalate if Tier 1 fails to respond within 7 days or recovery telecallers breach RBI guidelines by calling outside 8 AM to 7 PM.
Tier 3Principal Nodal Officer (PNO)
SLA: 30 Days Statutory SLA
Jurisdiction: Tata Capital Head Office, Lower Parel, Mumbai
Channel: nodalofficer@tatacapital.com | Peninsula Business Park, Lower Parel, Mumbai - 400013
Action: Lodge formal grievance against unilateral arbitrator appointment violating Perkins Eastman, harassment violating Tata Code of Conduct, or delayed NOC.
Tier 4RBI Integrated Ombudsman
SLA: 30+ Days Post-PNO
Jurisdiction: Reserve Bank of India (Statutory Authority)
Channel: Online via cms.rbi.org.in | CRPC Chandigarh (Toll-Free 14448)
Action: Statutory arbitration for regulatory non-compliance, refusal to issue No Dues Certificate within 30 days of payoff, or claiming delay compensation of ₹5,000/day.
Click the button above to copy this formal representation letter. Fill in your bracketed details and dispatch it directly to nodalofficer@tatacapital.com to establish a binding legal paper trail.
To: The Principal Nodal Officer, Tata Capital Limited
11th Floor, Tower A, Peninsula Business Park,
Ganpatrao Kadam Marg, Lower Parel, Mumbai - 400013
Email: nodalofficer@tatacapital.com
Phone: 1860 267 6060

Subject: Urgent Grievance - Stressed Loan Account No: [INSERT LOAN ACCOUNT NUMBER] / Objection to Unilateral Arbitration & Request for Amicable Compromise Settlement

Respected Sir/Madam,

I am a retail borrower with Tata Capital Limited holding Loan Account Number [INSERT ACCOUNT NUMBER]. Due to unexpected and severe financial insolvency resulting from [BRIEFLY STATE REASON: job loss, business collapse, critical medical emergency], I was involuntarily unable to service the regular monthly installments.

I am writing to register an urgent formal grievance regarding the following statutory and regulatory violations:
1. Objection to Unilateral Arbitrator Appointment: I have received an arbitration notice regarding the appointment of a sole arbitrator without my mutual written consent. Under the landmark Supreme Court ruling in Perkins Eastman Architects DPC vs. HSCC (India) Ltd. and recent Bombay High Court rulings in Tata Capital vs. Jaikishan Subramanian (2026), unilateral appointment of a sole arbitrator is void ab initio under Section 12(5) of the Arbitration and Conciliation Act, 1996. I formally object to the jurisdiction of any unilaterally appointed arbitrator.
2. Violation of Tata Code of Conduct (TCOC) & RBI Fair Practices Code: Outsourced recovery telecallers representing Tata Capital have repeatedly violated the RBI Fair Practices Code and Section 351 of the Bharatiya Nyaya Sanhita (BNS) by [DESCRIBE HARASSMENT: calling outside 8 AM to 7 PM / contacting third parties / issuing verbal threats].

I request your urgent intervention to:
a. Freeze all compounding penal interest and late bounce charges on my delinquent account.
b. Route my loan account to the Central Collections Desk or refer the matter to the upcoming National Lok Adalat bench for an amicable One-Time Settlement (OTS).
c. Direct collection agencies to cease coercive tactics and adhere strictly to the Tata Code of Conduct.

Sincerely,
[YOUR NAME]
[YOUR MOBILE NUMBER]
[YOUR REGISTERED EMAIL]
Official Tata Capital NBFC & RBI Grievance Portals: