SBI Loan Settlement Process & OTS Rules in India
How to Settle SBI Personal, Credit Card & Home Loans
Settling a loan with State Bank of India (SBI) is strictly rule-based-branch managers cannot make informal deals because every written-off rupee is audited by government vigilance officers. This guide explains how SBI's official Rinn Samadhan scheme works, how to secure a 50% to 75% waiver, and how to protect your savings.
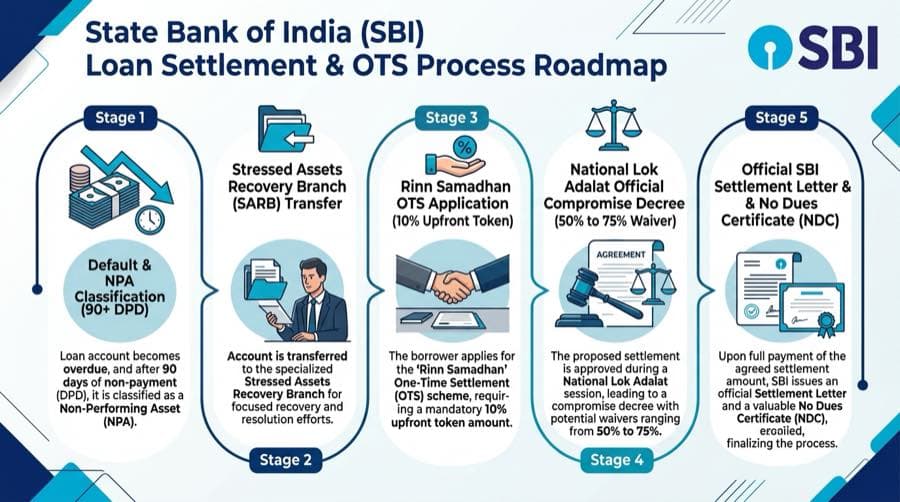
To settle an SBI loan or credit card for a 50% to 75% discount, your account must be delayed past 3 to 6 months (NPA status). Local SBI branch managers cannot give discounts-settlements are approved strictly under SBI's official Rinn Samadhan Scheme by the Stressed Assets Recovery Branch (SARB). Under this scheme, you pay a 10% token upfront, another 10% within 30 days of approval, and clear the remaining 80% within 90 days. Crucial: move your salary out of SBI immediately to stop the bank from freezing your savings (Section 171 Banker's Lien).
SBI Loan Settlement & Haircut Estimator
Unsecured retail portfolio. Eligible for Rinn Samadhan OTS sacrifice matrix once transferred to SARB.
Status: Optimal Settlement: Transferred to SARB AGM Desk
SBI 4-Stage Escalation & Grievance Matrix
Because SBI is a Public Sector Bank governed by vigilance norms and CVC rules, recovery agents often mislead borrowers regarding who can approve an OTS. Follow this 4-tier statutory ladder to bypass low-level recovery pressure:
Branch Manager & Retail Assets Central Processing Centre
Can discuss standard loan restructuring or tenure extension. Branch Managers carry ₹0 bad-debt haircut authority for NPA accounts.
Assistant General Manager (AGM) / Deputy General Manager (DGM)
The definitive authority for OTS. Holds delegated financial compromise powers under SBI Rinn Samadhan Sacrifice Matrix.
General Manager (Customer Service), State Bank Bhavan, Mumbai
Apex regulatory desk. Intervenes immediately against abusive recovery agency conduct, illegal employer calls, or CVC non-compliance.
Emails: agmcustomer.lhobho@sbi.co.in | customercare@sbi.co.in
Reserve Bank of India (cms.rbi.org.in)
Statutory appellate authority under Section 35A of the Banking Regulation Act. Can award compensation up to ₹20 Lakhs for mental harassment and coercive recovery.
Pre-Drafted Legal Representation to AGM (SARB)
Demand cessation of recovery harassment while opening official Rinn Samadhan OTS talks.
TO:
The Assistant General Manager (AGM),
Stressed Assets Recovery Branch (SARB),
State Bank of India.

SUBJECT: FORMAL NOTICE FOR ONE-TIME SETTLEMENT (OTS) & CEASE-AND-DESIST OF RECOVERY HARASSMENT
LOAN A/C NO: [INSERT 11-DIGIT SBI A/C]
BORROWER NAME: [INSERT YOUR FULL NAME]

Respected Sir/Madam,

1. I am the borrower of the aforementioned loan account with State Bank of India. Due to genuine, verifiable financial hardship resulting from [insert reason: involuntary job loss / catastrophic medical emergency / business failure], I have experienced acute distress and was unable to service regular EMIs.

2. I hereby express my bona fide intent to amicably resolve this account under the State Bank of India Rinn Samadhan Scheme / Compromise Settlement Policy. I propose a lump-sum One-Time Settlement (OTS) representing the sustainable recovery value, supported by my enclosed financial disclosures.

3. NOTICE TO RESTRAIN THIRD-PARTY RECOVERY AGENTS:
Despite my continuous willingness to engage through official banking channels, I and my family members are being subjected to persistent harassment, abusive calls during unsanctioned hours, and unauthorized outreach by third-party recovery agents representing SBI.

This violates:
- Reserve Bank of India (RBI) Master Circular on Fair Practices Code for Lenders;
- Section 351 of the Bharatiya Nyaya Sanhita (BNS), 2024 (Criminal Intimidation);
- Hon'ble Supreme Court directives in ICICI Bank v. Prakash Kaur (2007).

I request your office to:
a) Immediately instruct your empaneled recovery agencies to cease all non-statutory calls and personal visits;
b) Direct all future communications strictly in writing via registered post or official email;
c) Place my settlement proposal before the competent Committee for issuance of a formal, written OTS Sanction Letter specifying the net compromise figure and bank payment account.

Yours sincerely,
[Your Name]
[Your Contact Number]
[Your Address]
Dated: 16 September 2026
The SBI Settlement Reality: Public Sector Banking Mechanics
As a public sector bank, State Bank of India (SBI) cannot offer informal or arbitrary settlements. If an officer waives debt without adhering to official circulars, government anti-corruption bodies (the Central Vigilance Commission - CVC, and the CAG) can initiate vigilance inquiries. For this reason, all settlements follow strict institutional rules:
The Three Inflexible Rules of SBI Recovery:
- Your Local Branch Manager Has Zero Power: Branch managers are personally responsible for collecting full EMIs. They carry zero legal authority to give you a discount on your loan balance. Do not waste your time pleading at local branches.
- Files Move to the SARB Office: Once your loan is unpaid for 6 months (180 days), your file is taken away from the local branch and transferred to SBI's specialized Stressed Assets Recovery Branch (SARB) headed by an Assistant General Manager (AGM).
- Decisions are Made by a Committee: No single officer decides your settlement. A committee of senior bank managers reviews your hardship proof against an official government formula. This protects you from bribes or secret deals.
Understanding this public-sector rulebook is your greatest advantage. It means SBI officers will never accept bribes, cannot make false promises, and must follow published compromise circulars.
The Rinn Samadhan Scheme: SBI's Flagship OTS Framework
To resolve bad debts without dragging citizens into endless court cases, SBI periodically runs its official settlement scheme called the Rinn Samadhan Scheme. This scheme provides transparent, formulaic discounts to honest borrowers who cannot repay due to genuine financial trouble.
1. 100% Penal Interest & Charges Removed: All accumulated penalty interest, late fees, and bounce charges added after your default are completely cancelled.
2. 45% to 75% Discounts on Principal: If your unsecured loan has been overdue for over 1 to 2 years, the committee can approve a 45% to 75% waiver on the remaining balance.
3. The Easy 10-10-80 Payment Rule: You do not need all the money at once. You pay a mandatory 10% token deposit with your application, pay another 10% within 30 days of receiving your approval letter, and pay the remaining 80% balance within 90 days.
4. 5% Extra Early-Bird Discount: If you can pay the entire agreed settlement amount in one single payment within 30 days of approval, SBI gives you an extra 5% cash discount!
Note: As confirmed by the Supreme Court in AGM, SBI v. Tanya Energy Enterprises, a settlement is an internal bank policy concession, not an automatic legal right. Following deadlines and payment terms is strictly required.
The Banker's Lien (Section 171) Trap in SBI
This is the single most dangerous mistake borrowers make with an SBI default: keeping money in an SBI savings, pension, or salary account.
Under Section 171 of the Indian Contract Act, 1872, a bank has the legal right to pull money from any account you hold with them to pay off your overdue debts. Because all SBI accounts across India are linked to your PAN card, the moment you miss payments:
- The day your monthly salary or pension lands in your SBI savings account, the bank will automatically sweep it away.
- Your Fixed Deposits (FDs) and Recurring Deposits (RDs) will be broken and taken.
- Your SBI debit card and UPI (Google Pay / PhonePe) will suddenly stop working.
Your #1 Survival Step: At least 60 days before your first missed EMI, open an operational savings account in a completely different private bank (such as Axis, ICICI, or Kotak) and route your salary, freelance earnings, and family emergency money there. Never leave your living expenses inside SBI while negotiating a settlement.
SBI Xpress Credit & Personal Loan Playbook
SBI Xpress Credit personal loans are unsecured (no house, car, or gold pledged). Because there is no collateral, the bank cannot seize your property or auction your home.
SBI Credit Card Settlement: Why Your Local Branch Cannot Help
Your local SBI bank branch manager cannot help you settle an SBI credit card.
The Important Difference You Must Know:
SBI Cards is operated by SBI Cards and Payment Services Limited, a completely separate company listed on the stock market. It is not an internal department of your local bank branch.
- Credit card defaults are handled by SBI Card's centralized head office located in Gurugram (Gurgaon), Haryana.
- Unpaid interest on SBI credit cards compounds monthly at a staggering 42% to 45% annual rate (APR) plus 18% GST on all late fees.
- When you negotiate a settlement with SBI Card officers, ignore their inflated statement bill. Demand that 100% of the late fees and finance charges be removed, and negotiate a 50% to 70% discount on your original shopping principal.
SBI Home Loan Settlement & SARFAESI Act Defense
Can you get a 50% discount on an SBI home loan? No. SBI will never agree to a principal haircut on a home loan because they physically hold your original property papers (Registry / Sale Deed). Under Indian law (the SARFAESI Act, 2002), if you stop paying, the bank has the legal right to take possession and auction the house.
ibapi.in, they sell it cheap (20% to 30% below market value), destroying your life savings. Selling it yourself lets you pay off SBI in full and keep the remaining cash.SBI Gold Loan Default & Section 176 Auction Rules
If you pledged family gold with SBI and stopped paying interest, the bank cannot quietly melt or confiscate your family jewelry. Under Section 176 of the Indian Contract Act, 1872, you have 3 strict legal protections:
Your Legal Rights Under Section 176:
- Mandatory 14-Day Registered Notice: SBI must send you an individual registered letter and publish public auction notices in local newspapers giving you 14 full days to clear the dues.
- Fair Government Price Floor: The public auction price cannot fall below 90% of the official 30-day average market gold price. They cannot sell your gold at cheap throwaway prices.
- Extra Money Must Be Returned to You: If your gold sells for ₹3,50,000 and your total loan was ₹2,50,000, SBI is legally required to send that extra ₹1,00,000 back to your bank account.
Legal Notices: Section 138, Section 25 & Section 351 BNS Shields
When an SBI loan defaults, bank panel advocates send legal notices to push you to pay. Here is what they actually mean in plain words:
National Lok Adalat: SBI's Largest Settlement Channel
State Bank of India is the single largest participant in the quarterly National Lok Adalat organized by the government (NALSA). If you receive a notice to appear before a Lok Adalat bench, view it as an exceptional opportunity, not a threat!
Why Settle Before a Lok Adalat Bench?
- Direct Discounts on the Spot: SBI sends senior Assistant General Managers to Lok Adalat with pre-approved permission to grant 50% to 70% discounts right on the spot without waiting weeks for head office approval.
- Permanent Protection (No One Can Ever Harass You Again): The settlement signed at Lok Adalat has the power of a final civil court decree. SBI or any debt collection agency can never reopen your file or demand more money ever again.
- 100% Free: You pay zero court fees, zero lawyer charges, and zero stamp duties.
How to Pay SBI Safely Without Getting Cheated
Payment fraud is rampant in the loan settlement space. Over 30% of complaints happen because dishonest recovery agents collect money from panicked borrowers, give fake receipts, and disappear while the debt remains active. Follow these 4 strict rules:
1. Zero Cash Rule: Never hand over physical cash, cash bearer cheques, or demand drafts made out to any collection agent or agency name.
2. Pay Only into Your Loan Account: Payments must strictly be transferred via NEFT, RTGS, or branch cash deposit directly into: State Bank of India - A/C [Your Official 11-Digit Loan Account Number].
3. Have the Physical Letter First: Never deposit a single rupee until you hold an official, signed, stamped Settlement Sanction Letter issued on SBI letterhead.
4. Getting Your No Dues Certificate: SBI is required under RBI rules to issue your official physical No Objection Certificate (NOC) and No Dues Certificate (NDC) within 21 to 30 working days of final payment.
YONO SBI App Digital Settlement Offers
SBI frequently uses its YONO SBI mobile app or official SMS from sender ID SBIBNK to show pre-approved settlement offers to borrowers who are 3 to 6 months late.
How to Use a YONO Offer to Get a Bigger Discount:
If a popup appears on your YONO screen under 'Settlement Offers':
- Take a clear screenshot showing your loan number, the date, and the offer amount.
- Remember: the automated app offer is usually conservative and offers only a small 20% to 35% discount.
- Take that screenshot to your regional SARB branch as official proof that SBI has approved your loan for a settlement, and negotiate for a much deeper 50% to 70% waiver under the Rinn Samadhan Scheme by showing your genuine hardship proofs.
7 Checkpoints of a Real SBI Settlement Letter
Never pay until your settlement paper contains all 7 safety checkpoints:
SARB/OTS/2026/XXXX) traceable in SBI's computer system.@sbi.co.in email address-never from Gmail, Yahoo, or personal accounts.What Happens to Your CIBIL Score & How to Rebuild It
When an OTS settlement is finished, SBI updates CIBIL and other credit bureaus within 30 to 45 days.
The CIBIL Reality:
The account status will be marked as “Settled” (Post-Write-off) with a zero current balance. Your CIBIL score will drop initially (often 70 to 120 points), but all recovery calls, legal threats, and interest compounding stop permanently on that day.
Can You Change “Settled” to “Closed” in the Future?
Yes! If your finances improve 2 to 3 years later and you want to apply for a fresh home loan or visa, SBI allows you to pay back the discount amount that was originally waived (without adding extra interest). Once you clear that difference, SBI updates CIBIL to clean “Closed” with zero written-off balance.
How to Rebuild a 750+ CIBIL Score Fast:
Put ₹20,000 in a Fixed Deposit (FD) at any bank and take an FD-backed credit card. Spend a small amount each month and pay on time for 18 to 24 months. Your credit score will climb steadily back above 750+.
Frequently Asked Questions (FAQ)
Can an SBI personal loan or Xpress Credit loan be settled?▼
Yes! Once an unsecured SBI personal loan is delayed past 3 to 6 months (NPA status), your file shifts to the Stressed Assets Recovery Branch (SARB). Under SBI's official compromise rules or the Rinn Samadhan Scheme, borrowers routinely receive 50% to 75% discounts on total accumulated interest and a significant haircut on the principal balance.
Can my local SBI branch manager approve my loan settlement?▼
No. Local SBI branch managers have exactly ₹0 authority to reduce your loan dues. By system rule, defaulted accounts are transferred to the specialized Stressed Assets Recovery Branch (SARB), where decisions are made by senior committees headed by an Assistant General Manager (AGM). Do not waste your energy arguing at local branch counters.
What is the SBI Rinn Samadhan Scheme?▼
Rinn Samadhan is SBI's official, government-approved settlement program. It sets clear, transparent discount formulas so honest borrowers can close bad debts without endless court cases. It cancels 100% of penalty interest and late fees, allows 45% to 75% discounts on old loans, and follows a simple 10-10-80 payment plan (10% token deposit upfront, 10% within 30 days of approval, and the remaining 80% within 90 days).
Is SBI Cards the same entity as State Bank of India?▼
No. SBI Cards is a completely separate company (SBI Cards and Payment Services Ltd) listed on the stock exchange. Credit card settlements are handled exclusively by SBI Card's centralized recovery office in Gurgaon, Haryana-not by your local SBI bank branch manager.
Can SBI freeze my savings or salary account if I default on an SBI loan?▼
Yes! Under Section 171 of the Indian Contract Act (Banker's Right of Set-Off), SBI can legally pull money directly from any savings, salary, or fixed deposit account linked to your PAN card to pay off your overdue loan without asking you. To protect your family's essential living expenses, move your salary to a completely different private bank (like Axis or ICICI) before you miss an EMI.
Can an SBI home loan be settled with a principal haircut?▼
No. Because home loans are backed by your house papers, SBI will never give a discount on the principal loan amount. Under the SARFAESI Act, 2002, the bank can auction the house. However, you can negotiate to wipe out 100% of the late penalty interest, or ask for 90 days to sell the house yourself in the market to protect your hard-earned savings.
What happens if my SBI gold loan defaults?▼
Under Section 176 of the Indian Contract Act, SBI cannot secretly melt or sell your gold. They must send you a registered notice giving you 14 full days to clear the dues, and the auction price must match at least 90% of market gold rates. If your gold sells for more than what you owed, SBI is legally required to return the extra money to your bank account.
What legal notices does SBI issue for loan defaults?▼
SBI issues notices under Section 138 (for bounced physical cheques) or Section 25 (for bounced auto-debit EMIs). These are legal notices requiring a reply within 15 days, and responding through a lawyer typically moves the file to Lok Adalat for an affordable settlement. If any recovery agent threatens you or abuses you, you are protected under Section 351 of the Bharatiya Nyaya Sanhita (BNS), 2024.
Why is National Lok Adalat the best place to settle an SBI debt?▼
National Lok Adalats are government-organized settlement courts held every 3 months. SBI sends senior managers who have pre-approved powers to grant 50% to 70% discounts on the spot. Best of all, a Lok Adalat order has the power of a final civil court decree-meaning the bank can never ask you for money again, and it is 100% free with zero court fees.
How should I make payment once an SBI settlement is approved?▼
Never pay cash or transfer money to any recovery agent's personal account or UPI ID. All payments must be deposited directly into your official 11-digit SBI Loan Account number via NEFT/RTGS or at a branch cash counter against an official, signed, stamped SBI settlement letter.
What is the turnaround time for receiving the SBI No Dues Certificate (NDC)?▼
Once your final settlement payment reflects in SBI's computer system, the bank is required by RBI rules to issue your official physical No Objection Certificate (NOC) and No Dues Certificate (NDC) within 21 to 30 working days.
Can a "Settled" SBI account be converted to "Closed" in CIBIL later?▼
Yes! If your financial situation improves 2 to 3 years later, you can approach the bank, pay back the remaining discount amount that was originally waived (without any extra interest), and SBI will update CIBIL to clean "Closed" status with a fresh No Dues Certificate.
Official Statutory Resources & Regulatory Portals
RBI & GOVT VERIFIEDAccess the official government portals and statutory frameworks governing banking recovery, consumer grievance redressal, and borrower rights: