HomeAbout
BlogSoon
Bank specific setupSoon
LocationsSoon
WARNING: THIS IS NOT LEGAL ADVICE. THIS IS SURVIVAL ADVICE BASED ON REAL BORROWER EXPERIENCE.
UPDATED: SEPTEMBER 2026

RBL Bank Loan Settlement Process & OTS Rules in India

How to Settle RBL Cards, Bajaj SuperCard & Debt

If you are struggling with unpaid RBL Bank credit cards, Bajaj Finserv SuperCards, or unsecured personal loans, you are not alone - and you have legal rights. This practical guide shows you how to handle recovery agency calls, avoid bank account freezes under Section 171, and negotiate an official One-Time Settlement (OTS) directly with RBL Bank to close your debt for 40% to 65% less.

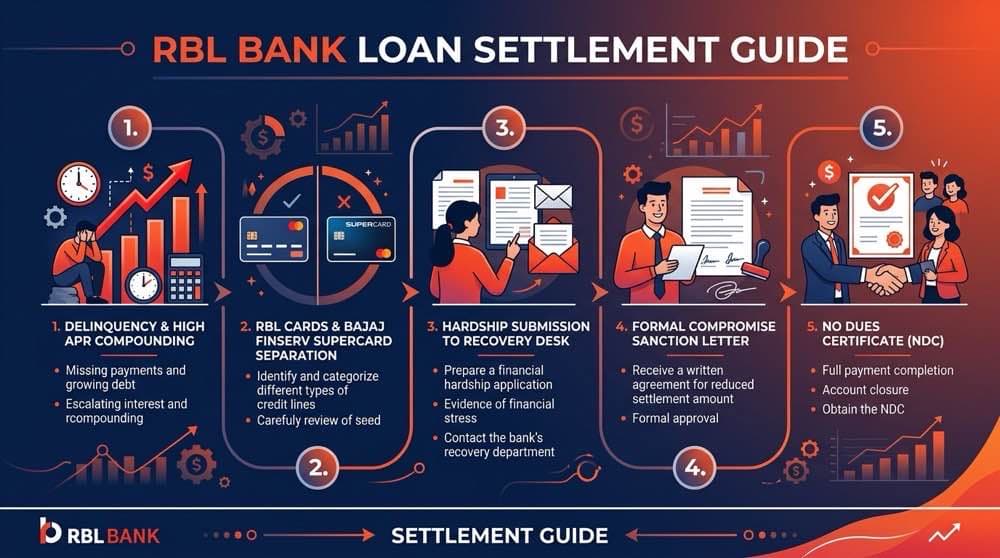
RBL Bank Loan Settlement Process and SuperCard Debt Relief Roadmap

Visual Roadmap: Official settlement hierarchy and compromise procedure across RBL Bank branches and recovery offices.

Quick Answer Summary

RBL Bank resolves stressed credit cards (including extensive Bajaj Finserv co-branded cards) and unsecured personal loans through centralized recovery desks and collection agencies. Delinquent accounts past 90 to 180 DPD can secure 100% waiver of accumulated finance charges (which compound up to 47.8% APR) and 40% to 60% principal write-offs. Beware of aggressive automated digital calling bots and Section 25 PSS notices for bounced NACH mandates. Settlements executed before the National Lok Adalat provide a binding judicial decree under Section 21 of the Legal Services Authorities Act, permanently extinguishing pending Section 138 cheque bounce and Section 25 PSS cases.

1. RBL Bank Portfolio Landscape & Credit Surge

Originally established in 1943 in Kolhapur, Maharashtra as The Ratnakar Bank Limited, RBL Bank underwent a massive strategic reinvention over the past decade. Transforming into a high-octane private sector player with primary corporate operations at One World Center in Mumbai and Mahavir Chambers in Pune, the bank aggressively expanded into retail consumer credit, unsecured personal loans, business installment credit, and revolving credit cards.

Through innovative digital partnerships, fintech co-lending ventures, and widespread retail distribution, RBL Bank issued millions of credit cards across urban and semi-urban India. However, this aggressive expansion also generated significant delinquency volumes when borrowers encountered job loss, inflation shocks, or unforeseen medical expenses.

Because RBL Bank operates as a modern private commercial lender, its collections and recovery machinery is highly automated. Understanding how the bank structures its stressed asset write-offs allows defaulting borrowers to negotiate structured compromise settlements with significant haircuts.

2. The Bajaj Finserv RBL SuperCard Dichotomy

The single largest source of borrower confusion in RBL Bank defaults involves the Bajaj Finserv RBL Bank SuperCard. Because the card features prominent Bajaj Finserv branding alongside RBL Bank logos, borrowers frequently misunderstand the legal ownership of the debt:

Key Legal Realities of the Bajaj SuperCard:
  • RBL Bank is the Sole Legal Creditor: Bajaj Finserv is merely the co-branding marketing and sourcing partner. Under RBI licensing rules, NBFCs like Bajaj Finance cannot issue credit cards independently. RBL Bank holds the banking license, extends the credit limit, and provisions for non-performing accounts.
  • Legal Notices Emanate from RBL Bank: Any statutory notice under Section 138 of the Negotiable Instruments Act or Section 25 of the Payment and Settlement Systems Act is filed by RBL Bank's legal department.
  • Settlement Sanction & NDC Authority: Compromise letters and No Dues Certificates must be issued directly by RBL Bank Limited. Paying settlement amounts into third-party Bajaj accounts without an official RBL Bank sanction letter is dangerous and invalid.

3. The 47.9% APR Debt Trap & Compounding Penalties

RBL Bank credit cards feature among the highest finance charges in the Indian private banking sector:

Monthly Finance Charge: Revolving charges range between 3.49% and 3.99% per month, compounding to an effective Annual Percentage Rate (APR) of 41.88% to 47.88%.
Late Payment Penalties: Slabs up to ₹1,300 are debited every billing cycle whenever the minimum amount due is unpaid.
18% GST Levy: Every rupee of interest and late payment charges is subjected to 18% Goods and Services Tax, creating a vicious debt spiral where interest is charged on top of tax.

In a compromise settlement negotiation, borrowers should insist on stripping out 100% of accumulated finance charges, late fees, and compounding GST, anchoring negotiations solely on the net principal balance.

4. Internal Recovery Desks & Section 171 Banker's Lien

RBL Bank organizes its recovery apparatus across distinct delinquency stages, accompanied by strict account control mechanisms:

● Early Collections (1 - 89 DPD): Managed by centralized call centers and tele-calling vendors. Their goal is extracting minimum payments. They possess zero authority to sanction principal write-offs.

● NPA & Field Collections (90 - 180 DPD): Assigned to third-party recovery agencies for physical residential visits and legal pre-litigation notices under Section 25 PSS Act.

● Stressed Assets Desk (180+ DPD): Internal Credit Card & Retail Settlement Desks based at Mumbai and Pune. Authorized managers can approve substantial compromise haircuts to remove bad loans from active ledgers.

● ARC Portfolio Assignment: Chronic bad debts past 2 to 3 years may be sold or assigned to registered Asset Reconstruction Companies (ARCs) under Section 5 of SARFAESI.

Section 171 Banker's General Lien Immediate Protection Protocols:
  • If you hold an active RBL Bank savings account, salary account, or fixed deposit, any funds deposited will be immediately swept and debited against your defaulted credit card or personal loan.
  • Joint accounts with family members can also be placed on administrative debit holds.
  • Prior to crossing 60 days delinquent, redirect all salary deposits and emergency reserves to an independent banking institution where you have zero credit relationships.

5. Loan Products Breakdown & Realistic Haircuts

Settlement benchmarks across RBL Bank's product spectrum:

Credit FacilityCollateral TypeInterest / Penal WaiverExpected Principal Haircut
Bajaj Finserv RBL SuperCardUnsecured Revolving100% Finance Charges45% - 65%
Standalone RBL Credit CardUnsecured Revolving100% Finance Charges45% - 65%
RBL Personal LoanUnsecured Clean100% Penal Interest40% - 60%
Business Installment Loan (BIL)Unsecured MSME100% Penal Interest35% - 55%
RBL FinServe MicrofinanceJoint Liability Group100% Penal Interest50% - 70%
⚡ Empirical CalculatorCO-BRANDED REVOLVING

RBL Bank & SuperCard Settlement Estimator

Calculate realistic One-Time Settlement (OTS) compromise ranges based on RBL Bank recovery circulars and SuperCard provisioning metrics.

Co-branded credit card with aggressive collection agency outsourcing and high compounding finance fees.

₹3,00,000
₹25,000₹25,00,000₹50,00,000
Target Settlement Offer:60%–72% Haircut
Realistic Settlement Range:₹84,000₹1,20,000
Estimated Debt Forgiven:₹1,80,000₹2,16,000
*100% of accumulated finance charges, bounce penalties & GST waived on OTS compromise.
⚠️
RBL Bank Recovery Caveat:RBL Bank collection calls are outsourced to secondary collection centers. Demand written settlement approval from RBL Bank official domain (@rblbank.com) before paying.

6. Statutory Legal Defenses (Sec 138, 25 PSS) & Lok Adalat

When payments default, RBL Bank issues formal legal notices under Section 25 of the Payment and Settlement Systems Act, 2007 (for dishonored NACH auto-debits) or Section 138 of the Negotiable Instruments Act, 1881:

1. Bailable Offense & Statutory Defense: These proceedings are quasi-criminal recovery mechanisms designed to compel settlement. They are fully bailable and do not result in immediate arrest. You have 15 days from notice receipt to submit a formal legal response establishing bona fide financial hardship.
2. National Lok Adalat Judicial Compromise: An award passed by a National Lok Adalat carries the exact authority of a civil court decree under Section 21 of the Legal Services Authorities Act, 1987. It legally dissolves all pending Section 138 NI Act or Section 25 PSS Act complaints permanently with zero court fees.

7. Sanction Verification, Direct Remittance & 30-Day NDC SLA

Navigating an RBL Bank settlement from initial proposal to unconditional closure requires disciplined execution:

1. Genuine RBL Bank Letterhead: The sanction letter must be printed on official RBL Bank Limited letterhead, displaying your complete card/loan account number, approved settlement amount, and payment deadline. Never accept WhatsApp text confirmations.
2. Direct CBS Remittance: Pay settlement funds directly into your RBL Bank credit card or loan account through NEFT/RTGS using official net banking. Never pay cash or UPI to third-party agency representatives.
3. 30-Day Mandatory Release (RBI/2023-24/60): Under RBI directions, RBL Bank is legally required to issue the No Dues Certificate within 30 days of full settlement payment. Any delay beyond 30 days entitles the borrower to ₹5,000 daily compensation.
4. Post-Settlement CIBIL Rehabilitation: Verify bureau status reflects “Settled” with zero balance, then rebuild your credit score back above 750 over 18 to 24 months using a fixed-deposit backed credit card.
Tier 1

Credit Card & Retail Customer Helpline

SLA: 7 Working Days

Frontline Customer Support Desk

Initial dispute registration, billing statement reconciliation, and APR charge verification.

National Helplines: 022 6232 7777 / 1800 120 616161 | Email: cardservices@rblbank.com
Tier 2

Regional Nodal Officer (RNO)

SLA: 7 - 10 Working Days

Regional Grievance Head (Mumbai / Delhi / Bengaluru / Pune)

Stalled compromise requests, Bajaj SuperCard co-branded confusion, and collection agency harassment incidents.

Regional Offices | Email: regionalnodalofficer@rblbank.com | Portal: rblbank.com/grievance
Tier 3

Principal Nodal Officer (PNO)

SLA: 15 Working Days

Principal Nodal Officer, RBL Bank Limited

Apex bank authority for severe recovery misconduct, criminal intimidation complaints, and final OTS review.

One World Centre, Tower 2B, 9th Floor, 841, Senapati Bapat Marg, Lower Parel West, Mumbai - 400013 | Phone: 022 7143 2700 | Email: principalnodalofficer@rbl.bank.in
Tier 4

RBI Banking Ombudsman (Statutory Regulator)

SLA: 30 Days Post-PNO

Reserve Bank of India Consumer Education and Protection Cell

Binding statutory adjudication under the Reserve Bank - Integrated Ombudsman Scheme, 2021.

Portal: cms.rbi.org.in | Toll-Free: 14448 | Postal: CRPC, RBI, 4th Floor, Sector 17, Chandigarh - 160017

Formal Harassment & Settlement Escalation Notice Template

Send this formal legal dispute notice directly to the Principal Nodal Officer before filing a complaint on the RBI CMS portal:

Subject: URGENT: Illegal Collection Harassment & Formal Compromise Settlement Submission - Card/Loan A/C [Your Account Number]

To:
The Principal Nodal Officer, RBL Bank Ltd. (principalnodalofficer@rbl.bank.in)
Copy: Regional Nodal Officer (regionalnodalofficer@rblbank.com)

Respected Sir/Madam,

I am writing regarding my [RBL Credit Card / Bajaj Finserv RBL SuperCard / Personal Loan Account Number: Your Account Number]. Owing to documented severe financial hardship [state reason: job loss / severe medical illness / business failure], I am unable to maintain payments against high compounded finance charges.

I have submitted an application for an amicable One-Time Settlement (OTS) to resolve this debt in full. Regrettably, third-party collection agents representing RBL Bank have subjected me to persistent telephone intimidation, calls to family contacts, and unannounced visits outside permitted hours (08:00 to 19:00), in blatant violation of the RBI Master Direction on Fair Practices Code.

I formally request your urgent intervention to:
1. Direct collection teams to halt coercive tactics immediately and communicate exclusively through official email or registered mail.
2. Direct the Credit Card Settlement Desk to evaluate my compromise settlement proposal for a full and final resolution.
3. Provide an itemized statement of dues segregating pure principal spend from accumulated finance charges, late payment fees, and GST.

Sincerely,
[Your Full Name]
[Registered Mobile Number]
[Registered Communication Address]

8. Frequently Asked Questions (RBL Bank Debt Settlement)

Who do I negotiate with to settle a Bajaj Finserv RBL SuperCard?
Although Bajaj Finserv acts as the co-branding and sourcing partner, RBL Bank Limited is the licensed banking entity that extends the credit line and carries the loan on its balance sheet. When an account defaults past 90 days into NPA, legal notices, compromise sanction letters, and No Dues Certificates (NDC) are issued strictly by RBL Bank's Stressed Assets and Credit Card Recovery Department. All formal settlement negotiations must be finalized directly with RBL Bank.
What finance charges apply when an RBL credit card defaults?
RBL Bank credit cards carry finance charges ranging from 3.49% to 3.99% per month, translating to an effective Annual Percentage Rate (APR) of up to 47.88%. Additionally, late payment charges up to ₹1,300 per cycle and 18% GST on all finance fees are compounded monthly. In an approved One-Time Settlement (OTS), borrowers can demand a 100% complete waiver of these accumulated finance charges and GST additions.
What percentage waiver can I realistically secure on an RBL credit card or SuperCard?
On revolving credit card debt delinquent beyond 180 to 365 days, negotiated compromise settlements routinely secure a 45% to 65% haircut on the pure principal transaction balance, alongside total cancellation of unbilled finance charges and late fees upon payment of an upfront lump sum.
Can RBL Bank freeze my savings account under Section 171?
Yes. Under Section 171 of the Indian Contract Act, 1872 (Banker's General Lien), RBL Bank core banking systems automatically place debit freezes or exercise right of set-off on any savings or fixed deposit account linked to the same Customer Identification File (CIF). Borrowers facing default must open an independent operating account with a completely unrelated bank before delinquency commences.
How does National Lok Adalat help in settling RBL Bank debt?
Settling through a National Lok Adalat bench yields a binding judicial compromise decree under Section 21 of the Legal Services Authorities Act, 1987. The Lok Adalat award carries the force of a final civil court decree, leaves zero right of appeal for the bank, and automatically dismisses and compounds all pending Section 138 cheque bounce or Section 25 PSS complaints.
What should I do if third-party collection agents use abusive language or make home visits?
Under the Reserve Bank of India Master Directions on Fair Practices Code, recovery agents are strictly prohibited from using abusive language, visiting homes outside 08:00 to 19:00, or contacting relatives and employers. Record all phone calls and preserve security footage. File a police complaint under Section 351 of Bharatiya Nyaya Sanhita (BNS) for criminal intimidation, and escalate the violation to RBL Bank's Principal Nodal Officer (principalnodalofficer@rbl.bank.in).
Can RBL Bank file a criminal case against me for credit card default?
No. The Supreme Court of India has consistently held that inability to repay an unsecured credit card or personal loan is a civil matter, not a criminal offense. The only criminal proceedings banks can initiate are Section 138 of the Negotiable Instruments Act (cheque bounce) or Section 25 of the Payment and Settlement Systems Act (NACH auto-debit bounce), which are bailable and routinely dismissed upon settlement.
How do I verify that an RBL Bank settlement sanction letter is genuine?
Never accept verbal assurances or informal WhatsApp messages from collection agents. A valid RBL Bank settlement sanction letter must be printed on official RBL Bank Limited letterhead, display a specific internal reference number, specify your exact 16-digit card or loan account number, clearly define the compromise amount and payment schedule, and bear the signature and employee code of an authorized bank manager.
How long does RBL Bank take to issue the No Dues Certificate (NDC)?
In accordance with RBI circular RBI/2023-24/60, RBL Bank is legally mandated to issue the formal No Dues Certificate within 30 days of receiving the final settlement payment. Failure to issue the NDC within 30 days makes the bank liable to pay statutory compensation of ₹5,000 for each day of delay to the borrower.
How does an RBL Bank settlement impact my CIBIL credit score?
The settled card or loan account will be reported to CIBIL, Experian, and CRIF High Mark as 'Settled' or 'Post-Write-Off Settled', causing a temporary score drop of 50 to 90 points. However, by obtaining a secured credit card backed by a small fixed deposit and servicing it with timely repayments, borrowers can rehabilitate their CIBIL score above 750 within 18 to 24 months.

Official Statutory Grievance Portals & Regulatory Sources:

Find this content helpful?

If this guide has helped you navigate your settlement journey, consider showing some support to keep this platform running.