Can I negotiate a loan settlement directly with my Canara Bank branch manager?▼
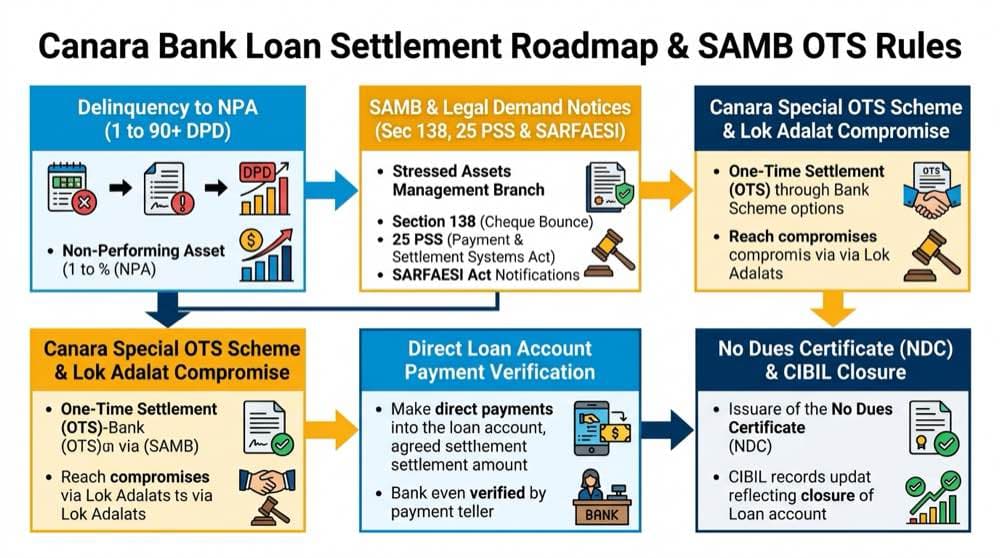
Branch managers in Canara Bank have very narrow discretionary compromise authority due to vigilance oversight by the Central Vigilance Commission (CVC) and statutory CAG audits. For meaningful waivers (40% to 65%), settlement proposals must be escalated to the Circle Recovery Section or Stressed Assets Management Branch (SAMB), or finalized during National Lok Adalat where settlements receive judicial sanction.
What is the Canara Special OTS Scheme and how does the formula work?▼
The Canara Special OTS Scheme is a board-approved, time-bound compromise framework for non-performing assets (NPAs). It uses fixed formula-based haircuts determined by asset vintage (Sub-Standard, Doubtful D1/D2/D3, or Loss). Wilful defaulters, fraudulent borrowers, staff loans, and matters under CBI investigation are strictly barred.
Can Canara Bank freeze my savings or pension account under Section 171?▼
Yes. Under Section 171 of the Indian Contract Act (Banker's General Lien), Canara Bank's Finacle CBS automatically attaches an internal freeze or debit hold on any savings, current, or term deposit account sharing the same Customer Information File (CIF). Borrowers facing financial distress should redirect living incomes and pensions to an independent bank prior to default.
What percentage waiver is realistic on an unsecured Canara Bank personal loan?▼
On unsecured retail debt such as Canara Budget personal loans or pensioner advances overdue beyond 180 to 365 days, negotiated settlements generally achieve 35% to 60% write-offs against total outstanding ledger balances, alongside complete 100% waivers on accumulated penal interest and penal levies.
Is Can Fin Homes Ltd the same as Canara Bank for loan settlement?▼
No. Canara Bank is a public sector commercial bank regulated directly by the RBI, whereas Can Fin Homes Ltd is a separately listed housing finance institution with its own independent credit policy, recovery machinery, and management board. Canara Bank branch staff cannot approve settlements on Can Fin Homes accounts.
Can Canara Bank auction my agricultural land under the SARFAESI Act?▼
No. Section 31(i) of the SARFAESI Act of 2002 expressly exempts agricultural land from securitization and enforcement proceedings. Canara Bank cannot take physical possession or conduct e-auctions of agricultural holdings without securing a decree through a competent civil court.
Why is National Lok Adalat the safest venue to settle with Canara Bank?▼
Settling through National Lok Adalat provides Canara Bank officers statutory immunity from internal vigilance inquiries, because the resulting award functions as a decree of a civil court under Section 21 of the Legal Services Authorities Act, 1987. It is final, binding, and non-appealable.
What interest rates apply when Canara Bank credit cards default?▼
Canara Bank credit cards carry finance charges up to 2.95% per month, compounding to approximately 35.4% to 42% annually when defaults trigger late fees and taxes. In an OTS negotiation, insist on stripping away all unbilled charges and compounding finance penalties before arriving at a net principal compromise.
How many days does Canara Bank have to issue my No Dues Certificate?▼
In accordance with RBI circular RBI/2023-24/60, Canara Bank must issue the No Dues Certificate and return all deposited original property or asset documents within 30 calendar days of receiving full settlement proceeds. Any unjustified delay triggers mandatory compensation of ₹5,000 per day payable to the borrower.
What happens to my CIBIL credit report after completing a Canara settlement?▼
Canara Bank reports the settled account status to TransUnion CIBIL, Experian, Equifax, and CRIF High Mark as 'Settled' rather than 'Closed'. This indicator depresses credit scores in the short term. However, disciplined credit habits and a secured credit card backed by a fixed deposit can restore scores above 750 within 18 to 24 months.
What is the Canara Bank OTS scheme for 2026 and who qualifies?▼
Canara Bank operates under a Board-approved Compromise Policy for 2025-26. NPA accounts classified as Sub-Standard, Doubtful, or Loss across MSME, Agriculture, and Retail segments are eligible. Wilful Defaulters and fraud accounts are excluded. You can pay the full settlement in one lump sum, or 10% to 25% upfront with quarterly installments over 12 to 24 months. Loans above Rs. 1 Crore need Settlement Advisory Committee (SAC) approval.
What is the difference between the Canara Bank SARB and the retail branch for settlements?▼
For loan exposures above Rs. 1 Crore, your NPA account is managed by the Circle SARB (Stressed Asset Recovery Branch), not the retail branch manager. The retail manager has near-zero authority to approve waivers on large accounts. Submit your written OTS application directly to the SARB in your zone. For loans below Rs. 50 Lakh, the retail Branch Head has limited powers. Mid-range cases go to SAMB (Stressed Asset Management Branch).