The Ground Reality of NBFC Loan Settlement.
NBFC & Fintech Loan Settlement & 25%–60% Waiver Guide
Digital lending apps like Navi, KreditBee, Kissht, CASHe, and MoneyView run on venture debt with zero in-app settlement options. Meanwhile, legacy giants like Bajaj Finance offer 40%–60% waivers but deploy the most aggressive recovery agents in India. Here is the unfiltered ground truth on how to survive NBFC defaults and force formal settlements.
Fintech apps will tell you “Settlement is strictly against company policy” because frontline bots cannot grant haircuts. Settlements only become possible past 180 DPD by bypassing the app and writing directly to the underlying RBI-registered NBFC's Principal Nodal Officer (PNO) or attending Lok Adalat. Bajaj Finance settles at 40%–60% waivers, but only after you withstand their intense field agent pressure.
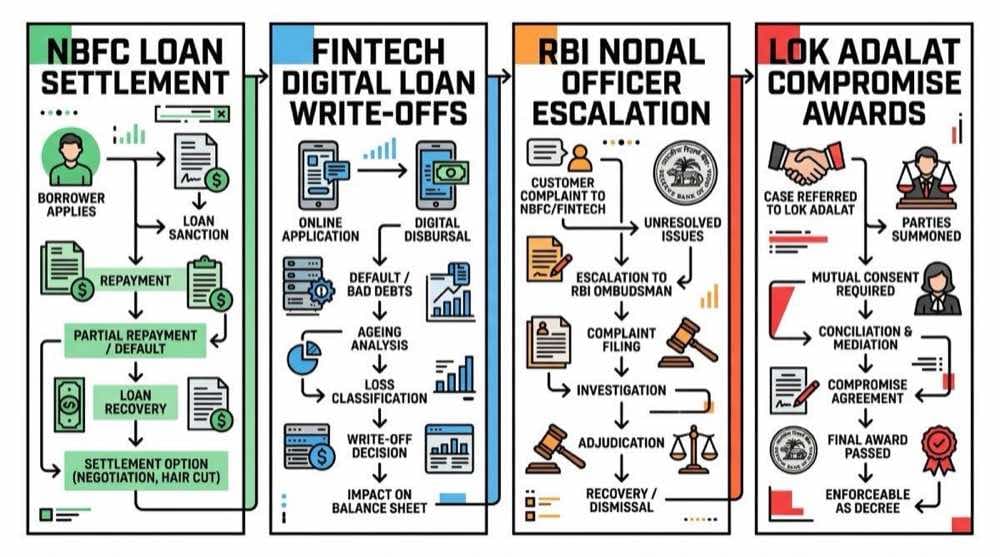
Figure 1.0: Complete flow from digital fintech default to RBI Principal Nodal Officer escalation and Lok Adalat compromise awards.
NBFC Loan Settlement Truth: Fintech vs Legacy
VC Debt & Zero Haircut Margins
Fintech lenders (Navi, KreditBee, Kissht, CASHe) borrow money at 12%–16% from wholesale debt funds and lend it at 24%–36% APR. Because their capital cost is high and margins are paper-thin, their algorithms are hardcoded to never grant voluntary settlement discounts on active accounts.
Institutional 90-Day Provisioning
Legacy giants like Bajaj Finance and Tata Capital operate institutional balance sheets. At 90 DPD, they classify loans as NPAs and set aside 100% cash provisions. At 180+ DPD, recovering 40% to 50% in cash cleans up their quarterly NPA ratios for stock market filings.
Court Fees Exceed Loan Amount
Most digital fintech personal loans are small tickets (₹25,000 to ₹1,50,000). Filing Section 25 PSS Act criminal complaints or summary civil suits in magistrate courts costs ₹20,000+ per borrower. Lenders bluff aggressively, but practical recovery happens only via out-of-court OTS or Lok Adalat.
Fintech App Brand vs Registered NBFC Entity Mapping
When you default on an app, you are NOT being sued by the app logo. Under RBI Digital Lending Guidelines, the app is merely a Loan Service Provider (LSP). Your debt is held by an RBI-registered NBFC:
Settles strictly via Central Grievance Desk / Lok Adalat at 180+ DPD. In-app bots will deny.
Directly registered NBFC. Customer care refuses OTS; Principal Nodal Officer handles hardship.
Uses Northern Arc and Si Creva. Outsourced recovery agencies are aggressive; settle via Zonal desks.
Settlement notices must be served to Bhanix Finance Nodal Cell for 30%–40% waivers past 180 DPD.
Multi-lender platform. Check your sanction letter PDF to confirm which partner funded your loan.
Direct NBFC entity. Hardship letters citing medical/job emergency unlock formal compromise.
Why Fintech Apps Refuse Settlements & How OTS Works
While Navi, Kissht, and Si Creva strictly refuse loan settlements across the board, other fintechs (like KreditBee, CASHe, and Fibe) initially reject in-app settlement requests with automated messages before offering 35%–50% OTS via their Principal Nodal Officers. Here is why bots resist frontline requests:
In-app customer care executives and chat bots operate on strict scripts with no discretionary power to waive even ₹100 of late fees. Asking them for an OTS is a waste of time.
Fintechs assign defaulted accounts to third-party collection agencies on a 20% to 35% commission cut. These recovery agents make money ONLY if they extract full payments, which is why they resort to 50+ robocalls/day, threatening WhatsApp notices, and contact list shaming.
Fintech NBFCs only settle when an account crosses 180+ DPD into the Technical Write-Off pool. At this stage, collection agencies give up, the debt is flagged for bad-debt disposal, and the NBFC's central legal cell accepts 25% to 40% compromise payouts to recover principal capital.
Bajaj Finance Recovery Reality vs 40%–60% OTS
In the Indian lending ecosystem, Bajaj Finance represents the classic paradox: their recovery tactics are flagship-grade aggressive, but their balance sheet desk grants substantial 40% to 60% settlement waivers once accounts hit NPA write-off status.
Bajaj recovery agents show up unannounced at homes, shops, and offices at 7:00 AM or late in the evening. They corner relatives or speak to neighbors under the guise of “address verification” to create intense social panic.
Bajaj Finance frequently re-presents ECS / e-NACH debits 3 to 5 times a month, racking up ₹500 bank bounce charges on the borrower's bank account.
Once a Bajaj loan crosses 180 DPD and enters National Lok Adalat or regional legal recovery desks, their central committee routinely approves 40% to 60% OTS waivers.
Interactive NBFC Loan Settlement Payout Calculator
Select your outstanding balance, your specific lending app or NBFC, and your delinquency stage to see realistic payout expectations:
NBFC Loan Settlement Calculator
Estimate realistic OTS payable figures based on whether your lender is a VC-backed fintech app or a legacy NBFC.
The Token Payment Trap: How Agents Scam Borrowers
The #1 scam targeting defaulted NBFC borrowers is the “Token Deposit Trap” run by commission-hungry collection agents:
An agent calls or visits saying: “Pay just ₹5,000 or ₹10,000 on this link today, and I will personally close your ₹1,50,000 loan from the backend system.”
NEVER pay a single rupee based on verbal promises, WhatsApp screenshots, or personal UPI QR codes. Payment must be made ONLY after you hold an authentic OTS Sanction Letter issued from the NBFC's official email domain.
NBFC Default Impact on CIBIL: Settled Tag vs Write-Off
Settling an NBFC loan causes an immediate 75 to 150 point drop in your CIBIL score. The account is reported as “SETTLED” or “POST WRITE-OFF SETTLED”, signaling to other banks that you did not pay the full loan balance.
No bank or registered NBFC will approve fresh unsecured personal loans or credit cards for 5 to 7 years following a settlement.
Top 10 NBFCs Ground-Level Harassment & Settlement Matrix
Empirical data on the Top 10 Indian NBFCs and fintech lenders based on ground collection aggression and NPA settlement reality:
Home visits, neighborhood inquiries, and repeated NACH bounce charges. Direct email escalation to Grievance cell unlocks 50%+ waivers.
Professional legal escalation. Settles amicably in National Lok Adalat hearings upon submission of verified medical/job loss proof.
Relentless initial telecalling cadence. Responding calmly to formal demand notices unlocks written OTS agreements.
Unsecured personal loan portfolio. Settles once categorized as long-term bad debt at branch level.
Navi is one of only three lenders (along with Kissht and Si Creva) that strictly does NOT offer loan settlement. Demands 100% recovery with zero OTS allocation.
Unlike Navi/Kissht, KreditBee/Krazybee Services NBFC offers 35%–50% compromise settlements upon escalation to PNO or Lok Adalat.
Kissht and Si Creva are among only three lenders (along with Navi) that strictly do NOT offer loan settlements. Demands 100% recovery with zero OTS budget.
Rejects early settlement. Direct Nodal Officer representations unlock up to 40% haircuts past 180 DPD.
Check sanction letter to identify whether Whizdm, DMI Finance, or Clix Capital holds the debt before settling.
Formal hardship documentation (salary slip reduction, medical bills) required for Principal Nodal Officer approval.
Case Study: ₹4.2 Lakh Bajaj & KreditBee Settled at 55%
The Situation: An IT professional in Delhi faced sudden unemployment, defaulting on a ₹2.8 Lakh Bajaj Finance personal loan and a ₹1.4 Lakh KreditBee loan. Within 45 days, he was hit with 80+ calls/day and two unannounced home visits by Bajaj recovery agents.
The Strategy:(1) Canceled all active e-NACH mandates to prevent bank penalties. (2) Bypassed the KreditBee app chatbot and submitted a formal hardship notice to the Principal Nodal Officer of Krazybee Services. (3) Refused to entertain Bajaj field agents at home, insisting on meeting only at the zonal branch office. (4) At 210 DPD, both files were placed before the National Lok Adalat bench.
Resolution: Bajaj settled for ₹1,30,000 (53.5% haircut, Ref: BAJAJ/SAM/2026/OTS-41892). KreditBee settled for ₹59,000 (57.8% haircut, Ref: KB/PNO/2026/SET-1104). Full No Dues Certificates received in 30 days.
Section 25 PSS Act vs Fake WhatsApp Legal Notices
Fintech collection agencies flood defaulted borrowers with terrifying messages on WhatsApp citing Section 25 PSS Act, Section 138 NI Act, and Section 420 IPC. Here is the ground reality:
99% of notices sent on WhatsApp with forged court seals, fake advocate stamps, or Delhi Police Cyber Cell logos are fabricated by collection agents. Real court notices are NEVER served via WhatsApp by private agents giving 2-hour deadlines.
An e-NACH bounce allows the NBFC to file a Section 25 complaint in a magistrate court. However, this is a bailable compoundable summons trial. The magistrate issues summons via Registered Post with 30–60 day dates. If you appear, it is routinely referred to Lok Adalat to settle amicably at 40%–60% discounts.
Ground-Level Defense Against Home Visits & Shaming
You are under no legal obligation to let agents inside your home. Ask for their official Employee ID card, NBFC Authorization Letter, and demand all correspondence strictly on email.
If an app calls your relatives or emergency references, post a pre-emptive WhatsApp status: “My phone contact list was compromised by a rogue app. Please ignore any spam calls.” Contacting third parties violates RBI Digital Lending Guidelines.
Record abusive calls and lodge complaints on sachet.rbi.org.in and cybercrime.gov.in. NBFCs are vicariously liable for agent harassment.
How to Bypass App Bots: Escalating to Nodal Officer
To unlock a genuine OTS with a digital fintech lender, you must execute the PNO Bypass Protocol:
Close the app support chat. Do not argue with frontline telecallers or bots.
Open your loan sanction email or PDF to verify the exact legal entity (e.g. Krazybee Services, Bhanix Finance, Navi Finserv).
Use our free tool below to generate a formal representation citing RBI Digital Lending Guidelines and hardship proof.
If the PNO does not resolve the matter within 30 days, file an official complaint on the RBI CMS portal (cms.rbi.org.in).
Lok Adalat & ODR: Locking in a Binding Compromise
If an NBFC refuses informal settlement, National Lok Adalat or Online Dispute Resolution (ODR) is the most powerful legal mechanism available to borrowers:
A Lok Adalat award has the legal status of a final civil court decree. Once signed, the NBFC can NEVER claim residual dues or assign the debt to recovery agencies.
Judicial conciliators at Lok Adalat actively push NBFC legal officers to waive 100% of penal charges, bounce fees, and up to 50% of the principal balance for insolvent borrowers.
There are zero court fees or advocate mandates. Both parties sign a compromise agreement directly before the bench.
Genuine NBFC Settlement Letter Verification Checklist
- ✓1. Registered NBFC Letterhead: Must be issued by the registered NBFC entity (e.g.
Krazybee Services Pvt Ltd), NOT just an app graphic. - ✓2. Unique Internal Settlement ID: Must contain an authorized tracking reference number (e.g.
KB/SAM/2026/OTS-99420). - ✓3. Direct Loan Account Payment: Payment must be routed strictly to your own unique loan virtual account, NEVER to an agent's personal UPI.
- ✓4. Official Corporate Domain Email: Sent from the official domain (e.g.
@krazybee.com,@bajajfinserv.in), never from Gmail or Yahoo.
NBFC Principal Nodal Officer Hardship Letter Generator Tool
Generate a formal legal notice addressed directly to the Principal Nodal Officer of the registered NBFC to request an amicable OTS and legally halt collection harassment:
NBFC Principal Nodal Officer Hardship Notice Generator
Bypass in-app support bots and generate an official legal representation addressed to the Principal Nodal Officer of the underlying registered NBFC.