HomeAbout
BlogSoon
Bank specific setupSoon
LocationsSoon
WARNING: THIS IS NOT LEGAL ADVICE. THIS IS SURVIVAL ADVICE BASED ON REAL BORROWER EXPERIENCE.
UPDATED: SEPTEMBER 2026

IndusInd Bank Loan Settlement Process & CFD Rules in India

How to Settle IndusInd Personal, Card & Vehicle Debt

If you are struggling with unpaid IndusInd Bank personal loans, credit cards, or vehicle financing, you have legal rights. This guide explains how to leverage private commercial provisioning cycles, stop recovery harassment, prevent unlawful vehicle seizure, and negotiate an official compromise settlement for 40% to 65% less.

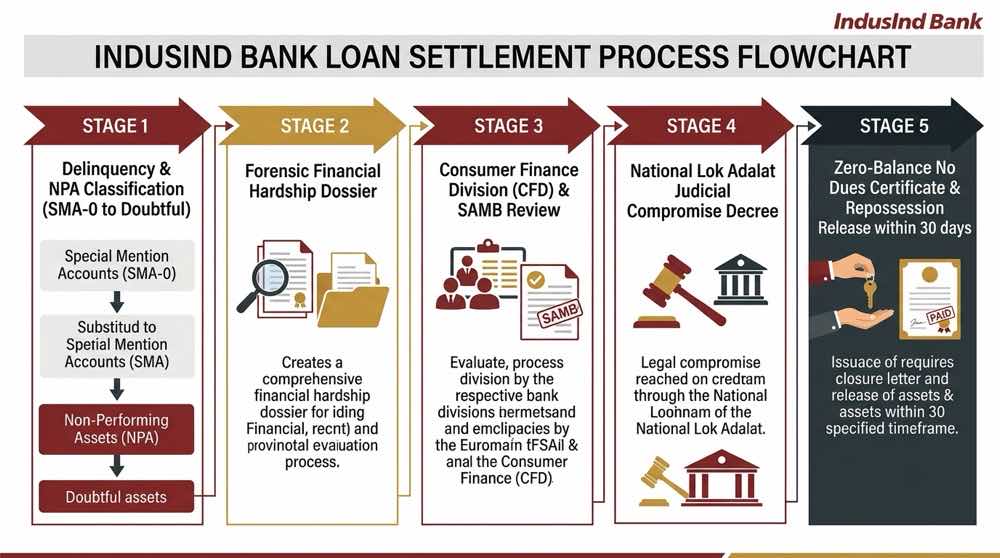
IndusInd Bank Loan Settlement Process, CFD Escalation and Compromise Workflow

Figure 1: Official settlement hierarchy and CFD compromise procedure across IndusInd Bank branches and Consumer Finance desks.

Quick Answer Summary

IndusInd Bank loan settlements work through retail branches for personal loans and cards, and through its Consumer Finance Division (CFD) for vehicle debt. Because IndusInd is a private bank, recovery managers have strong commercial power to approve 40% to 65% principal discounts on credit cards and personal loans overdue past 6 months. For car and truck loans, you can settle before the vehicle is auctioned. Always pay directly into your IndusInd loan account and collect an unconditional No Dues Certificate within 30 days under RBI rules.

⚡ Empirical CalculatorUNSECURED NPA

IndusInd Bank Settlement & Haircut Estimator

Calculate realistic One-Time Settlement (OTS) compromise ranges based on IndusInd Bank CFD and Stressed Asset guidelines.

Unsecured retail advance. Delinquent accounts past 180 DPD qualify for 100% penal interest waiver and up to 60% principal reduction.

₹4,00,000
₹30,000₹25,00,000₹50,00,000
Target Settlement Offer:50%–65% Haircut
Realistic Settlement Range:₹1,40,000₹2,00,000
Estimated Debt Forgiven:₹2,00,000₹2,60,000
*100% penal interest and late payment charges waived under IndusInd OTS guidelines.
⚠️
IndusInd Bank Recovery Caveat:IndusInd assigns third-party agencies aggressively. Escalate directly to the Principal Nodal Officer (PNO) or Stressed Asset Desk for genuine compromise sanction.

1. IndusInd Institutional Reality: Commercial Agility & CFD Power

IndusInd Bank is a leading private bank known for personal loans and vehicle financing. When you fall behind on payments, dealing with IndusInd is very different from public sector banks like SBI or Canara Bank.

Public banks follow strict government vigilance audits. But IndusInd Bank operates as a private business. Their recovery managers have the power to approve big discounts on bad loans if they realize court cases will take years and cost too much.

The Best Time to Settle

IndusInd Bank works on strict quarterly financial deadlines (June, September, December, and especially March). When loans are overdue past 6 months, the bank must set aside money for bad debts. Approaching recovery managers near the end of these quarters gets you the biggest settlement discounts.

2. Consumer Finance Division (CFD) Recovery Architecture

To settle with IndusInd Bank, you need to know which department handles your loan:

Consumer Banking Division

Handles personal loans, credit cards, and home loans through normal bank branches. Settlements here follow standard retail recovery rules.

Consumer Finance Division (CFD)

Manages vehicle loans, cars, commercial trucks, tractors, and construction equipment. CFD operates through dedicated regional recovery hubs with its own recovery staff.

If your unpaid loan is for a car, truck, or machine, local branch staff cannot help you. You must send your settlement request directly to the Regional Collection Manager (RCM) of the Consumer Finance Division.

3. IndusInd Settlement Formula: How Waivers Are Calculated

IndusInd Bank decides your discount based on how long your loan has been unpaid and whether they hold any asset security:

Loan StatusTime OverdueSettlement RuleTarget Discount
Early Default (SMA-2)60 to 90 daysOverdue EMI ClearancePenalty Waiver Only
NPA (Sub-Standard)90 to 180 daysPrincipal + Waived Late Fees20% to 35% Off
Doubtful (D1/D2)180 to 365+ daysDeep Principal Discount40% to 55% Off
Loss / Written-OffOver 2 yearsMaximum Cash Settlement55% to 70% Off

Unsecured vs Secured Loans: Unsecured loans (personal loans and credit cards) get the largest discounts (up to 65%) because the bank has no asset to sell. Vehicle loans get 25% to 45% discounts depending on the market value of your vehicle.

4. National Lok Adalat: Judicial Compromise Decrees

National Lok Adalat is one of the safest ways to settle with IndusInd Bank. These court drives happen every three months in all district courts across India.

Final Court Protection

Under Section 21 of the Legal Services Authorities Act, 1987, an agreement in Lok Adalat has the force of a civil court decree. Once you pay the agreed sum, IndusInd Bank cannot file any more cases, reopen your debt, or sell your file to recovery agencies.

If IndusInd Bank sends you a Lok Adalat notice, do not ignore it. Go in person with your medical bills, salary slip, or income proof, and offer a clear one-time payment.

5. Personal Loans & Digital Credit: Section 171 Banker's Lien

IndusInd Bank gives out instant digital loans (Indus Easy Credit) and personal loans. When you miss payments, the bank acts fast inside its computer systems.

Automated Section 171 Banker's Lien

Under Section 171 of the Indian Contract Act, 1872 (called the Banker's Right of Set-Off), IndusInd Bank can freeze your savings account. If your personal loan or card is unpaid, the bank can put an internal freeze on any savings account, current account, or fixed deposit under your Customer ID.

Protect your family's living money with three simple steps:

  • Open a fresh savings account in another bank before your loan is 60 days overdue.
  • Tell your company to deposit your monthly salary into your new bank account.
  • Never keep emergency money in an IndusInd account while negotiating your debt.

6. IndusInd Credit Cards: Tackling 46% Compounded APR

IndusInd credit cards (like Pinnacle, Legend, Platinum, and Nexxt) charge interest up to 3.83% per month. That adds up to nearly 46% per year once you add late fees and 18% GST. An unpaid card bill can triple in less than two years.

How to Negotiate Your IndusInd Card Bill

When talking to IndusInd card recovery teams, never accept the total inflated bill. Ask for your complete itemized statement. Strip away all interest, late fees, and overlimit charges to find your pure principal spend. IndusInd settlement officers can waive 100% of these extra charges. This lets you settle the money you actually spent for 35% to 50% less.

7. CFD Vehicle Loans: Illegal Repossession vs Compromise

IndusInd Bank's Consumer Finance Division (CFD) is a market leader in vehicle loans. When borrowers miss payments on cars or commercial trucks, recovery agents sometimes try to snatch vehicles illegally. You must know your legal rights:

Supreme Court Rules on Vehicle Seizure

  • Ban on Musclemen: In ICICI Bank vs Prakash Kaur, the Supreme Court ruled that banks cannot use recovery thugs or force to seize vehicles on the road.
  • 14-Day Notice: After taking a vehicle, IndusInd must give you a written 14-day pre-sale notice with the exact amount needed to get your vehicle back.
  • Inventory List: The recovery team must make a signed list of all personal items left inside the vehicle when it is handed over.

If IndusInd seizes your vehicle by force without following these rules, file a police complaint immediately and report it to the Principal Nodal Officer. This serious violation gives you strong leverage to settle for a lower amount.

7. Bharat Financial Inclusion (BFIL) Microfinance & Unsecured Commercial Advances

Through its wholly owned subsidiary, Bharat Financial Inclusion Limited (BFIL), IndusInd Bank extends Joint Liability Group (JLG) micro-advances, alongside unsecured merchant POS loans and small-enterprise credit lines.

RBI Microfinance Framework & Commercial Compromise Solutions

Under the RBI Master Direction on Microfinance Loans (2022), recovery personnel are strictly forbidden from applying collective social pressure, visiting borrowers during non-business hours, or refusing medical hardship pleas. For distressed enterprises or closed merchant units, BFIL and regional credit committees routinely sanction One-Time Settlements discounting unsecured principal balances by 40% to 60%.

8. CFD Sanction Verification, Core Account Remittance & 30-Day Form 35/NDC SLA

Because IndusInd Bank operates specialized auto and retail loan desks, never pay funds based on third-party collection agency receipts. Every authentic compromise must be ratified through a formal OTS Sanction Letter bearing authorized CFD or retail committee approval.

● Direct Core Account Remittance: Remit all settlement installments directly into your designated IndusInd Bank loan account via NEFT/RTGS using branch IFSC code INDB0..., or tender a crossed Account Payee Demand Draft favoring "IndusInd Bank A/C [Your Loan Number]". Never pay cash to recovery personnel.

● 30-Day Form 35 & NDC Mandate: In strict compliance with RBI circular RBI/2023-24/60, IndusInd Bank is legally obligated to issue your No Dues Certificate and provide Form 35 (RTO Hypothecation Removal) or return deposited collateral within 30 calendar days of final settlement clearance. Unjustified delay obligates the lender to pay statutory compensation of ₹5,000 per day of delay.

● Bureau Updating Protocol: Confirm at 45 days post-settlement that credit bureaus reflect a zero outstanding balance with account status marked "Settled". Rebuild your CIBIL score back above 750 over 18 to 24 months with a disciplined secured credit card repayment history.

Tier 1Branch Manager & Consumer Care Helpdesk
SLA: 7 Working Days

Authority: Frontline Customer Service / CFD Helpdesk

Contact: Toll-free: 1860 267 7777 / 1800 209 0061 | Email: reachus@indusind.com

Jurisdiction: Handles factual ledger balance disputes, initial compromise requests, and statement queries.

Tier 2Nodal Officer (Internal Escalation)
SLA: 10 Working Days

Authority: Senior Grievance Head

Contact: Phone: (022) 6877 9659 | Email: nodal.officer@indusind.com

Jurisdiction: Reviews stalled OTS proposals, vehicle repossession disputes, and unresolved branch grievances.

Tier 3Principal Nodal Officer (PNO)
SLA: 15 Working Days

Authority: Ms. D. Sidhwa (Executive Vice President & PNO)

Contact: OPUS Center, 47, Central Road, Opp. Tunga Paradise Hotel, MIDC, Andheri (East), Mumbai - 400093 | Phone: (022) 6155 3705 | Email: pno@indusind.com

Jurisdiction: Senior-most internal authority for third-party harassment, illegal repossession, and final compromise review.

Tier 4RBI Banking Ombudsman (Statutory Regulator)
SLA: 30 Days Post-PNO

Authority: Reserve Bank of India Consumer Education and Protection Cell

Contact: Portal: cms.rbi.org.in | Toll-Free: 14448 | Postal: CRPC, RBI, 4th Floor, Sector 17, Chandigarh - 160017

Jurisdiction: Binding statutory adjudication under the Reserve Bank - Integrated Ombudsman Scheme, 2021.

📝

1-Click IndusInd PNO Harassment & OTS Template

Personalize the bracketed variables and email directly to pno@indusind.com.

Subject: URGENT: Harassment, Unlawful Collection & Formal OTS Submission - Loan A/C [Your Account Number]

To:
The Principal Nodal Officer,
IndusInd Bank Ltd, OPUS Center, Andheri (East),
Email: pno@indusind.com

Cc:
Nodal Officer: nodal.officer@indusind.com

Dear Madam,

I am writing regarding my Loan/Credit Card Account Number [Your Account Number] registered with IndusInd Bank [Branch/CFD Location].

Due to severe unforeseen financial hardship caused by [State Reason: e.g., Critical Medical Emergency / Sudden Loss of Employment / Enterprise Revenue Collapse], I am unable to maintain contractual EMI schedules. I have communicated my willingness to execute a legitimate One-Time Settlement (OTS) compromise reflecting my realistic payment capacity.

However, recovery agents claiming to represent IndusInd Bank / Consumer Finance Division have violated RBI regulations:
1. Threatening forcible asset seizure without serving statutory pre-repossession notices.
2. Placing abusive and coercive telephone calls outside the permitted 8:00 AM to 7:00 PM corridor.
3. Intimidating family members and employers in direct violation of the RBI Fair Practices Code.

Please note that these actions violate Supreme Court directives on loan recovery and constitute an offense under Section 351 of the Bharatiya Nyaya Sanhita (BNS) for criminal intimidation.

I hereby formally demand:
1. Immediate halt to all unauthorized recovery calls and workplace visits.
2. Written consideration of my compromise settlement proposal under IndusInd settlement guidelines.
3. All future communications sent exclusively to my registered email address.

Yours faithfully,
[Your Name]
[Contact Number]
[City]

9. Frequently Asked Questions (IndusInd Bank Loan Settlement)

How does loan settlement work with IndusInd Bank's Consumer Finance Division (CFD)?
IndusInd manages car, bike, and commercial vehicle loans through its Consumer Finance Division (CFD). When a loan is unpaid for over 90 to 180 days, regional CFD desks can approve settlements, waiving 100% of penalty fees and cutting 30% to 50% off the principal balance.
Can IndusInd Bank repossess my vehicle without a court order?
No. Under Supreme Court rulings (including ICICI Bank vs Prakash Kaur) and RBI rules, banks cannot use recovery thugs or force to take your vehicle. IndusInd must give you a 14-day pre-sale notice and make a list of your personal items before any auction.
Can IndusInd Bank freeze my savings account under Section 171?
Yes. Under Section 171 of the Indian Contract Act (Banker's Right of Set-Off), IndusInd can freeze any account linked to your Customer ID. Move your salary and living money to an unlinked bank before you default.
What waiver can I expect on an unsecured IndusInd personal loan or credit card?
For personal loans or cards unpaid for over 6 months, IndusInd routinely approves settlements for 40% to 65% less. They will also wipe out all extra interest, late fees, and GST charges.
How does Bharat Financial Inclusion Limited (BFIL) debt affect my settlement?
BFIL is IndusInd's microfinance branch. Microfinance loans follow special RBI rules. Field agents cannot harass you. If you face genuine poverty, illness, or loss, you can settle your individual loan directly with the zonal BFIL manager.
How does settling at National Lok Adalat benefit IndusInd Bank borrowers?
Lok Adalat orders have the power of a civil court decree under Section 21 of the Legal Services Authorities Act. It closes all cheque bounce or auto-debit cases immediately and prevents the bank from ever taking you to court again.
What interest rates apply when IndusInd credit cards default?
IndusInd credit cards charge up to 3.83% per month (almost 46% per year) with fees. When you negotiate, ask for your full statement. Demand 100% waiver on all interest and fees, and settle the pure principal spend.
What should I do if third-party recovery agents harass my family?
Record all calls and visits. File a police complaint under Section 351 of Bharatiya Nyaya Sanhita (BNS) for criminal intimidation. Report the agents immediately to IndusInd's Principal Nodal Officer (pno@indusind.com) and the RBI Ombudsman.
How many days does IndusInd Bank have to issue a No Dues Certificate?
Under RBI rules (RBI/2023-24/60), IndusInd must issue your No Dues Certificate and return all vehicle papers (Form 35) within 30 days of full payment. If they delay, they must pay you ₹5,000 for every day of delay.
How does an IndusInd settlement impact my CIBIL score?
The bank marks your loan as 'Settled' instead of 'Closed'. Your score may drop by 50 to 100 points temporarily. You can rebuild your score back above 750 within 18 to 24 months by using a secured fixed deposit credit card responsibly.

Find this content helpful?

If this guide has helped you navigate your settlement journey, consider showing some support to keep this platform running.