HomeAbout
BlogSoon
Bank specific setupSoon
LocationsSoon
WARNING: THIS IS NOT LEGAL ADVICE. THIS IS SURVIVAL ADVICE BASED ON REAL BORROWER EXPERIENCE.
UPDATED: SEPTEMBER 2026

HDFC Bank Loan Settlement Process & OTS Rules in India

How to Settle HDFC Personal, Credit Card & Home Loans

If you are struggling with unpaid HDFC loans or credit cards, you are not alone-and you have legal rights. This practical guide shows you how to handle recovery calls, avoid bank account freezes, and negotiate an official One-Time Settlement (OTS) directly with HDFC Bank to close your debt for 50% to 75% less.

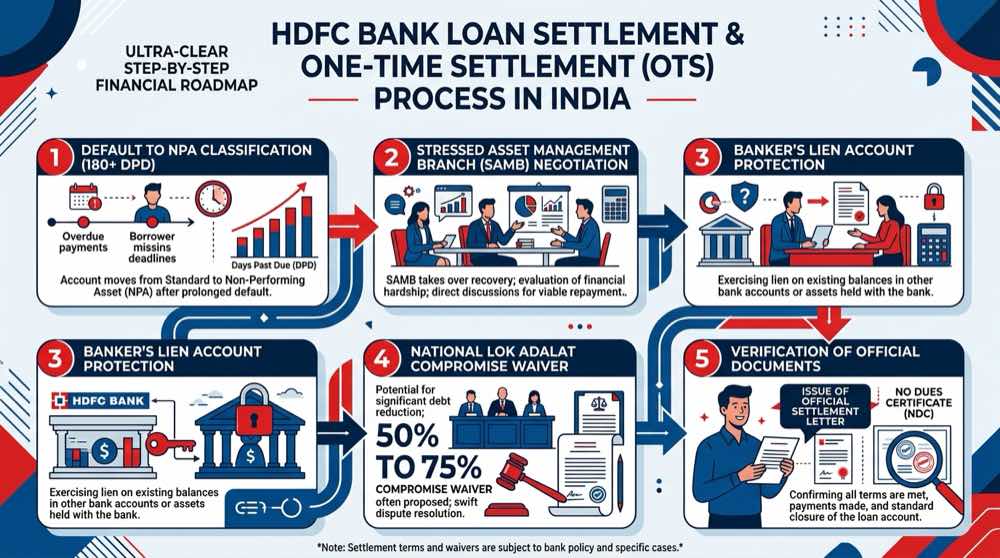
HDFC Bank loan settlement process, OTS waiver timeline, and legal defense roadmap

Visual Roadmap: The 5 steps to settling HDFC debt: wait for 6 months delinquency, protect your salary account, negotiate with the special recovery branch, settle for 50%–75% less, and get your official No Dues Certificate.

Quick Answer Summary

Yes, you can settle an HDFC personal loan or credit card for a 50% to 75% discount once payments are delayed past 6 months (180 days). At this point, the bank treats the debt as a loss and will waive accumulated interest and penalties to recover cash. However, home loans cannot be discounted because the bank holds your property papers. Most importantly: move your salary to a different bank to stop HDFC from auto-debiting your savings (Section 171 Banker's Lien), and never pay cash to recovery agents.

⚡ Empirical CalculatorUNSECURED NPA

HDFC Bank Settlement & Haircut Estimator

Calculate realistic One-Time Settlement (OTS) compromise ranges based on actual HDFC Stressed Asset recovery metrics.

Unsecured retail debt. HDFC Retail Assets collection transfers accounts past 90 DPD to Stressed Asset Management branches.

₹3,50,000
₹25,000₹25,00,000₹50,00,000
Target Settlement Offer:50%–65% Haircut
Realistic Settlement Range:₹1,22,500₹1,75,000
Estimated Debt Forgiven:₹1,75,000₹2,27,500
*Penal Waiver: 70%–100% of accumulated penal fees & bounce charges waived.
HDFC Set-Off & Banker's Lien Directive:Move your salary account out of HDFC immediately before starting negotiations to prevent auto-debit Banker's Lien freezes.
⚡ Regulatory Shield4-STAGE LADDER

HDFC Bank Grievance Redressal & PNO Directory

If recovery agents violate RBI calling guidelines or threaten criminal prosecution, escalate through HDFC's apex compliance desk.

Level 1: Branch Manager & Retail AssetsTurnaround: 7 Days

Submit a written hardship application in person at your home branch. Request account transfer to the Retail Asset Collections (RAC) desk.

Level 2: Grievance Redressal Officer (GRO)Turnaround: 7 Days

Escalate via HDFC's digital grievance redressal portal (grievance.hdfcbank.com) citing your previous complaint ticket.

Level 3: Principal Nodal Officer (PNO)APEX DESK

Official Emails: pno@hdfcbank.com | nodal.officer@hdfcbank.com

Direct escalation creates a statutory audit record that legally compels HDFC to halt unauthorized agency harassment.

Level 4: RBI Integrated Ombudsman (cms.rbi.org.in)Statutory

If unresolved after 30 days of PNO filing, lodge a formal digital complaint under the RBI Integrated Ombudsman Scheme (RB-IOS).

Pre-Drafted PNO Escalation Notice:
Formal Grievance: Cease Harassment by Recovery Agents & Request for One-Time Settlement (OTS) To: The Principal Nodal Officer, HDFC Bank Ltd., Email: pno@hdfcbank.com / nodal.officer@hdfcbank.com Subject: Formal Grievance regarding Harassment by Recovery Agents & Request for Compromise One-Time Settlement (OTS) - Loan/Card A/c: [YOUR LOAN/CARD ACCOUNT NUMBER] Respected Principal Nodal Officer, I am writing to register an urgent formal grievance under the RBI Master Direction on Fair Practices Code for Lenders (RBI/2022-23/84) and the Reserve Bank - Integrated Ombudsman Scheme, 2021. 1. Background: I hold an active facility with HDFC Bank under Account No. [YOUR LOAN/CARD ACCOUNT NUMBER]. Due to genuine, verifiable financial hardship ([BRIEFLY MENTION: LOSS OF EMPLOYMENT / SEVERE MEDICAL EMERGENCY / BUSINESS LOSS]), I have experienced delays in regular EMI servicing. 2. Regulatory Violations by Collection Agencies: I am being subjected to unlawful harassment by external recovery agents representing HDFC Bank. Specifically: - Repeated harassing phone calls outside prescribed RBI hours (before 8:00 AM and after 7:00 PM). - Unsolicited calls, threats of criminal prosecution, and intimidation to family members and colleagues. - Threats of immediate arrest under criminal sections (which violates statutory lending guidelines and amounts to Criminal Intimidation under Section 351 of Bharatiya Nyaya Sanhita, 2024). 3. Request for Remedy & Settlement: - I hereby demand an immediate cessation of all unnotified third-party recovery agency visits and telephone harassment. - I request HDFC Bank to recall this account from external collection agencies and transfer it to the Stressed Asset Management Branch (SAMB) for structured compromise discussions. - I am prepared to offer a genuine lump-sum One-Time Settlement (OTS) of ₹[YOUR REALISTIC SETTLEMENT BUDGET] as full and final closure against an official settlement letter issued on HDFC Bank letterhead. Please acknowledge receipt of this complaint within 48 hours and provide an official Grievance Ticket Number. Failing resolution within 30 days, I shall escalate this matter to the RBI Integrated Ombudsman (cms.rbi.org.in). Sincerely, [YOUR FULL NAME] [REGISTERED MOBILE NUMBER] [REGISTERED EMAIL ADDRESS] [LOAN / CREDIT CARD NUMBER]

*Replace all [BRACKETED FIELDS] with your actual loan details before emailing.

1. The HDFC Settlement Reality: When & Why the Bank Agrees

HDFC Bank's recovery and settlement process follows a strict timeline based on how many days your payment has been delayed:

● Month 1 (1–30 Days Late): You receive automated text messages, NetBanking notifications, and gentle reminder calls from customer care. The bank will not discuss any discount or settlement at this stage.

● Months 2–3 (31–89 Days Late): Your file is given to third-party telecalling collection agencies. You will start receiving multiple aggressive phone calls every day and demand letters at home. Do not panic-this is standard pressure, not a police case or arrest warrant.

● Month 3 (90 Days Late - NPA Tag): Under Reserve Bank of India (RBI) rules, your account is now officially tagged as a “Non-Performing Asset” (NPA). The bank is forced to set aside its own profit money into a reserve fund to cover this bad loan.

● Month 6 onwards (180+ Days Late - Settlement Window): Because keeping this unpaid debt on their books hurts their quarterly profits, your file is transferred to HDFC's Stressed Asset Management Branch (SAMB). At this stage, HDFC would rather recover 30% to 50% of the money in cash today than spend more money on collection agencies. This is when 50% to 75% waivers are actually approved.

2. The Critical Trap: HDFC's Right of Banker's Lien (Set-Off)

🚨 Mandatory Warning Before You Default on HDFC:

If you have a savings account, corporate salary account, or fixed deposit with HDFC Bank, the bank will secretly freeze your money and deduct it to pay off your overdue credit card or loan.

Under Indian law (Section 171 of the Indian Contract Act, known as the Banker's Right of Set-Off), HDFC does not need a court order or your permission to take money from your savings account to pay your loan. Many borrowers wake up on salary day to find their entire month's salary wiped out to ₹0.

Your #1 Survival Step: At least 60 days before you miss an EMI or start settlement talks, immediately ask your employer's HR to change your salary account to a completely different bank (such as State Bank of India, Punjab National Bank, or Bank of Baroda). Never keep your family's grocery and rent money inside an HDFC account if you owe them money.

3. HDFC Personal Loan & Jumbo Loan Settlement Playbook

HDFC personal loans, pre-approved digital loans, and Jumbo Loans are unsecured (no house, car, or gold pledged). Because there is no collateral, the bank cannot seize your property or auction your home.

To negotiate a high-waiver settlement on an HDFC personal loan, follow these 3 simple rules:

RULE 1: PROVE GENUINE FINANCIAL HARDSHIPBanks do not settle just because you ask. You must show written proof that you cannot pay-such as hospital discharge papers, a company job termination letter, or bank statements showing business losses.
RULE 2: REJECT THE FIRST TWO OFFERSThe bank's first offer will only waive 10% to 20% of late fees. Do not accept this. Stand firm, explain that you have no income, and state that you can only pay a single lump-sum borrowed from relatives to close the matter forever.
RULE 3: TIME YOUR OFFER FOR QUARTER-ENDSHDFC collection managers have strict quarterly targets. During the last 10 days of March (financial year-end), June, September, and December, managers have special powers to approve much deeper discounts (50% to 70%) to hit their targets.

4. HDFC Credit Card Settlement & 42% APR Penalty Defense

HDFC credit cards (such as Millennia, Regalia, MoneyBack, and Diners Club) charge interest rates of 3.6% to 3.75% per month. Because interest is added on top of interest every 30 days, this adds up to a massive 42% to 45% annual interest rate (APR).

If your actual card shopping spend was ₹1,50,000, after 6 months of missed payments your bill will jump to almost ₹2,80,000. That extra ₹1,30,000 is not money you spent-it is compounding finance charges, ₹1,200 monthly late fees, and 18% GST added to every penalty.

How to Settle Credit Cards on Pure Principal Only:

1. Ask HDFC for an itemized statement showing your exact original shopping spend (the pure principal) without any interest or penalties.

2. Tell the bank in writing that you will not pay their 42% interest or late fees, and insist that 100% of these penal charges must be removed under the settlement.

3. Offer to pay 40% to 50% of the original shopping principal as a one-time full and final payment. If your default is older than 1 year (360+ days), cards routinely settle for 25% to 35% of the inflated bill amount.

5. HDFC Home Loans & SARFAESI Defense

All HDFC housing loans are secured debts governed by the SARFAESI Act, 2002.

Can you get a 50% discount on an HDFC home loan? No. If any third-party agent promises a 50% waiver on an HDFC home loan, they are running a scam. Because when you took the home loan, the bank took your original property papers (Sale Deed / Registry). If you stop paying, the bank has the legal right to auction the property to get its money back.

The 3 Real Solutions for an Overdue Home Loan:

1. Wipe Out 100% of Penal Interest: The bank adds lakhs of rupees in late fees and penalty interest over 1–2 years. You can legally negotiate to cancel 100% of these penal fines if you agree to regularize your base EMIs.

2. Reply to the 60-Day Notice (Section 13(2)): When the bank sends you a formal 60-day demand notice, do not hide. Send an official objection letter within 60 days under Section 13(3A) explaining your medical or financial crisis. By law, the bank is forced to review your objection and reply within 15 days.

3. Sell the Property Yourself (Section 13(8) Private Sale): If you truly cannot afford the house, ask HDFC for a 90-day window to sell the house yourself in the open market. When the bank puts a house in a public auction, they sell it at a distress price (20% to 30% below market value), destroying your life savings. Selling it yourself lets you pay off HDFC and keep the remaining cash equity.

6. HDFC Gold Loan Default & Section 176 Auction Protocol

If you pledged family gold with HDFC Bank and stopped paying interest, the bank cannot secretly melt or sell your ornaments behind closed doors. Under Section 176 of the Indian Contract Act, 1872, you have 3 critical legal protections:

Mandatory 14-Day Written Notice: HDFC is legally prohibited from auctioning your gold without sending you an individual registered notice giving you 14 full days to clear the dues.

Fair Market Price Floor: The auction price must match at least 90% of the official 30-day average market gold price set by the India Bullion and Jewellers Association (IBJA). They cannot sell your gold at cheap throwaway prices.

Extra Money Must Be Returned to You: If your gold sells at auction for ₹4,00,000 and your total loan plus auction costs was ₹3,00,000, HDFC is legally required to send that extra ₹1,00,000 back to your bank account within 30 days.

7. Legal Notices Sent by HDFC: Section 138, Sec 25 & BNS Counter-Shields

When an HDFC loan defaults, collection agencies send scary-looking legal notices drafted by lawyers to create panic. Understanding what these notices actually mean removes the fear:

SECTION 138 NEGOTIABLE INSTRUMENTS ACT (CHEQUE BOUNCE)This applies only if a physical paper cheque you signed bounced. You receive a 15-day notice to clear the money. Having a lawyer send an official reply proposing a settlement almost always moves the matter to Lok Adalat without jail time.
SECTION 25 PAYMENT AND SETTLEMENT SYSTEMS ACT (eNACH BOUNCE)This is triggered when your electronic auto-debit bounces because your account had insufficient balance. It is purely a civil dispute and is routinely resolved through a compromise settlement.
SECTION 351 BHARATIYA NYAYA SANHITA, 2024 (YOUR SHIELD AGAINST RECOVERY GOONS)This is your legal shield. Under India's new penal code (Section 351 BNS, formerly 506 IPC), if collection agents shout at you, call your relatives, visit your workplace, or call before 8 AM or after 7 PM, they are committing a crime. You can file an immediate police complaint for criminal intimidation against both the agency and the bank.

8. National Lok Adalat: The Safest Channel for HDFC Waivers

The single safest and cleanest avenue to settle an HDFC loan is the National Lok Adalat. Held every 3 months across India by the government (National Legal Services Authority - NALSA), these are official settlement courts designed to help citizens resolve disputes peacefully.

Why settling at a Lok Adalat is 100x better than dealing with telecallers:

Permanent Closure (No One Can Ever Harass You Again): The settlement signed at Lok Adalat has the power of a final civil court decree. HDFC Bank or any recovery agency is legally barred from ever reopening your file or demanding more money.

Direct 50% to 70% Discounts on the Spot: HDFC bank managers attending Lok Adalat carry special pre-approved authority to sanction 50% to 70% waivers right on the spot without waiting for head office approval.

100% Free: There are zero court fees, zero lawyer charges, and zero hidden costs.

9. Operational Settlement Logistics: Retail Branch vs SAMB & How to Pay

The biggest mistake distressed borrowers make is walking into their local neighbourhood HDFC branch to ask for a discount. Here is how the bank's internal chain of command works and how to pay without getting cheated:

1. Why Your Local Branch Says NO (₹0 Waiver Power)

Retail branch managers, loan officers, and tellers have zero authority to reduce your debt by even ₹1. If you visit a branch, they will strictly demand 100% payment or tell you to borrow money from friends. Do not waste your time or emotional energy arguing at retail branch counters.

2. Who Actually Has the Power to Settle

At HDFC Bank, debt discounts are approved strictly by senior officers in the Stressed Asset Management Branch (SAMB), the Regional Collections Head, or bank officials at National Lok Adalat. To reach them directly, bypass third-party telecallers and email the Principal Nodal Officer (pno@hdfcbank.com).

3. The Zero-Scam Payment Rules

Once you have an official signed settlement letter from HDFC, pay strictly through authorized banking channels:

  • Direct NEFT / RTGS: Transfer money directly to: HDFC Bank Ltd - A/C [Your Exact Loan Number] from your external (non-HDFC) bank account.
  • Branch Counter Deposit: Pay directly at any HDFC bank teller counter using a physical pay-in slip with your exact loan number, and keep the stamped teller receipt safely.
  • STRICT WARNING: NEVER pay physical cash to any collection agent, never send money to any agency company account, and never pay via personal UPI (such as Google Pay or PhonePe).
Getting Your No Dues Certificate: Once your settlement money clears, HDFC Central Operations is required under RBI rules to send your official No Dues Certificate (NDC) or Settlement Closure Letter to your email and home address within 21 to 30 working days.

10. HDFC NetBanking & Mobile App “Digital OTS” Offers: How to Inspect & Negotiate

Between 3 and 6 months of missed payments, HDFC's computer system often shows pre-approved settlement offers inside your HDFC NetBanking and Mobile Banking App, or sends an official SMS from sender ID HDFCBK:

What It Looks Like

“Special One-Time Concession Offer” Banner

The screen shows your credit card or loan number with a slider offering to close the account if you pay a single lump-sum amount. To make sure it is genuine, check that the website link starts with https://netbanking.hdfcbank.com with a secure lock icon.

The Hidden Trap

App Offers Only Give Small Discounts (20%–35%)

These automated app offers are designed to see if you will panic and pay. They usually offer only a 20% to 35% discount on your inflated total bill. If you have genuinely lost your job, suffered business losses, or had major medical emergencies, you do not need to accept this small discount.

Smart Borrower Tip: Take a clear screenshot of the NetBanking discount offer! This screenshot is official proof that HDFC Bank has already approved your account for a settlement haircut. You can show this screenshot to senior recovery officers or at Lok Adalat as your starting point to push for a much better 50% to 70% discount.

11. Elements of a Valid HDFC Settlement Letter & How to Check It

Never pay a single rupee based on a phone call, WhatsApp text, or informal email! Fake recovery agents often send fake letters, collect your money, and pocket it while your debt stays unpaid. An official HDFC Bank settlement letter must have all 7 safety checkpoints:

✓ 1.Official Bank Letterhead: Must be printed on official HDFC Bank stationery showing the Mumbai corporate office address (HDFC Bank House, Lower Parel, Mumbai).
✓ 2.Unique Reference Number: Must have an internal tracking number (e.g. HDFC/SAMB/2026/SET-XXXX) that exists in the bank's computer system.
✓ 3.Your Exact Details: Must clearly list your full legal name, PAN card number, and your exact 16-digit card number or loan account number.
✓ 4.Clear Money Breakdown & Deadline: Shows the total amount owed, the discount given, and the exact settlement amount you must pay (in both numbers and words), along with a clear payment deadline.
✓ 5.Full & Final Closure Clause: Must clearly state in plain words: “Upon payment of the agreed settlement amount on or before the due date, this account shall stand fully settled and closed with no further dues or claims.”
✓ 6.Official Signature & Stamp: Signed and stamped by an authorized HDFC manager with their official employee code number.
✓ 7.Official Bank Email Delivery: If sent by email, it must come strictly from an official @hdfcbank.com email address-never from Gmail, Yahoo, or agency emails.

12. What Happens to Your CIBIL Score & How to Fix It

After you settle a loan with HDFC Bank, here is the truth about how credit bureaus record it and how you can restore a clean 750+ CIBIL score:

1. The Immediate CIBIL Reality

Within 30 to 45 days after settlement, HDFC Bank updates CIBIL and other credit bureaus. Because you paid less than the full amount, the bank marks the account status as “Settled” (or “Post-Write-off Settled”), and lists the waived discount under “Amount Written Off”. Your score will drop by 70 to 120 points, and banks will avoid giving you new unsecured credit cards for 2 to 3 years.

2. Can You Change “Settled” to “Closed” Later?

Yes! If your financial situation improves 2 to 3 years later (for example, you get a great job or want to apply for a home loan), HDFC allows you to clear the record:

  • Write to the Principal Nodal Officer (pno@hdfcbank.com) asking to convert your account from “Settled” to “Closed”.
  • HDFC calculates the exact discount amount that was originally waived (they do not add compound interest for the past years).
  • Once you pay that remaining difference directly to the bank, HDFC issues a fresh “Paid in Full” No Dues Certificate.
  • In the next monthly CIBIL update, HDFC changes your account status from “Settled” to clean “Closed” with ₹0 written off.
How to Rebuild Your Credit Score Fast: If you cannot pay the old waived balance, simply deposit ₹20,000 to ₹30,000 in a Fixed Deposit (FD) at a bank and get an FD-backed credit card. Spend a small amount every month and pay the bill in full before the due date. Within 18 to 24 months, your CIBIL score will bounce back above 750+.

13. Frequently Asked Questions (12 High-Intent Q&As)

How much discount or waiver can I realistically get on an HDFC personal loan settlement?
For unsecured personal loans and Jumbo loans delayed past 6 months (180 days), HDFC's special recovery branch routinely approves 50% to 70% discounts on your total unpaid interest and late fees. This usually means paying around 35% to 55% of your original borrowed principal. The biggest discounts happen at the end of March, June, September, and December when branch managers face quarterly targets.
Can HDFC Bank freeze my savings account if I default on an HDFC credit card?
Yes! Under Section 171 of the Indian Contract Act (Banker's Right of Set-Off), HDFC can legally pull money directly from your HDFC savings, salary, or fixed deposit account to pay off your credit card or personal loan without a court order. To protect your family's grocery and rent money, immediately move your salary to a completely different bank (like SBI, PNB, or Bank of Baroda) before you miss an EMI.
Can HDFC Bank file a criminal police FIR against me for defaulting on an unsecured loan?
No. Defaulting on a loan is purely a civil dispute, not a crime. Any recovery agent who threatens police arrest or FIR is breaking the law. Under Section 351 of the Bharatiya Nyaya Sanhita (BNS) 2024, threatening a borrower is considered criminal intimidation. You can report abusive agents directly to the local police and the RBI Banking Ombudsman.
What is the difference between HDFC Loan Foreclosure and HDFC Loan Settlement?
Foreclosure means you paid 100% of your loan before the tenure ended; your CIBIL report says "Closed" and your score goes up. Settlement (OTS) means you were in financial distress and the bank agreed to accept a discount (e.g. 50% less) to close the account; your CIBIL report will say "Settled", which drops your score for a few years.
Why does HDFC Bank refuse principal waivers on Home Loans?
Because home loans are secured by your house papers. When you took the loan, the bank kept your original property registry deeds. Under the SARFAESI Act, 2002, if you don't pay, the bank can auction the house to recover its money. However, you can negotiate to cancel 100% of the late fees and penalty interest, or ask for 90 days to sell the house yourself in the market to protect your hard-earned money.
How do I know if an HDFC settlement letter is genuine or fake?
A real HDFC settlement letter is always printed on official bank letterhead with the Mumbai head office address, has a unique tracking reference number, lists your exact loan or card number, shows the exact discount and net amount you must pay, includes a clear "Full and Final" closure sentence, is signed by a bank manager with their employee code, and is sent from an official @hdfcbank.com email address. Never pay cash to any agent.
What happens to HDFC loan settlement during National Lok Adalat?
National Lok Adalats are government-organized settlement courts held every 3 months. HDFC sends senior officers who have pre-approved powers to grant 50% to 70% discounts right on the spot. Best of all, a Lok Adalat agreement has the power of a final civil court decree-meaning the bank or any collection agency can never ask you for money again, and it is 100% free with no court fees.
How do I handle an HDFC Section 138 Negotiable Instruments Act or Section 25 notice?
A Section 138 notice (cheque bounce) or Section 25 notice (auto-debit bounce) gives you 15 days to respond. Do not ignore it. Hire a lawyer to send an official reply explaining your financial hardship and proposing a settlement. In almost all cases, this smoothly moves your file to Lok Adalat for an affordable settlement without any jail time.
How do gold loan defaults work at HDFC Bank?
Under Section 176 of the Indian Contract Act, HDFC cannot secretly melt or sell your gold. They must send you a registered notice giving you 14 days to clear the dues, and the auction price must match at least 90% of current market gold rates. If your gold sells for more than your loan balance, the bank is legally required to return the extra cash to your bank account within 30 days.
How long does HDFC Bank take to issue a No Dues Certificate (NDC) after settlement?
Once your agreed settlement payment clears, HDFC is required by RBI rules to send your official No Dues Certificate (NDC) or Closure Letter to your email and home address within 21 to 30 working days. They also update CIBIL within 30 days to show that the loan is settled.
Can I accept an automated HDFC settlement offer in the NetBanking app or negotiate lower?
The discount offer inside your NetBanking or Mobile App is real, but it usually offers only a small 20% to 35% discount. If your financial hardship is severe, do not accept this small offer immediately. Take a screenshot of the offer as proof that the bank has approved a settlement, and use that screenshot to negotiate for a much better 50% to 70% discount through the special recovery branch or at Lok Adalat.
Can I convert an HDFC "Settled" loan status to "Closed" in CIBIL in the future?
Yes! If your finances improve 2 to 3 years later, you can write to the Principal Nodal Officer (pno@hdfcbank.com) and offer to pay the remaining discount amount that was originally waived (without any extra interest). Once you pay that difference, HDFC will issue a fresh "Paid in Full" No Dues Certificate and update CIBIL from "Settled" to clean "Closed".

Official Statutory Grievance Portals & Regulatory Sources:

Find this content helpful?

If this guide has helped you navigate your settlement journey, consider showing some support to keep this platform running.