HomeAbout
BlogSoon
Bank specific setupSoon
LocationsSoon
WARNING: THIS IS NOT LEGAL ADVICE. THIS IS SURVIVAL ADVICE BASED ON REAL BORROWER EXPERIENCE.
UPDATED: SEPTEMBER 2026

Bajaj Finance Loan Settlement Process & OTS Rules in India

How to Settle Bajaj Personal, EMI Card & BHFL Debt

Complete borrower handbook for settling delinquent Bajaj Finance personal loans, Insta EMI cards, consumer durable loans, and Bajaj Housing Finance (BHFL) mortgages. Learn how to stop 50+ daily recovery calls, cancel predatory NACH bounce charge cascades, legally counter unilateral sole arbitration notices from Pune or Delhi under Supreme Court precedents, and negotiate 50% to 75% one-time settlement (OTS) waivers during National Lok Adalats.

Bajaj Finance Loan Settlement Process and OTS Roadmap

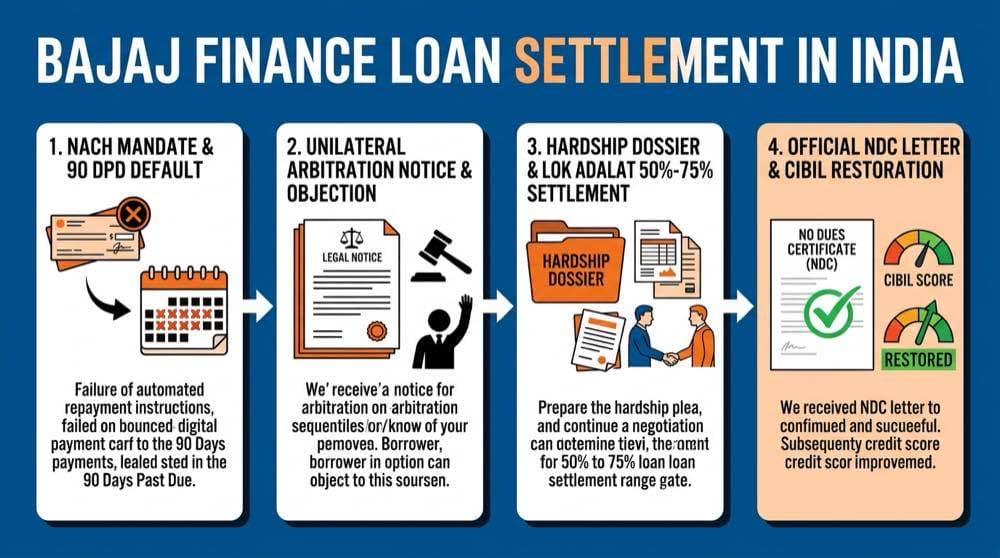
Visual Blueprint: Bajaj Finance 4-Stage Delinquency, Arbitration Defense & Lok Adalat OTS Settlement Roadmap

Quick Answer Summary

Bajaj Finance settlements are negotiable once an unsecured loan or Insta EMI card crosses 180+ DPD, at which point accounts transfer to Asset Recovery teams or National Lok Adalat with 50% to 75% waiver mandates. Because Bajaj is an NBFC, they cannot freeze your bank account directly under Section 171 Banker's Lien; immediately cancel your external bank NACH mandate to stop recurring ₹450 to ₹1,200 bounce penalties. If served unilateral sole arbitration notices from Pune or Delhi, object formally under Supreme Court Perkins Eastman precedents.

⚡ Empirical CalculatorUNSECURED NBFC

Bajaj Finserv Settlement & Haircut Estimator

Calculate realistic One-Time Settlement (OTS) compromise ranges based on Bajaj Finance NBFC recovery guidelines.

Unsecured personal loan. Delinquent accounts past 180 DPD qualify for 100% penal bounce fee waivers and up to 55% principal reduction.

₹3,50,000
₹25,000₹25,00,000₹50,00,000
Target Settlement Offer:50%–65% Haircut
Realistic Settlement Range:₹1,22,500₹1,75,000
Estimated Debt Forgiven:₹1,75,000₹2,27,500
*100% of accumulated penal bounce charges & GST waived on OTS compromise.
⚠️
Bajaj Finance Legal Caveat:Bajaj Finance recovery algorithms aggressively deploy automated telecalling and arbitration notices. Settle via their official PNO or Stressed Asset Manager.
⚡ Regulatory Shield4-STAGE LADDER

Bajaj Finance 4-Stage Redressal Hierarchy

If recovery agents violate RBI calling guidelines or threaten criminal prosecution, escalate through Bajaj Finance apex compliance desks.

Tier 1: Customer Care & Branch ServiceSLA: 7 Working Days

Frontline Customer Support Team

wecare@bajajfinserv.in | 08698010101

Scope: Routine queries, statement requests, NACH bounce dispute logging, and payment verification.

Action: Submit your formal loan settlement proposal or initial harassment complaint. Request a formal ticket reference number.

Tier 2: Grievance Redressal Officer (GRO)SLA: 10 Working Days

Mr. Sowmiyanarayanan Srinivasan (Head of Grievance)

grievanceredressalteam@bajajfinserv.in | 022 4180 3901

Scope: Unresolved Tier 1 complaints, third-party recovery agent harassment, abusive telecalling, and uncredited payments.

Action: Quote your Tier 1 ticket number. Attach call recordings, screenshots of agent WhatsApp threats, and financial hardship proofs.

Tier 3: Principal Nodal Officer (PNO)SLA: 10 Working Days

Mr. Yogesh Sharma (Principal Nodal Officer)

ospno@bajajfinserv.in | 079 7126 8594

Scope: Institutional dispute resolution, unilateral sole arbitration objections, Section 25 PSS Act notice representations, and final OTS approvals.

Action: Email formal representation challenging illegal recovery tactics or proposing lump-sum OTS. Send via speed post to Corporate Office, Pune.

Tier 4: RBI Integrated OmbudsmanSLA: 30 Working Days

Reserve Bank of India Statutory Ombudsman

cms.rbi.org.in | CRPC, RBI, 4th Floor, Sector 17, Chandigarh | 14448

Scope: Violations of RBI Fair Practices Code, non-adherence to recovery guidelines, harassment of relatives/contacts, and refusal to resolve legitimate disputes within 30 days.

Action: File online at cms.rbi.org.in quoting your Bajaj PNO docket number. Request compensation for mental harassment and direction for debt regularisation.

Pre-Drafted Dispute & OTS Notice:
FORMAL DISPUTE NOTICE & FINANCIAL HARDSHIP OTS PROPOSAL To: The Principal Nodal Officer (PNO) / Grievance Redressal Officer, Bajaj Finance Limited, Corporate Office, Pune, Maharashtra. Email: ospno@bajajfinserv.in / grievanceredressalteam@bajajfinserv.in Subject: Formal Hardship Dispute, Anti-Harassment Notice & One-Time Settlement (OTS) Request for Loan Account No: [INSERT YOUR BAJAJ LOAN NO.] Respected Principal Nodal Officer, I am writing to formally register my financial hardship and present a bona fide proposal for One-Time Settlement (OTS) regarding the above-referenced loan account. 1. STATEMENT OF GENUINE FINANCIAL HARDSHIP: Due to unforeseen financial setbacks [e.g. involuntary job loss / severe medical crisis / critical business revenue reduction], my income stream has been severely impacted. Consequently, I have been unable to service the regular monthly EMIs despite my sincere intent. 2. CESSATION OF RECOVERY AGENT HARASSMENT (RBI MANDATE): Third-party recovery agents representing Bajaj Finance have made repeated abusive calls, contacted my relatives/workplace references, and threatened unlawful physical action. I place on record that such conduct directly violates: - Reserve Bank of India (RBI) Fair Practices Code for NBFCs (Master Direction DNBR.PD.008/03.10.119/2016-17). - Section 351 of the Bharatiya Nyaya Sanhita (BNS, 2024) for Criminal Intimidation. - Section 329 of the Bharatiya Nyaya Sanhita (BNS, 2024) for Criminal Trespass. I demand that all third-party collection agency harassment cease immediately. All future communication must be conducted strictly in writing via my registered email or postal address. 3. OBJECTION TO UNILATERAL SOLE ARBITRATOR APPOINTMENT: Any notice purporting to unilaterally appoint a sole arbitrator in Pune or Delhi without my mutual written consent is legally void ab initio under the landmark Supreme Court of India precedents: - Perkins Eastman Architects DPC v. HSCC (India) Ltd. (2020) 20 SCC 760. - TRF Ltd. v. Energo Engineering Projects Ltd. (2017) 8 SCC 877. I reserve the right to challenge any ex-parte arbitral proceedings before the appropriate High Court under Section 14 and Section 34 of the Arbitration and Conciliation Act, 1996. 4. BONA FIDE ONE-TIME SETTLEMENT (OTS) OFFER: To achieve an amicable, full and final closure without protracted litigation, I offer to pay a lump sum of ₹[ENTER REASONABLE AMOUNT, E.G., 35% TO 50% OF PRINCIPAL] towards the full and final settlement of all claims. I request a 100% waiver of all accumulated penal interest, late payment charges, and repeated NACH bounce fees. Upon acceptance, please issue an official Settlement Offer Letter on Bajaj Finance letterhead specifying: a) The exact agreed settlement amount and payment deadline. b) Confirmation that payment will be credited directly to my loan account number. c) Explicit commitment to issue a formal No Dues Certificate (NDC) and update my credit bureau records (CIBIL) to "Settled" status within 30 days. I look forward to your prompt and fair response within 10 working days. Yours sincerely, [Your Full Name] [Registered Mobile Number] [Registered Email Address] [Postal Address]

*Replace all [BRACKETED FIELDS] with your actual loan details before emailing.

1. Why Bajaj Finance Settles Overdue Loans

Bajaj Finance Limited (BFL) is India's largest retail non-banking financial company with over 80 million active customers. Because it is an Upper Layer NBFC (NBFC-UL) regulated under the Reserve Bank of India (Scale Based Regulation) framework, BFL must adhere to strict provisioning timelines for bad loans:

● 90 Days Past Due (NPA Tag): RBI mandates that Bajaj classify the account as a Non-Performing Asset (NPA). Capital reserves must be immediately sequestered.

● 180 Days Past Due (100% Provisioning): Once the default extends past 180 DPD, Bajaj must allocate 100% of the loan amount from its operating profits into a credit risk reserve.

● Quarterly Financial Targets: Bajaj operates on aggressive quarterly balance sheet targets closing on March 31, June 30, September 30, and December 31. During these cutoffs, regional recovery managers are evaluated on cash recovery, not protracted legal litigation.

● Central Asset Recovery Authority: Retail branch counters exist purely to disburse fresh loans and sell insurance. All compromise settlement authority rests with the central Asset Recovery wing in Pune and designated regional collection heads.

2. The NACH Auto-Debit Bounce Trap & Fix

Unlike commercial banks like HDFC, SBI, or ICICI, Bajaj Finance does not hold your savings or salary account. They cannot directly freeze your funds using Section 171 of the Indian Contract Act (Banker's General Lien).

Instead, Bajaj uses the National Automated Clearing House (NACH) mandate that you signed during loan onboarding. When an account defaults, Bajaj automated systems represent the payment mandate against your external bank account 2 to 3 times in a single billing cycle:

The Double Bounce Penalty Trap:

Bajaj Bounce Charge: ₹450 to ₹1,200 plus 18% GST added directly to your loan dues on every failed presentation.

Your Bank's Bounce Charge: ₹250 to ₹590 deducted automatically from your active savings account balance.

● Within 3 months of missed payments, automated NACH representations can inflate your debt by ₹6,000 to ₹15,000 in pure penalty fees.

Actionable Countermeasure: Log into your external bank netbanking portal, select “e-Mandates / NACH Services”, locate the Bajaj Finance mandate ID (UMRN), and submit a cancellation request. Under RBI circular DPSS.CO.CHD.No./2015-16, banks are legally bound to cancel customer mandates without requiring prior approval from the lending institution.

3. Unilateral Sole Arbitration Defense

Between 90 and 150 DPD, Bajaj Finance frequently issues an arbitration notice via speed post, email, or WhatsApp. The notice states that a “Sole Arbitrator” seated in Pune or Delhi has been appointed to adjudicate your loan dispute, often conducting proceedings virtually on digital mediation platforms.

Many borrowers panic, assuming this is an official court summons or arrest warrant. It is not. It is a private arbitral proceeding initiated under the standard arbitration clause in Bajaj's digital loan contract.

Landmark Supreme Court Precedents on Sole Arbitrators:

In Perkins Eastman Architects DPC v. HSCC (India) Ltd. (2020) 20 SCC 760 and TRF Ltd. v. Energo Engineering Projects Ltd. (2017) 8 SCC 877, the Supreme Court ruled that a party interested in the dispute (the lender) cannot unilaterally appoint a sole arbitrator without the mutual written consent of the borrower.

Under Section 12(5) of the Arbitration and Conciliation Act, 1996, an arbitrator appointed unilaterally by a finance company is legally ineligible to act. If you receive an arbitration notice, do not ignore it. Send our statutory objection template to both the arbitrator and the Bajaj PNO disputing their unilateral jurisdiction. This prevents them from obtaining an unchallenged ex-parte award.

4. Insta EMI Card & Consumer Durable Debt

Bajaj Finance built its retail dominance on the Insta EMI Card and 0% interest consumer durable loans used to purchase smartphones, televisions, laptops, and home appliances.

When a borrower misses payments on a ₹20,000 smartphone EMI, two major consequences occur:

  • Card Blocking & Compounding Penalties: The Insta EMI Card is immediately blocked, and monthly penal charges (up to 36% APR) plus repeated bounce charges are levied.
  • CIBIL Bureau Reporting: Even a tiny ₹1,500 monthly default is reported to TransUnion CIBIL, Experian, and CRIF High Mark as an active delinquent consumer loan, causing a severe credit score drop of 70 to 120 points.
The Settlement Reality for EMI Cards:Because the principal amounts are small (typically ₹10,000 to ₹1,00,000), recovery litigation costs Bajaj more than the debt itself. Once the card default passes 180 days, Bajaj Asset Recovery teams routinely approve 60% to 80% waivers on the inflated total balance, accepting just the original unpaid base principal to close the file.

5. Bajaj Finserv RBL SuperCard Entity Separation

🚨 Critical Legal Entity Distinction:

The **Bajaj Finserv RBL Bank SuperCard** is a co-branded credit card legally issued and governed by RBL Bank Limited, a scheduled commercial bank. Bajaj Finserv acts solely as the marketing and customer sourcing partner.

If you default on a SuperCard:

  • Bajaj Finance customer care has zero legal authority to settle the card or grant waivers.
  • Any settlement discussion with Bajaj Finance field agents will not reflect in your RBL Bank credit bureau records.
  • You must direct all settlement hardship letters directly to RBL Bank Credit Card Services (email: cardservices@rbl.bank.in) or the RBL Bank Principal Nodal Officer.

In an RBL Bank OTS, 100% of accumulated finance charges and late fees are eligible for waiver once the account crosses 180 DPD.

6. Personal, Business & BHFL Mortgages: 180+ DPD Delinquency Trajectory

Bajaj Finance personal loans (disbursed online via Experia up to ₹40 Lakhs) and MSME business loans are 100% unsecured. Conversely, mortgage advances are funded by Bajaj Housing Finance Limited (BHFL) under registered title deeds.

UNSECURED PERSONAL & MSME WAIVERS (50% TO 75%)Because Bajaj cannot attach physical property without a contested court decree, delinquent personal loans crossing 180+ DPD enter the loss asset pool, where central recovery committees sanction 50% to 75% waivers against total ledger balances upon proof of income or business distress.
BHFL MORTGAGES & SARFAESI ENFORCEMENTSecured housing loans trigger SARFAESI Section 13(2) (60-day demand) and Section 13(4) symbolic possession. While principal discounts on prime real estate are rare, BHFL credit authorities regularly waive 100% of accumulated penal interest, bounce surcharges, and legal inspection fees upon lump-sum principal clearance.
180+ DPD DELINQUENCY TRAJECTORY & LOK ADALAT BENCHESOnce an account enters 181+ DPD (Loss Asset status provisioned at 100% under RBI norms), telecalling stops and files are listed at National Lok Adalat drives, where Bajaj authorized officers execute binding compromise awards with court-decreed finality.

7. Official Sanction Letter Audit, Direct LAN Remittance & 30-Day NDC SLA

Never pay funds based on informal messages or verbal promises from field collection agencies. Every legitimate Bajaj Finance compromise must be audited against these statutory protocols:

01. Corporate Letterhead & Authenticated DomainMust be printed on Bajaj Finance Limited official stationery bearing the registered Akurdi, Pune corporate address and delivered exclusively from an authenticated @bajajfinserv.in domain.
02. Full & Final Discharge & Legal Withdrawal UndertakingThe sanction letter must explicitly state that payment of the agreed settlement sum constitutes full and final satisfaction of the loan with zero remaining balance, and that all pending Section 25 PSS complaints and unilateral arbitration proceedings are unconditionally withdrawn.
03. Direct LAN Remittance ChannelRemit settlement funds strictly into your individual 10-to-16-digit Bajaj Loan Account Number (LAN) via the official Experia portal, verified netbanking, or branch demand draft. Never transfer money into personal UPI handles or third-party agency accounts.
04. Mandatory 30-Day NDC SLA (RBI Mandate)Under RBI Circular RBI/2023-24/60, Bajaj Finance is legally obligated to issue your No Dues Certificate and return all original mortgaged property documents within 30 days of full settlement credit. Failure entitles you to statutory compensation of ₹5,000 per day of delay.
05. Post-Settlement CIBIL RehabilitationVerify at 45 days that credit bureaus reflect a zero balance with status marked “Settled”. Rebuild your score back past 750 over 18 to 24 months through disciplined utilization (under 20%) of a fixed-deposit backed credit card.

8. Frequently Asked Questions (Bajaj Finance Loan Settlement)

Can I settle a Bajaj Finance personal loan or Insta EMI card for a 50% to 75% waiver?
Yes. Once an unsecured Bajaj personal loan or EMI card enters 180+ days past due (180+ DPD), Bajaj Finance provisions 100% of the loan value under RBI guidelines. At this stage, your file is transferred from call centers to the Asset Recovery team or referred to National Lok Adalat, where officers approve 50% to 75% waivers on accumulated bounce charges and interest.
How do I stop Bajaj Finance from repeatedly deducting NACH bounce charges?
Bajaj Finance represents failed payment mandates 2 to 3 times a month, triggering ₹450 to ₹1,200 plus GST each time from Bajaj and bounce penalties from your own bank. Log in to your bank netbanking portal, navigate to the e-Mandate or NACH section, and cancel the Bajaj Finance mandate. Alternatively, submit a written mandate cancellation form at your bank branch under RBI circular DPSS.CO.CHD.No./2015-16.
What should I do if I receive an arbitration notice from a sole arbitrator in Pune or Delhi?
Do not panic. Under landmark Supreme Court rulings in Perkins Eastman Architects DPC v. HSCC (India) Ltd. and TRF Ltd. v. Energo Engineering Projects Ltd., unilateral appointment of a sole arbitrator by a lender without your mutual written consent is legally void. Send our statutory objection notice to the arbitrator and Bajaj Finance PNO disputing their unilateral jurisdiction.
Can Bajaj Finance freeze my savings account under Section 171 Banker's Lien?
No. Bajaj Finance is an Upper Layer Non-Banking Financial Company (NBFC-UL), not a commercial bank. Because Bajaj does not hold your savings or salary accounts, it cannot exercise a direct Banker's Lien to freeze internal funds. However, they can trigger NACH debits, which is why canceling the bank mandate is essential.
Can I settle my Bajaj Finserv RBL Bank SuperCard with Bajaj Finance?
No. The Bajaj Finserv RBL Bank SuperCard is legally issued and governed by RBL Bank Ltd, not Bajaj Finance. Bajaj is merely the marketing partner. You must negotiate settlement directly with RBL Bank Cards Collection department at cardservices@rbl.bank.in.
Can Bajaj Finance arrest me if my EMI bounces?
No. Loan default is strictly a civil financial dispute under Indian law. While Bajaj Finance may send a legal notice under Section 25 of the Payment and Settlement Systems Act for NACH bounce, it is a bailable complaint, not a non-bailable arrest warrant. Police cannot arrest you for unpaid NBFC loans.
Can Bajaj Finance recovery agents visit my office or call my relatives?
Calling relatives, workplace harassment, and threatening family members directly violate the RBI Fair Practices Code for NBFCs and constitute criminal intimidation under Section 351 of the Bharatiya Nyaya Sanhita (BNS). Record the calls, take photos of visiting agents, and lodge an immediate complaint with the Principal Nodal Officer at ospno@bajajfinserv.in.
Why is National Lok Adalat the best venue to settle Bajaj Finance debt?
Bajaj Finance participates heavily in quarterly National Lok Adalats organized by DLSA across India. Lok Adalat settlement officers have pre-delegated authority to offer maximum discounts (up to 75% waiver) to clear bulk non-performing accounts. The resulting compromise decree is final, binding, and permanently extinguishes all future legal claims.
How do I verify if a Bajaj Finance settlement offer letter is genuine?
A genuine settlement letter comes from an official @bajajfinserv.in email address, carries an authorized digital signature and company seal, specifies payment directly to your Bajaj loan account number, states that payment constitutes "Full and Final Settlement", and guarantees a No Dues Certificate (NDC) within 30 days.
Can Bajaj Housing Finance Ltd (BHFL) auction my property under SARFAESI?
Yes. BHFL holds your original title deeds under an equitable mortgage. If your housing loan defaults past 90 days, they can issue a Section 13(2) 60-day demand notice followed by Section 13(4) symbolic possession. You can negotiate a 100% waiver on compound penal interest before the auction date by offering a lump-sum principal clearance.
What is the best month to negotiate a loan settlement with Bajaj Finance?
March, June, September, and December. Bajaj Finance operates on quarterly financial targets. During quarter-end cutoffs, recovery managers have higher write-off budgets and are under pressure to resolve delinquent files before balance sheet publication.
How does settling a Bajaj loan impact my CIBIL score?
The loan will be reported as "Settled" rather than "Closed", causing an initial 50 to 100 point drop. However, by taking an FD-backed credit card, keeping credit utilization below 30%, and maintaining flawless repayment history, you can rebuild your score back above 750 within 18 to 24 months.

Official Statutory Grievance Portals & Regulatory Sources:

Find this content helpful?

If this guide has helped you navigate your settlement journey, consider showing some support to keep this platform running.