Bank Settlement Letter Formats: Sample PDF Download and Guide
Official OTS Proposal Templates, RBI Rules and Formats
Download verified One-Time Settlement request formats and examine genuine bank approval letters. Learn the 6 mandatory clauses that legally protect you from residual debt claims.
A valid bank settlement letter must arrive on official bank letterhead. It must come from an authorized bank email domain. The letter must state your 16-digit loan account number and the exact settlement amount. It must contain a full and final discharge clause under Section 63 of the Indian Contract Act. The bank must promise to update credit bureaus within 30 days. It must also agree to issue a formal No Dues Certificate. Never pay any money before receiving this signed document.
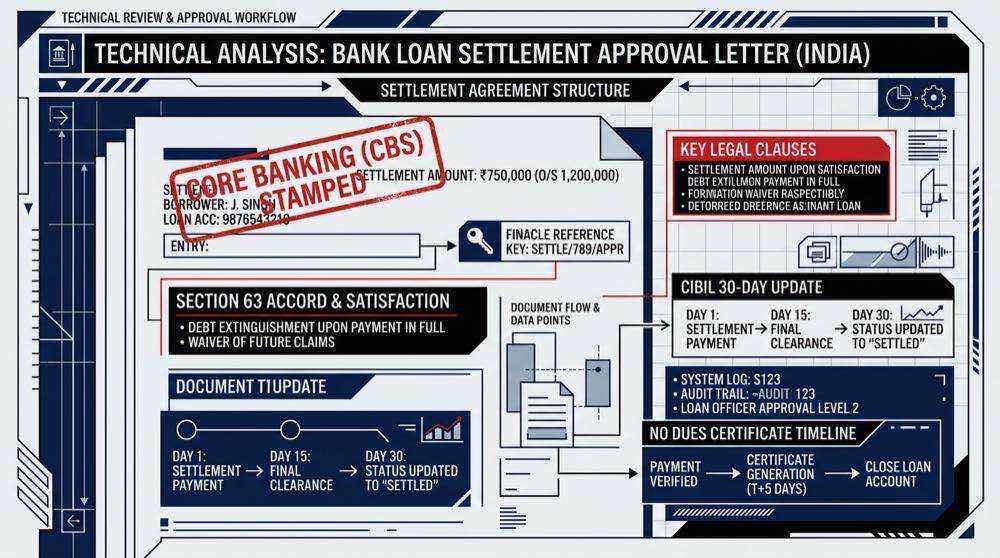
Figure 1: Complete Anatomical Breakdown of a Legally Enforceable Bank Loan Settlement Letter
Watch 59-Sec Explainer: How to Spot a Fake Bank Settlement Letter
WhatsApp PDF Scams, HDFC CBS Audit Key Verification & 30-Day RBI No Dues Rules
- ●Never Pay Agent UPI: Recovery agents often create forged PDF letterheads to pocket money via personal UPI handles. Always deposit directly into your 16-digit bank loan account.
- ●CBS Audit Key: Genuine settlement letters arrive from official bank email domains and carry a verifiable Core Banking reference key (e.g. HDFC-OTS-2026).
- ●Section 63 Full Accord: Legally discharges the debt under the Indian Contract Act with a 30-day CIBIL bureau update mandate.
- ●30-Day NDC Mandate: RBI rules require the bank to issue your No Dues Certificate within 30 days or pay a ₹5,000 per day penalty for delay.
Ground Reality Note: Book Rules vs Daily Harassment
Scam ShieldAll RBI circulars, banking rules, and contract laws exist officially on paper. However, the ground reality in India is very different. Third-party recovery agencies often invent fake discount schemes to hit monthly collection targets. They send fabricated PDF letters over WhatsApp promising a 60% waiver. They demand instant UPI payment and disappear. The bank never receives your money. Your loan stays open with rising penal charges.
You have zero legal protection until you hold a system-verified sanction letter. You must deposit funds directly into your loan account number. Real peace of mind only begins when your loan balance shows zero in the core banking system.
1. Never Pay Based on Verbal Promises: If a telecaller or field agent promises a settlement discount over the phone, ignore it. Demand a formal approval letter on the official letterhead of the bank or NBFC before transferring a single rupee.
2. Deposit Only into Your Loan Account: Never transfer settlement funds to a recovery agency bank account, a collection manager UPI handle, or pay cash. Every rupee must be paid directly into your official 16-digit bank loan account.
3. Verify in Core Banking Before Paying: Walk into your bank branch or email the central nodal desk. Ask the branch manager to confirm the settlement sanction key in Finacle or BANCS before releasing the payment.
01. How to Draft a Formal One-Time Settlement Request Letter
Your initial proposal sets the legal framework for loan settlement. Always write directly to the Branch Manager or Principal Nodal Officer. Your letter must explain genuine financial hardship. Common hardships include medical illness, business failure, or job loss. You must clearly state your inability to pay rather than a refusal to pay.
Auto-Generate and Email Your OTS Hardship Letter
Select your bank, enter your loan details, and send an official hardship letter directly to the bank Nodal Officer and Stressed Asset resolution desk.
Under RBI rules, banks can take legal action if a borrower refuses to pay despite having money. Always frame your request around genuine hardship. Attach medical bills, job termination letters, or bank statements as proof.
02. Authentic Bank Settlement Approval Letter Specimen
While your OTS proposal initiates negotiations, the bank settlement approval letter is your final legal shield. This is the formal sanction letter issued by the bank confirming debt discharge. Inspect the annotated specimen below to see every mandatory element that must appear on official bank letterhead:
Specimen: Authentic Bank Settlement Approval Letter
Examine this realistic sample settlement sanction letter issued by a bank. Inspect the 6 mandatory checkpoints highlighted in red and blue to ensure your settlement document is legally enforceable.
Dear Sir / Madam, with reference to your hardship representation dated 15 September 2026, the Competent Authority has sanctioned a One-Time Settlement (OTS) for your Personal Loan facility subject to the strict adherence of all terms detailed below:
| Accounting Component | Contractual Dues | Bank Waiver | Approved Payable |
|---|---|---|---|
| Principal Outstanding | Rs. 3,25,000 | Rs. 1,50,000 | Rs. 1,75,000 |
| Overdue Normal Interest | Rs. 95,400 | Rs. 95,400 | Rs. 0 |
| Penal Interest & Bounce Fees | Rs. 82,400 | Rs. 82,400 | Rs. 0 |
| Legal Charges & Incidental Costs | Rs. 40,000 | Rs. 40,000 | Rs. 0 |
| Total Net Settlement | Rs. 5,42,800 | Rs. 3,67,800 | Rs. 1,75,000 |
Payment Window: The net approved settlement amount of Rs. 1,75,000/- must be deposited directly into Loan Account Number 5010048291054321 via RTGS / NEFT on or before 15 October 2026. Cash payments and transfers to recovery agency accounts are strictly prohibited and legally null.
Full and Final Discharge: Upon unconditional receipt and clearance of Rs. 1,75,000/- within the validity window, the borrower stands fully and permanently discharged from all past, present, and future contractual liabilities in respect of this loan facility. The remaining balance of Rs. 3,67,800/- stands written off.
Legal and Regulatory Covenants: The bank covenants to withdraw all pending proceedings under Section 138 of the Negotiable Instruments Act, Section 25 of the Payment and Settlement Systems Act, and Arbitration matters within 15 working days. The bank further undertakes to report the account as "SETTLED" with zero balance to TransUnion CIBIL, Experian, Equifax, and CRIF High Mark within 30 days, and issue the official No Dues Certificate along with returning all security cheques.
Compare the letter you received with the specimen above. If it does not have an internal CBS Reference Key, fails to specify your 16-digit loan account, or is sent from a personal Gmail or WhatsApp account, it is likely fraudulent. Never release payment until these 6 checkpoints are verified.
03. 6 Mandatory Clauses in a Valid Bank Settlement Letter
A settlement letter must contain specific legal clauses under RBI compromise rules and Section 63 of the Indian Contract Act. If any clause is missing, the bank can demand the remaining balance later. An asset reconstruction company could also reopen your debt.
The letter must state that the settlement payment ends all claims. This discharges the original loan contract under Section 63 of the Contract Act. The Supreme Court upheld this rule in Lala Kapurchand Godha v. Mir Nawab Himayatalikhan Azamjah.
The letter must list the principal, normal interest, penal fees, and legal costs separately. It must clearly state the exact amount waived by the bank. It must also show the final net payable figure.
The letter must state the exact payment deadline or installment dates. It must instruct you to deposit funds directly into your 16-digit loan account. Payments into agency pool accounts or UPI IDs are invalid.
Under Section 21 of CICRA 2005, the bank must update your credit records. It must report the account as Settled to CIBIL, Experian, CRIF, and Equifax within 30 days of receiving payment.
The bank must agree to issue an official No Dues Certificate. Under RBI rules, it must return all security cheques or property title deeds within 30 days. Any lender delay requires a compensation of Rs. 5,000 per day.
The bank must promise to withdraw all court cases. This includes cheque bounce cases under Section 138, NACH cases under Section 25, and arbitration claims once payment clears.
04. Bank-Specific Formats: What Genuine Letters Look Like
Different lenders use unique document formats. Below is how top Indian banks and NBFCs structure their official settlement letters:
Issued by the Stressed Assets Resolution Branch (SARB) or Stressed Assets Recovery Branch. Carries the title "Sanction of Compromise Settlement under SBI OTS Scheme". Reference key starts with SARB/[City]/OTS/[Year] and is signed by an Assistant General Manager (Scale V) or Deputy General Manager.
Issued by the "Retail Loan Service Desk" or "Collections Legal Department" on corporate blue letterhead. Contains the 16-digit Card or Loan Number, includes a structured table showing Principal Overdue, Charges Waived, and Net Payable, and requires borrower countersignature on an Acceptance Copy.
ICICI Bank generates letters through its Debt Resolution Forum. The system reference code reads DRF-[Month]-[Year]-[Digits]. The letter warns that the offer becomes void if payment is delayed by even 24 hours past the due date.
Issued specifically by "IndusInd Bank Limited - Consumer Finance Division". For auto and two-wheeler loans, the letter cites the vehicle registration number and chassis number, including an explicit covenant to issue Form 35 and vehicle NOC.
Navi Finserv generates letters digitally through its core platform. Each letter has a dynamic QR code and a digital signature. Your settlement status reflects inside the Navi mobile app within 48 hours.
KreditBee letters arrive on Krazybee Services letterhead or from its partner NBFCs. Partner lenders include Northern Arc, InCred, and Vivriti. The letter lists both the app loan ID and the NBFC account number, confirming full clearance across both lenders.
05. Real vs Fake Bank Settlement Letter Comparison Matrix
Use this side-by-side comparison table to detect fraudulent settlement letters before releasing any funds:
| Check | Fake Agent Template | Genuine Bank Letter |
|---|---|---|
| Delivery | WhatsApp PDF / Gmail | Official bank domain / branch |
| System Key | Blank or made-up text | Finacle / BANCS CBS reference |
| Payment | Agency account or UPI | Direct 16-digit loan account |
| Signatory | Copied stamp, no ID | Scale IV/V Manager with code |
| Bureau | Verbal promise / omitted | Explicit 30-day CIBIL clause |
| Timeline | Pay within 4 hours | 7 to 30 days payment window |
06. Step-by-Step Protocol to Pay Your Settlement Safely
Follow this 4-step checklist when executing a settlement payment to ensure your funds reach the lender:
Never pay any advance money based on phone calls or WhatsApp chats. Always demand a signed and stamped letter on bank letterhead. Ensure it carries a verifiable core banking ticket.
Visit your home branch or email central customer care from your registered ID. Ask the branch manager to verify the reference key in Finacle or BANCS. Confirm that interest has been frozen.
Transfer funds using your banking app directly into your 16-digit loan account number. In the payment remarks or narration, write "Full and final settlement for Loan No [Number]". Save the UTR reference number.
Collect a stamped bank receipt or account statement showing a zero balance. Under RBI rules, the lender must issue your No Dues Certificate within 30 days. Track this delivery closely.
07. Frequently Asked Questions About Bank Settlement
How can I get an official loan settlement letter from my bank?+
Submit a written One-Time Settlement request letter to your bank branch manager. You can also write to the Principal Nodal Officer. Provide evidence of genuine hardship, such as medical bills or a job termination letter. Once approved, the bank will issue a formal sanction letter on corporate stationery.
Can a bank demand money after issuing a loan settlement letter?+
No. Under Section 63 of the Indian Contract Act, the debt is fully discharged once the bank accepts the agreed sum. The Supreme Court upheld this in Lala Kapurchand Godha v. Mir Nawab Himayatalikhan Azamjah. The bank cannot legally claim the waived balance later.
What should I check before paying money for a loan settlement?+
Check that the letter comes from an official bank email domain. Ensure it has a genuine core banking reference key. It must state your 16-digit loan account number and confirm full debt discharge. Always pay directly into your loan account and never to an agency account.
Does a loan settlement letter guarantee removal of CIBIL default?+
A settlement letter does not erase the loan from your credit report. Under RBI rules, the bank reports the account as Settled rather than Closed. This freezes interest and stops court action. However, the Settled mark remains on your bureau file for up to 7 years.
How long does a bank take to issue a No Dues Certificate after settlement?+
Under RBI rules, lenders must deliver your No Dues Certificate within 30 days of payment. They must also return all original property deeds and security cheques. If the bank delays beyond 30 days, it must pay compensation of Rs. 5,000 per day.
What if a recovery agent sent me a fake settlement letter on WhatsApp?+
Do not transfer any money. Immediately call the National Cyber Crime Helpline at 1930. File a formal complaint on the RBI CMS portal against the lender. The bank is legally responsible for monitoring its collection agencies. Attach the fake letter copy as evidence.
Community Discussion & Case Notes
0 CommentsNo comments posted yet. Be the first to share your experience below!
Join the Discussion & Share Your Experience
Have you dealt with this situation or received a notice? Share your questions or experience with other borrowers.
Official Statutory Resources & Regulatory Portals
RBI & GOVT VERIFIEDAccess official government portals, regulatory ombudsman channels, and statutory dispute resolution bodies governing Indian banking and borrower rights:
- RBI Integrated Ombudsman Scheme (CMS)↗
File complaints against bank recovery abuse and fair practice violations
- RBI Sachet Portal (Illegal Recovery & Harassment)↗
Report unauthorized lending apps and aggressive recovery agency violations
- NALSA National Lok Adalat Schedules↗
Statutory alternative dispute resolution for mutually agreed OTS settlements
- National Consumer Helpline (NCH)↗
Government grievance redressal under Department of Consumer Affairs
- National Cyber Crime Reporting Portal (1930)↗
Official reporting for recovery blackmail, cyber threats, and extortion
- Section 63 Indian Contract Act, 1872↗
Doctrine of Accord and Satisfaction allowing creditor debt discharge without fresh consideration
- RBI Compromise Settlements Framework (June 8, 2023)↗
Official master directions on board-approved compromise settlements and technical write-offs
- Section 21 Credit Information Companies Act, 2005↗
Statutory obligation of lenders to update borrower credit bureau status within 30 days
- RBI Master Direction on Property Documents (2023)↗
Mandatory release of title deeds within 30 days with Rs. 5,000 per day delay penalty
Find this content helpful?
If this guide has helped you navigate your settlement journey, consider showing some support to keep this platform running.