WARNING: THIS IS NOT LEGAL ADVICE. THIS IS SURVIVAL GUIDANCE BASED ON STATUTORY INDIAN LAW AND BORROWER EXPERIENCE.
UPDATED: SEPTEMBER 2026

IDFC Loan Foreclosure: Step-by-Step Charges, Process & NOC Rules

Complete Guide to Foreclosing Personal, Vehicle & Home Loans

Foreclosing your IDFC loan early stops all future monthly interest. You clear your debt ahead of time. However, you must handle foreclosure charges correctly. You must also stop automated NACH debits, recover bundled insurance money, and collect your official No Dues Certificate.

Quick Answer: How to Foreclose an IDFC Loan

You can foreclose your loan online via the IDFC mobile app or the QuickPay portal. Under RBI rules, floating-rate personal and home loans carry zero penalty. Products like FIRSTmoney also charge zero fees. Fixed-rate personal loans and two-wheeler loans charge 3% to 5% plus 18% GST. Pay your balance at least 7 days before your EMI date to avoid double debits. Download your No Dues Certificate within 72 hours.

Ground Reality NoteBook Rules vs Reality
The Harsh Reality: Why System Slowness Demands Direct Self-Protection

All these RBI rules, regulatory guidelines, and police FIR provisions exist officially in the books. However, the ground reality is that the Indian judicial and police system moves very slowly. In most everyday cases, lodging a formal complaint or filing an FIR will not give you immediate relief from aggressive collection calls.

The honest fact is: until all of your outstanding loans are either officially settled (via One-Time Settlement) or fully closed, the probability of getting complete peace of mind from recovery agencies is very low.

Pro Survival Tips for Immediate Peace:

1. Change Your Mobile Number: Switch to a fresh SIM card for daily use, sharing it strictly with close family. Keep your old loan-registered SIM on silent in a spare phone to check SMS once weekly for official bank notices. This instantly cuts off the non-stop daily barrage of abusive phone calls.

2. Shift Your Residential Address: If recovery agents or local collection musclemen know your rented flat and keep showing up to humiliate you before neighbors, relocate to a different address if possible to protect your family from doorstep embarrassment.

3. Delete the Loan App & Revoke All Permissions: Immediately uninstall the lending app from your smartphone. Before deleting, open phone settings, revoke all permissions (contacts, storage, camera, location), and clear app data so trackers cannot continue harvesting your real-time data or accessing your contact list.

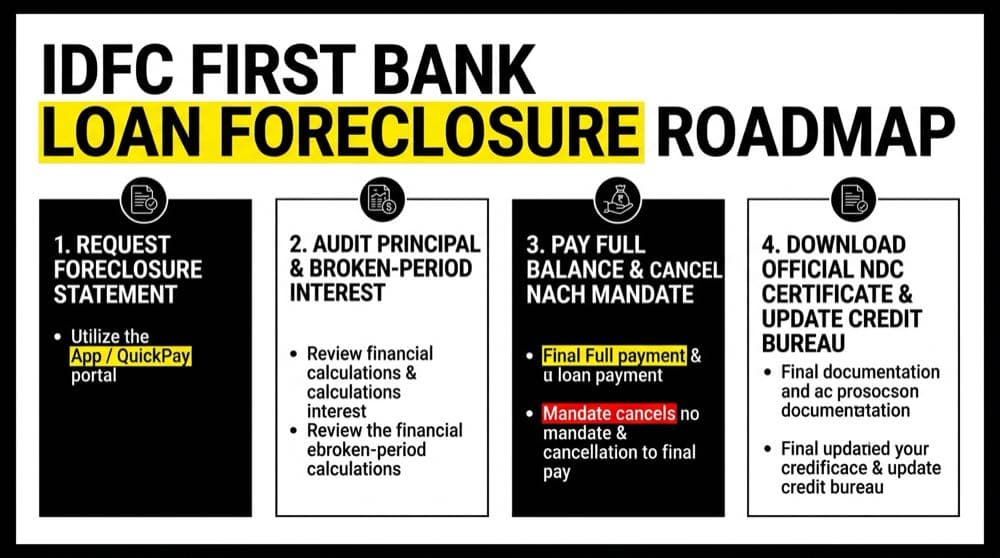
Step-by-step roadmap for IDFC FIRST Bank loan foreclosure, charges calculation, and NOC download

Visual Blueprint: 4-stage operational roadmap for fetching IDFC foreclosure quotes, auditing broken interest, and securing NDC.

01. Foreclosure vs Part-Prepayment Explained

Foreclosing a loan means paying off your full debt early. You pay the remaining principal in one single payment. When you foreclose an IDFC loan, the agreement ends completely. You wipe out all future interest charges immediately.

A part-prepayment is different. You pay a lump sum toward your principal while keeping the loan open. Part-prepayment either lowers your monthly EMI or shortens your remaining tenure. Your account remains active, and monthly bank debits continue.

Full ForeclosureComplete Termination

You pay 100% of the unpaid balance and broken-period interest. The bank cancels your NACH mandate and releases all collateral. They issue an official No Dues Certificate and mark the loan Closed on CIBIL.

Part-PrepaymentTenure or EMI Reduction

You make a partial payment to lower your balance. The loan stays open. The bank recalculates your interest on the smaller balance. Your monthly auto-debits continue as usual.

Facing Severe Hardship? If you cannot afford full 100% foreclosure payment, explore the master personal loan settlement process or read our dedicated IDFC FIRST Bank loan settlement guide to negotiate a structured 50% to 75% waiver.

02. IDFC Foreclosure Charges by Loan Category

Foreclosure fees at IDFC FIRST Bank depend on your specific loan category. The Reserve Bank of India strictly prohibits penalties on floating-rate loans given to individuals.

Standard IDFC Pre-Closure Schedule:
FIRSTmoney Smart Personal Loan:Zero foreclosure charges. You can close this facility early at any point without paying any penalty fees.
Standard Personal Loans:Typically 3% to 5% of the unpaid principal plus 18% GST. Most contracts enforce a lock-in period of 6 to 12 EMIs before early closure is allowed.
Floating-Rate Home Loans:Zero charges for individual borrowers under RBI rules. Lenders cannot impose any prepayment penalty on floating-rate home loans.
Two-Wheeler Loans:5% of principal outstanding plus 18% GST. Part-prepayment is not permitted on two-wheeler loan agreements.
Used Car & Commercial Loans:Typically 5% of the principal balance plus 18% GST, subject to minimum repayment history terms.

03. Step-by-Step Online Foreclosure Protocol

You can complete your loan foreclosure online through IDFC self-service tools. You do not need to visit a physical branch.

Four-Stage Digital Closure Walkthrough:

Step 1: Open the Mobile App: Log in to the IDFC FIRST Bank mobile app. Tap the Loans tab on your dashboard. Choose your active loan account.

Step 2: Request Foreclosure Quote: Select the Foreclose or Pre-closure option under loan services. If your loan has zero charges like FIRSTmoney, the app displays Foreclose with 0 Charges.

Step 3: Direct Portal Alternative: If the mobile app shows an error, open quickpay.partnerportal.idfcfirst.bank.in/loan-closure-portal in your browser. Enter your registered mobile number and loan ID to fetch your quote.

Step 4: Remit Full Balance: Pay the exact quoted balance via NetBanking, debit card, or UPI. Save the payment receipt and transaction reference number immediately.

04. The 7-Day Pre-EMI NACH Double-Debit Trap

Many borrowers face unexpected EMI debits days after foreclosing an IDFC loan. This happens because of automated National Automated Clearing House (NACH) presentation schedules.

Banks send automated debit instructions to clearing houses 5 to 7 days before your EMI date. Once sent, the automated cycle cannot be cancelled online.

How to Avoid Duplicate Deductions:
  • Never pay foreclosure dues within 7 days of your EMI date. The safest window is 2 to 3 days right after an EMI clears successfully.
  • Right after paying, visit your bank branch. Submit a written stop-payment letter for the IDFC NACH mandate.
  • If the bank debits an EMI after full foreclosure, raise a complaint with payment proof. The bank must refund excess funds within 7 to 10 working days.

05. Recovering Unexpired Bundled Insurance

When sanctioning loans, lenders often bundle single-premium loan protection insurance into the principal. Closing the loan early ends the risk cover. You are entitled to a cash refund.

Under Insurance Regulatory and Development Authority of India (IRDAI) rules, policyholders can claim a pro-rata surrender refund for the unexpired term.

Steps to Claim Your Premium Refund:
  1. Check your loan sanction letter to find the insurance company name (such as ICICI Lombard or Kotak Life).
  2. Download your official IDFC No Dues Certificate showing the early closure date.
  3. Submit a surrender request directly to the insurer with your NDC and policy paper.
  4. The insurance company calculates your pro-rata refund and credits your bank account within 15 working days.

06. How to Audit Your IDFC Foreclosure Quote

Always request an official Foreclosure Statement in PDF before paying. Never pay figures quoted over phone calls. Review every single line item carefully.

The Foreclosure Calculation Formula:

Total Payable = Principal Outstanding + Broken-Period Interest + Contractual Foreclosure Fee + 18% GST on Fee - Excess Advance Balance

  • Principal Outstanding: The actual unpaid loan balance after your last cleared EMI.
  • Broken-Period Interest: Simple interest accrued daily from your last EMI date to the date of foreclosure payment.
  • Foreclosure Charges: Applicable percentage only if your contract is a fixed-rate facility outside RBI exemption rules.
  • Validity Date: Every foreclosure statement has an expiration date. If you pay after this date, per-day interest adds up and leaves an unpaid balance.
Audit Your Numbers: Use our free Loan Settlement Calculator to estimate principal balances, compare full repayment vs waiver ranges, and plan your payoff.

07. Procuring Your Official NOC & RTO Form 35

A loan is never officially closed until you hold the bank No Objection Certificate (NOC) or No Dues Certificate (NDC). This document confirms you owe zero rupees.

Unsecured Personal Loans: You can download your NDC PDF directly in the IDFC app under Closed Loans within 72 hours of payment clearing.

Two-Wheeler & Car Loans: The bank sends two signed copies of RTO Form 35 with the physical NOC by registered post. Submit these to your local RTO to remove bank hypothecation from your RC.

Secured Home Loans & LAP: Under RBI Circular RBI/2023-24/60, the bank must return all original property deeds within 30 days of loan closure. If they delay beyond 30 days, the bank must pay you ₹5,000 for each day of delay.

08. Bureau Updation & ₹100/Day Delay Penalty

After foreclosure, IDFC FIRST Bank must update all credit bureaus: CIBIL, Experian, Equifax, and CRIF High Mark. Your loan remark must read Closed, not Settled or Written-Off.

Check your credit report 30 to 45 days after receiving your NDC. If the loan still shows active, file an online dispute on the CIBIL portal with your NDC copy.

RBI Mandated Dispute Compensation:

Under RBI Circular RBI/2023-24/72, credit bureaus and banks have 30 calendar days to resolve dispute requests. If they fail to fix your status within 30 days, they must pay you ₹100 for every calendar day of delay directly into your bank account.

09. Statutory Grievance Portals & RBI Contacts

If IDFC FIRST Bank delays your No Dues Certificate, withholds property deeds, or levies illegal foreclosure charges on a floating-rate loan, escalate through official channels:

Official Redressal Channels:

1. IDFC Principal Nodal Officer: Submit an internal complaint with your loan account number and payment proof through the official grievance portal or email the Principal Nodal Officer directly.

2. RBI CMS Portal: If the bank fails to resolve your grievance within 30 days, file an online complaint at cms.rbi.org.in or dial toll-free helpline 14448 under the Reserve Bank Integrated Ombudsman Scheme.

3. National Consumer Helpline: Register a consumer grievance regarding deficiency in banking service at consumerhelpline.gov.in or call 1915.

4. e-Jagriti Consumer Court: For cases involving withheld title deeds or delayed compensation, file an online consumer case through e-jagriti.gov.in.

10. IDFC Loan Foreclosure FAQs

Verified statutory answers regarding IDFC loan foreclosure fees, online portal steps, NACH cancellation, and RBI compensation rules.

What are the foreclosure charges for an IDFC FIRST Bank personal loan?
Charges depend on your exact loan product. For the FIRSTmoney smart personal loan, IDFC FIRST Bank charges zero foreclosure fees. For traditional personal loans, charges are usually 3% to 5% of the unpaid principal plus 18% GST. Check your sanction letter for any 6 to 12 month lock-in period.
Can IDFC FIRST Bank charge foreclosure fees on floating rate home loans?
No. The Reserve Bank of India bans all prepayment penalties on floating-rate term loans. This rule applies to all individual borrowers taking loans for non-business purposes.
How can I foreclose my IDFC loan online through the mobile app?
Log in to the IDFC FIRST Bank mobile app. Tap the Loans tab on your screen. Select your active loan account. Click Foreclose or Loan Closure. Check the final balance and broken-period interest. Complete the payment through UPI or NetBanking.
What is the QuickPay link for IDFC loan pre-closure?
You can use the official closure portal directly at quickpay.partnerportal.idfcfirst.bank.in/loan-closure-portal. Enter your registered mobile number and loan ID. The portal generates your real-time foreclosure balance quote.
Why did IDFC debit an EMI even after I foreclosed my loan?
Banks send automated NACH debit files to clearing houses 5 to 7 days before your EMI date. Once sent, the file cannot be stopped online. To avoid double debits, submit a written stop-mandate request to your bank branch right after paying.
Can I claim a refund on insurance bundled with my IDFC loan upon foreclosure?
Yes. Lenders often add single-premium credit life insurance to loans. When you close the loan early, risk cover ends. Under IRDAI rules, you can surrender the policy. Send your loan NOC to the insurer to get a pro-rata cash refund.
How many days does IDFC take to issue the No Objection Certificate (NOC)?
You can download digital NOCs in the mobile app within 72 hours of full payment. For two-wheeler and car loans, physical NOC copies and RTO Form 35 arrive by post within 10 to 14 working days.
What compensation does RBI mandate if IDFC delays returning property documents?
Under RBI Circular RBI/2023-24/60, lenders must return original property deeds within 30 days of loan closure. If the bank causes any delay beyond 30 days, they must pay you ₹5,000 for each day of delay.
How long does it take for an IDFC loan foreclosure to reflect on CIBIL?
Banks update credit bureaus within 30 to 45 days. Under RBI Circular RBI/2023-24/72, credit bureaus must fix dispute errors within 30 days. If they fail, they must pay you ₹100 compensation for each day of delay.
What is broken-period interest in an IDFC foreclosure statement?
Broken-period interest is simple interest charged on your unpaid principal balance. It counts from your last EMI debit date to the exact day your foreclosure payment reaches the bank.

Find this content helpful?

If this guide has helped you navigate your settlement journey, consider showing some support to keep this platform running.