WARNING: THIS IS NOT LEGAL ADVICE. THIS IS SURVIVAL ADVICE BASED ON REAL BORROWER EXPERIENCE.
UPDATED: SEPTEMBER 2026
Indian Bank Loan Settlement Process & OTS Rules in India
How to Settle Indian Bank & Allahabad Bank Debt
After its merger with Allahabad Bank, Indian Bank operates more than 5,700 branches. Learn how to settle personal loans and card dues through the eOTS portal, protect your pension from Section 171 banker's lien, and get a binding compromise order at Lok Adalat.
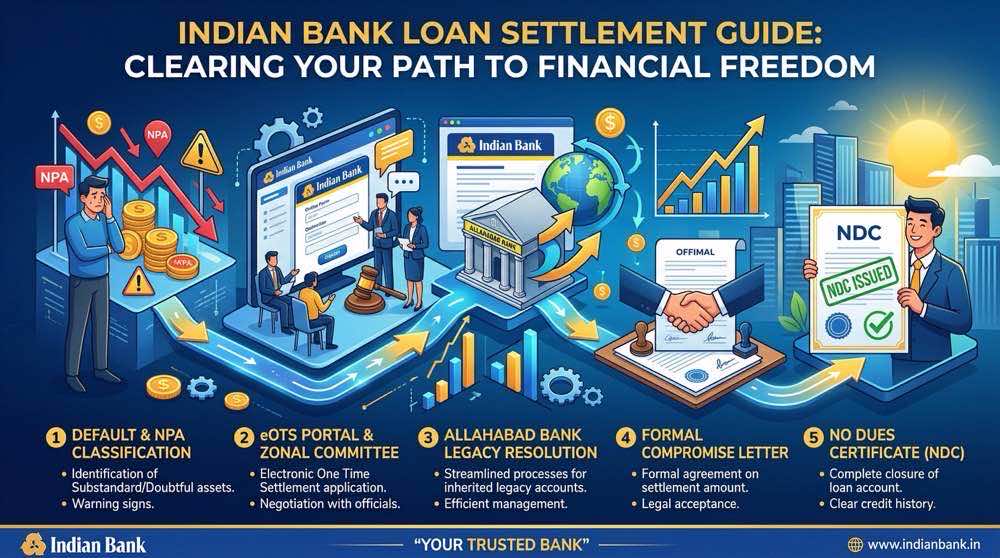
Figure 1: Official settlement hierarchy and Ind Samadhan compromise procedure across Indian Bank branches and recovery offices.
Quick Answer Summary
You can settle Indian Bank and old Allahabad Bank debts through branch recovery teams, Circle Recovery Wings (CRW), or the online eOTS portal for loans up to ₹10 Lakh. Delinquent unsecured personal loans and credit cards can be settled for 40% to 60% of your principal dues with a 100% waiver on late fees and interest. Under Section 171 banker's lien, the bank can freeze linked accounts, so move salary and pension funds to a different bank before you default. Settling at National Lok Adalat gives you a binding order under Section 21 of the Legal Services Authorities Act. This ends all Section 138 cheque bounce and Section 25 NACH court cases for good.
1. Indian Bank & Allahabad Bank Amalgamation Landscape
Indian Bank was established in 1907 with its head office in Chennai. On April 1, 2020, Allahabad Bank merged into Indian Bank. This merger created a massive public sector bank with over 5,700 branches across India.
This merger changed account details for many borrowers. Old Allahabad Bank loans were moved into Indian Bank's computer system. Loan numbers changed, and branch IFSC codes changed to the IDIB000... series. Many accounts were assigned to regional Circle Recovery Wings.
Even with these changes, Indian Bank offers clear settlement options. You can use the online eOTS portal or talk to the Zonal Settlement Committee to settle bad personal loans, credit cards, or MSME debts at a major discount.
Public sector banks cannot write off loans carelessly. Because they handle public money, Indian Bank must follow strict government rules:
RBI Master Directions on Compromise Settlements (2023)
Under RBI circular RBI/2023-24/40, Indian Bank has an approved policy for compromise settlements. The bank can legally reduce loan principal and waive interest on Non-Performing Assets (NPAs) without a court order.
Central Vigilance Commission (CVC) & Staff Accountability
Bank officers face audits by the CVC. Before approving any discount on your loan, officers must check for staff lapses. You must submit genuine proof of financial hardship. This gives officers the legal justification they need to approve your settlement.
Exclusion of Willful Defaulters & Fraud Accounts
Borrowers tagged as 'Willful Defaulters' or facing police investigations for fraud cannot get an OTS settlement. They must face legal action.
3. Internal Recovery Desks: Branch to SAMB
Indian Bank divides bad loans into four levels based on the loan amount:
Branch Level (Up to ₹5 Lakh)
The Branch Manager handles early defaults. They can remove late penalties or grant extra time. But branch managers have little power to reduce your principal loan balance.
Circle Recovery Wings (CRW) (₹5L - ₹50L)
Circle recovery teams led by Chief Managers and AGMs manage medium-size loans. They review and approve standard OTS settlement requests.
Dedicated SAMB offices manage large corporate and high-value NPA loans under the direct control of the Head Office in Chennai.
4. The eOTS Digital Settlement Portal
Indian Bank created the eOTS (Electronic One Time Settlement) system to make settlements fast and transparent. You can access it through the bank's website or the IndOASIS mobile app:
Core Eligibility & Operating Rules for eOTS:
Loan Limit: Open to borrowers whose total loan balance across the bank is up to ₹10.00 Lakh.
Account Status: The loan must be classified as Doubtful (D1, D2, D3) or Loss under RBI rules.
Fast Online Check: Enter your mobile number, CIF, or loan account number to see a pre-calculated settlement offer.
Instant Letter: You can accept the offer online and download an in-principle approval letter without visiting the branch.
5. Resolving Legacy Allahabad Bank Debt
If you took your loan from Allahabad Bank before April 2020, follow these steps to settle smoothly:
1. Check New Account Details:
Old Allahabad Bank account numbers are now mapped to new Indian Bank CBS accounts. Ask the branch for an Account Mapping Certificate before paying any money.
2. Track Original Documents:
For home or business loans, original property deeds were kept in old Allahabad Bank vaults. Make sure the current branch has your physical property papers before paying the final settlement installment.
3. Check Administrative Office:
While Indian Bank's head office is in Chennai, many old Allahabad Bank files in North and East India are managed by Zonal Offices in Kolkata, Lucknow, or Allahabad.
6. Loan Products Breakdown & Realistic Haircuts
Settlement discounts depend on your loan type and collateral:
Under Section 171 of the Indian Contract Act, 1872, Indian Bank can freeze any deposits held under your CIF number.
Crucial Defenses Against Section 171 Liens:
Statutory Pension Protection: Under Section 60(1)(g) of the Code of Civil Procedure (CPC) and Supreme Court rulings, banks cannot touch government pensions or essential living wages.
Joint Accounts: Money in a joint account where you are only a secondary holder cannot be attached for your personal loan without written permission.
Move Your Funds Early: Before you default, move your salary, savings, and operating money to an account in a different bank.
⚡ Empirical CalculatorUNSECURED NPA
Indian Bank Settlement & Haircut Estimator
Calculate realistic One-Time Settlement (OTS) compromise ranges based on Indian Bank e-OTS circulars and SAMB recovery guidelines.
Unsecured retail advance. Delinquent accounts past 180 DPD qualify for 100% penal interest waiver and up to 55% principal reduction.
₹3,50,000
₹25,000₹25,00,000₹50,00,000
Target Settlement Offer:50%–65% Haircut
Realistic Settlement Range:₹1,22,500 – ₹1,75,000
Estimated Debt Forgiven:₹1,75,000 – ₹2,27,500
*100% penal interest and late bounce charges waived under Indian Bank e-OTS.
⚠️
Indian Bank Recovery Caveat:Branch managers operate under strict CVC compromise caps. Submit applications through Zonal SAMB desks or register for National Lok Adalat sessions.
9. Step-by-Step OTS Negotiation Workflow
Follow these five steps to settle your debt with Indian Bank:
Step 1: Ledger Statement Analysis
Get a printed statement of account from your branch. Separate your original principal balance from unapplied interest and penal charges.
Step 2: Submission of Hardship Dossier
Write an OTS application to your Branch Manager and Circle Recovery Wing. Attach clear proof of financial distress, such as medical bills, a job loss letter, or business closure records.
Step 3: Verification by Circle Recovery Wing
The Circle Recovery Wing checks that you have no extra property to clear the debt. If you have no other assets, they recommend your file for an OTS write-off.
Step 4: Formal Sanction Letter Issuance
Indian Bank issues an official OTS Sanction Letter on bank letterhead. An authorized AGM or DGM signs and stamps it. It states your exact settlement amount, payment dates, and validity terms.
Step 5: Direct Remittance & NDC Dispatch
Pay the settlement money directly into your loan account using RTGS, NEFT, or at the branch counter. Collect your No Dues Certificate within 30 days.
10. Calculating Realistic Compromise Haircuts
When an Indian Bank loan defaults, extra fees and penalties add up fast. After two or three years of missed payments, a ₹5,00,000 loan can grow past ₹10,00,000.
Understanding Indian Bank's accounting rules helps you get a fair deal:
Penal Interest & Inspection Charges: 100% waiver of penalty charges is standard in public sector bank settlements.
Unapplied Interest: Under RBI rules on income recognition (IRAC), banks stop counting interest on bad loans as income. Waiving this unapplied interest costs the bank zero cash.
Principal Sacrifice: For personal loans unpaid for over a year (Doubtful status), Indian Bank usually accepts 40% to 55% of the pure principal balance in a lump-sum payment.
11. National Lok Adalat Fast-Track Route
If Indian Bank filed a Section 138 cheque bounce or Section 25 NACH case against you, settle through the National Lok Adalat:
Civil Court Decree Status: An award passed at Lok Adalat has the force of a civil court decree under Section 21 of the Legal Services Authorities Act, 1987. The bank cannot appeal against it.
Quashing Criminal Proceedings: The settlement order formally closes and withdraws all pending Section 138 cheque bounce cases.
Pre-Delegated Haircut Mandates: Indian Bank officers at Lok Adalat benches have pre-approved powers to grant discounts on the spot.
Tier 1
Home Branch Manager & 24x7 Customer Helpline
SLA: 7 Working Days
Frontline Branch & Centralized Grievance Redressal System (CGRS)
Initial submission of hardship letter, factual ledger reconciliation, and branch-level service issues.
Use this verified legal template to file a formal record with the Principal Nodal Officer before escalating to the RBI Ombudsman:
Subject: URGENT: Illegal Recovery Harassment & Formal Compromise Settlement Submission - Loan A/C [Your Account Number]

To:
The Principal Nodal Officer, Indian Bank (nodalofficer@indianbank.bank.in)
Copy: General Manager, Customer Service Cell, Head Office Chennai

Respected Sir/Madam,

I am writing regarding my Loan Account [Your Account Number] at Indian Bank [Branch Name / Legacy Allahabad Bank Branch]. Due to involuntary financial distress [state reason: job loss / medical crisis / business loss], I am unable to maintain regular EMIs.

I have formally requested an amicable One-Time Settlement (OTS) under the bank's compromise policies. However, recovery agents representing the bank have engaged in coercive tactics, including calling outside permitted hours (08:00 to 19:00) and threatening my family, in direct violation of the RBI Master Direction on Fair Practices Code.

I formally request:
1. Immediate cessation of third-party harassment and dispatch of calls/visits only through authorized bank officials.
2. Table discussion of my formal OTS settlement proposal for a full and final compromise.
3. Provision of a comprehensive statement of account delineating pure principal from penal charges.

Sincerely,
[Your Full Name]
[Registered Mobile Number]
[Registered Communication Address]
13. Securing the No Dues Certificate (NDC): Verification Criteria
Your settlement is not legally complete until you hold an unconditional No Dues Certificate (NDC) or No Objection Certificate (NOC) on Indian Bank letterhead.
Critical Verification Points:
Check that both the old Allahabad Bank account number and new Indian Bank account number are clearly printed.
Confirm that all court cases, Section 138 complaints, and SARFAESI actions are marked as withdrawn.
Confirm that the certificate frees all personal and corporate guarantors from future claims.
30-Day Mandatory Release (RBI/2023-24/60): Under RBI directions on property documents, Indian Bank must give you your NDC and return all original title deeds within 30 days of final payment. If the bank delays beyond 30 days, they must pay you ₹5,000 for each day of delay.
14. Post-Settlement CIBIL Restoration Plan
After you settle your loan, Indian Bank reports the account as 'Settled' or 'Post-Write-Off Settled' to CIBIL and other bureaus. This stops recovery actions, but your credit score will drop by 50 to 90 points temporarily.
You can rebuild your credit score above 750 within 18 to 24 months with these three steps:
1. Fixed Deposit Secured Card
Open a fixed deposit of ₹20,000 in another bank and take a secured credit card.
2. Strict 20% Utilization
Keep monthly spending below 20% to 25% of your card limit. Always pay the full statement balance before the due date.
3. Credit Bureau Verification
Download your updated CIBIL report after 90 days to verify that your Indian Bank account shows a ₹0 balance.
15. Frequently Asked Questions: Indian Bank Settlements
How do I settle an old loan taken from Allahabad Bank before the merger?▼
Allahabad Bank merged into Indian Bank on April 1, 2020. All old accounts are now part of Indian Bank with new IFSC codes (starting with IDIB000...). You can apply for a One-Time Settlement (OTS) directly at your local Indian Bank branch, Circle Recovery Wings, or through the online eOTS portal.
What is the Indian Bank eOTS digital settlement scheme?▼
Indian Bank runs a digital settlement system called eOTS on its website and the IndOASIS app. If your total loan is up to ₹10 Lakh and marked as Doubtful or Loss, you can see a pre-approved settlement offer online. You can settle your loan digitally without visiting the branch.
What percentage waiver is realistic on an unsecured Indian Bank personal loan?▼
For unsecured personal loans (like IB Clean Loans) unpaid for over 6 to 12 months, you can usually negotiate a 40% to 60% discount on your principal balance. The bank also waives 100% of all penalty interest and late charges.
Can Indian Bank freeze my pension or salary account under Section 171?▼
Under Section 171 of the Indian Contract Act, 1872, the bank can freeze funds in accounts linked to your CIF number. But court rulings and civil service rules protect government pensions and essential living wages from being seized. To stay safe, move your living funds to an account in another bank before you default.
What happens if I default on an Indian Bank credit card?▼
Credit card interest can reach 30% to 42% per year. After 90 days of missed payments, your card becomes an NPA. You can settle the card through the Zonal Credit Card Desk. The bank routinely waives 100% of all interest charges and offers a 45% to 60% discount on the principal balance.
How does Indian Bank handle settlements in National Lok Adalat?▼
Indian Bank regularly joins National Lok Adalat camps across the country. When you agree to settle at Lok Adalat, the judge issues an order under Section 21 of the Legal Services Authorities Act, 1987. This order has the power of a civil court decree and ends all Section 138 cheque bounce or Section 25 NACH cases.
Who approves loan settlement proposals above ₹10 Lakh at Indian Bank?▼
Settlements over ₹10 Lakh are reviewed by Circle Recovery Wings (CRW) and Zonal Committees led by a Deputy General Manager (DGM). For large loans over ₹1 Crore, the approval comes from the Head Office Stressed Asset Management Committee in Chennai.
What should I do if third-party recovery agents harass me in my home or office?▼
Save all call recordings and messages. Demand to see the agent's ID card and bank authorization letter. If agents harass or intimidate you, file a police complaint under Section 351 of Bharatiya Nyaya Sanhita (BNS). You should also email Indian Bank's Principal Nodal Officer at nodalofficer@indianbank.bank.in.
How long does Indian Bank take to issue the No Dues Certificate (NDC)?▼
Under RBI circular RBI/2023-24/60, Indian Bank must give you the No Dues Certificate within 30 days of your final payment. They must also return your property papers. If the bank takes longer than 30 days, they must pay you ₹5,000 for each day of delay.
How does an Indian Bank settlement reflect on my CIBIL credit report?▼
Indian Bank reports the loan as 'Settled' to credit bureaus. This drops your credit score in the short term. However, you can rebuild it. Get a secured credit card against a small fixed deposit and pay all bills on time. Your credit score can rise above 750 within 18 to 24 months.
Find this content helpful?
If this guide has helped you navigate your settlement journey, consider showing some support to keep this platform running.