WARNING: THIS IS NOT LEGAL ADVICE. THIS IS SURVIVAL ADVICE BASED ON REAL BORROWER EXPERIENCE.
UPDATED: SEPTEMBER 2026

IDFC FIRST Bank Loan Settlement Process & Digital OTS Rules

How to Settle IDFC Personal, Card & Consumer EMI Debt

If you have unpaid IDFC FIRST Bank personal loans, credit cards, or consumer EMIs, help is available. This guide explains how to handle automated collection calls, defend against Section 25 PSS notices, and negotiate a One-Time Settlement (OTS) for 40% to 65% less.

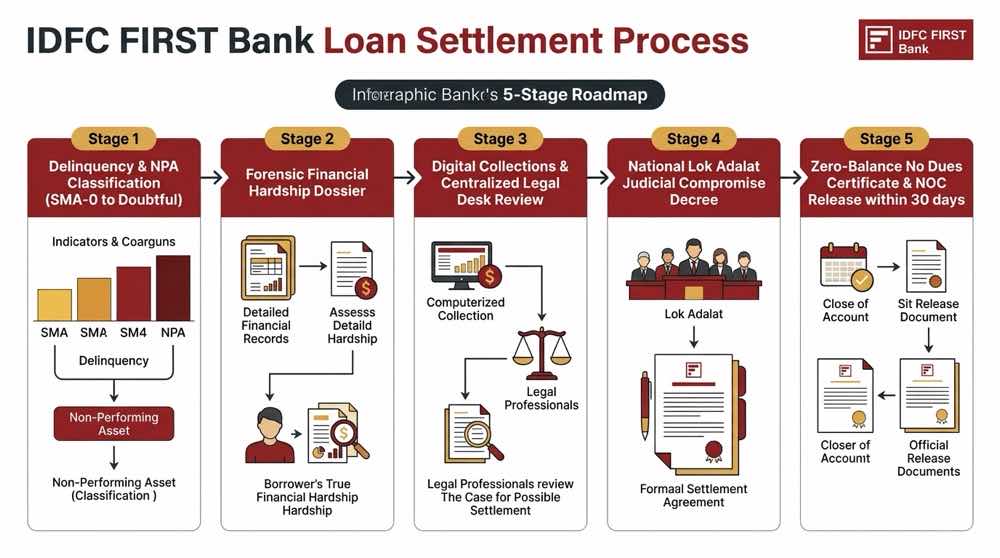
IDFC FIRST Bank Loan Settlement Process, Digital Escalation and OTS Workflow

Figure 1: Official settlement hierarchy and digital OTS compromise procedure across IDFC FIRST Bank operations.

Quick Answer Summary

IDFC FIRST Bank resolves defaulted retail debt through digital recovery teams and National Lok Adalat benches. Section 25 PSS Act notices are issued when auto-debits bounce, but you can settle them without going to jail. For personal loans, credit cards, and consumer EMIs overdue past 180 days, managers can approve 40% to 65% waivers on the principal. All late fees and penal interest can be waived. Always pay directly into your IDFC loan account and get an official No Dues Certificate within 30 days under RBI rules.

⚡ Empirical CalculatorUNSECURED NPA

IDFC FIRST Bank Settlement & Haircut Estimator

Calculate realistic One-Time Settlement (OTS) compromise ranges based on IDFC FIRST Bank recovery guidelines and NPA provisioning metrics.

Unsecured retail advance. Delinquent accounts past 180 DPD qualify for 100% penal interest waiver and up to 60% principal reduction.

₹3,50,000
₹30,000₹25,00,000₹50,00,000
Target Settlement Offer:50%–65% Haircut
Realistic Settlement Range:₹1,22,500 – ₹1,75,000
Estimated Debt Forgiven:₹1,75,000 – ₹2,27,500
*100% penal charges and bounce fees waived under IDFC FIRST OTS rules.
⚠️
IDFC FIRST Recovery Caveat:IDFC FIRST utilizes aggressive digital recovery agencies initially. Once aged past 180 DPD, direct negotiation with their central Stressed Assets Desk yields optimal haircuts.

1. IDFC FIRST Institutional Reality: Fintech Speed & Digital Desks

IDFC FIRST Bank formed through the merger of IDFC Bank and Capital First. It runs a fast digital lending platform across India. The bank funds consumer electronics, mobile phones, and instant personal loans online.

When borrowers face financial hardship and miss payments, recovery is also digital. IDFC FIRST Bank does not rely on branch visits. Instead, its systems send accounts into automated digital queues. The system sends phone calls, retries e-NACH auto-debits, and issues automated legal notices under Section 25 of the PSS Act.

If recovery callers call outside permitted hours or harass your family, you can take action. Follow our step-by-step guide to file an RBI recovery agent harassment complaint.

The Commercial Agility Advantage

IDFC FIRST is a private bank, so credit managers have wide power to approve discounts. They do not face government audit scrutiny. When an account is clearly past recovery, managers can approve deep waivers up to 65% to remove bad debt from their books.

2. Capital First Legacy & Consumer Durable Books

Many defaulted loans at IDFC FIRST Bank come from its Capital First business. These are no-cost EMI loans that financed TVs, phones, laptops, and home appliances.

Small-Ticket Economic Realities

For loans between ₹15,000 and ₹1,50,000, the bank has no physical collateral. Taking legal action costs more than the unpaid loan amount. Once these accounts pass 180 to 365 days of delay, managers routinely accept 40% to 50% one-time payments to close the file.

3. IDFC Digital OTS Settlement Formula: How Waivers Are Calculated

IDFC FIRST Bank decides settlement discounts based on how long the loan is unpaid and your financial hardship:

Delinquency StageDPD AgingRecovery PolicyTypical Haircut Band
Early Default (SMA-2)60 to 90 daysEMI Rescheduling / RestructuringBounce Fee Waiver Only
NPA (Sub-Standard)90 to 180 days100% Principal + Part Interest Waiver20% to 35% Waiver
Doubtful (D1/D2)180 to 365+ daysAggressive Principal Haircut (Unsecured)40% to 55% Waiver
Loss / Written-OffBeyond 2 yearsDeep Lump-Sum Compromise55% to 65%+ Waiver

To check your loan balance against bank waiver bands, use our interactive loan settlement calculator to estimate realistic one-time settlement figures.

4. National Lok Adalat: Judicial Compromise Decrees

IDFC FIRST Bank regularly sends unpaid retail loans to quarterly National Lok Adalat sessions. For borrowers, this is the safest place to settle debt.

Absolute Statutory Protection

An agreement signed at Lok Adalat acts as a final court decree under Section 21 of the Legal Services Authorities Act, 1987. No appeal can be filed against it. Settling at Lok Adalat closes all pending Section 25 PSS cases and stops future legal claims by the bank.

5. Personal Loans & Digital Lines: Section 171 Banker's Lien

IDFC FIRST Bank issues many personal loans online. When you miss payments, the bank uses automated tools to recover money.

Automated Section 171 Banker's Lien

Under Section 171 of the Indian Contract Act, 1872, the bank has a right of lien over your bank accounts. If you default on an IDFC loan or card, the bank can freeze any savings account, salary account, or fixed deposit under your Customer ID.

To protect your monthly living expenses:

  • Open a new savings account with a different bank before your loan is 60 days overdue.
  • Move your salary credit to this new external account right away.
  • Never keep emergency savings in an IDFC FIRST account while negotiating a settlement.

To learn your legal rights and view dispute letters, read our guide on the personal loan settlement process. If you have funds to pay in full and want to avoid credit damage, read our IDFC loan foreclosure guide.

6. IDFC FIRST Credit Cards: Dynamic APR Defense

IDFC FIRST credit cards charge annual interest rates between 9% and 42%. When you miss card payments, finance charges, late fees, and 18% GST add up fast.

Principal Dissection Negotiation Protocol

When you negotiate a card settlement, ask for an itemized statement. Deduct all finance charges, late fees, and taxes to find your actual principal spend. IDFC managers can waive 100% of accumulated interest. You can then settle the actual principal at a 35% to 50% discount.

For notice responses and settlement checklists, see our master guide on credit card debt settlement rules.

7. Centralized OTS Sanction Verification, Direct CBS Remittance & 30-Day NDC SLA

Recovery agents often send fake settlement offers to collect quick money. Never pay based on a phone call or plain email. Always insist on a formal settlement letter from IDFC FIRST Bank on official letterhead with a clear reference number.

Sanction Audit & Remittance Safeguards

  • ● Legal Case Dismissal: Make sure the letter states that all Section 25 PSS cases, Section 138 notices, and arbitration claims will be withdrawn.
  • ● Direct Bank Account Payment: Pay only by NEFT or RTGS directly into your IDFC loan account. Use the official bank IFSC code IDFB0.... You can also pay via Demand Draft favoring "IDFC FIRST Bank A/C [Your Loan Number]". Never hand cash to collection agents.
  • ● 30-Day NDC Rule: Under RBI Circular RBI/2023-24/60, IDFC FIRST Bank must issue your No Dues Certificate and return all loan security within 30 days. If the bank delays, it must pay you ₹5,000 for each day of delay.
  • ● Credit Score Update: Check your CIBIL report 45 days after payment. The loan should show as "Settled" with a zero balance. If you want to clear this mark later, follow our guide on converting CIBIL settled status to closed. Otherwise, you can rebuild your score over 18 to 24 months with a secured credit card.
Tier 1Customer Care & Branch Helpdesk
SLA: 7 Working Days

Authority: Frontline Digital Grievance Support

Contact: Toll-free: 1800 10 888 | Email: banker@idfcfirstbank.com

Jurisdiction: Handles account statement disputes, payment allocation mismatches, and initial compromise queries.

Tier 2Regional Nodal Officer (RNO)
SLA: 7 - 10 Working Days

Authority: Grievance Redressal Desk

Contact: Phone: 022-41652700 | Email: rno@idfcfirstbank.com / nodaldesk@idfcfirstbank.com

Jurisdiction: Handles repeated automated calling complaints, Sec 25 PSS dispute notices, and stalled OTS requests.

Tier 3Principal Nodal Officer (PNO)
SLA: 15 Working Days

Authority: Mr. Vipul Raj (Principal Nodal Officer)

Contact: Gigaplex Raheja Mindspace IT-5, Bldg 9, 17th Fl, Airoli, Navi Mumbai - 400708 | Phone: 1800 209 9771 | Email: pno@idfcfirstbank.com

Jurisdiction: Senior-most internal authority for third-party collection harassment, unlawful liens, and final OTS approvals.

Tier 4RBI Banking Ombudsman (Statutory Regulator)
SLA: 30 Days Post-PNO

Authority: Reserve Bank of India Consumer Education and Protection Cell

Contact: Portal: cms.rbi.org.in | Toll-Free: 14448 | Postal: CRPC, RBI, 4th Floor, Sector 17, Chandigarh - 160017

Jurisdiction: Binding statutory adjudication under the Reserve Bank - Integrated Ombudsman Scheme, 2021.

📝

1-Click IDFC FIRST PNO Harassment & OTS Template

Personalize the bracketed variables and email directly to pno@idfcfirstbank.com.

Subject: URGENT: Digital Collection Harassment & Formal OTS Settlement Submission - Loan A/C [Your Account Number]

To:
The Principal Nodal Officer,
IDFC FIRST Bank Ltd, Gigaplex Raheja Mindspace, Airoli,
Email: pno@idfcfirstbank.com

Cc:
Regional Nodal Officer: rno@idfcfirstbank.com

Dear Sir,

I am writing regarding my Loan/Credit Card Account Number [Your Account Number] registered with IDFC FIRST Bank.

Due to unforeseen severe financial hardship resulting from [State Reason: e.g., Catastrophic Medical Event / Sudden Loss of Job / Business Involuntary Shutdown], I have suffered an acute failure in regular EMI repayment capability. I have formally indicated my readiness to execute a legitimate One-Time Settlement (OTS) compromise reflecting my realistic financial means.

However, collection agencies and automated systems representing IDFC FIRST Bank have violated RBI fair practice codes:
1. Automated dialers bombarding my telephone multiple times per hour outside the 8:00 AM to 7:00 PM window.
2. Sending threatening and coercive messages referencing Section 25 PSS Act via WhatsApp and SMS without due process.
3. Contacting non-borrower references and workplace associates in clear breach of borrower privacy rights.

Please note that such actions violate RBI guidelines on digital recovery and constitute an offense under Section 351 of the Bharatiya Nyaya Sanhita (BNS) for criminal intimidation.

I hereby formally demand:
1. Immediate cessation of all auto-dialer calls, WhatsApp threats, and third-party contact.
2. Official consideration of my compromise settlement proposal under IDFC FIRST Bank settlement guidelines.
3. All future communications sent exclusively in writing to my registered email address.

Yours faithfully,
[Your Name]
[Contact Number]
[City]

8. Frequently Asked Questions (IDFC FIRST Bank Debt Settlement)

How does loan settlement work with IDFC FIRST Bank?▼
IDFC FIRST Bank settles unpaid retail loans through central digital recovery desks. Borrowers facing genuine financial hardship can negotiate One-Time Settlements (OTS) past 90 to 180 days of delay. You can secure 40% to 65% waivers on personal loans, credit cards, and consumer EMIs.
Why does IDFC FIRST Bank send Section 25 PSS Act legal notices?▼
IDFC FIRST Bank uses automated e-NACH mandates. When an auto-debit bounces, its legal system sends notices under Section 25 of the Payment and Settlement Systems Act, 2007. While Section 25 is similar to cheque bounce, it is a bailable offense. You can close it easily by reaching a settlement.
Can IDFC FIRST Bank freeze my savings account under Section 171?▼
Yes. Under Section 171 of the Indian Contract Act, IDFC FIRST Bank can place a lien or freeze on any savings, salary, or fixed deposit account under the same Customer ID. Borrowers facing default should move their salary to an external bank before missing payments.
Can I settle small-ticket consumer durable loans (electronics, smartphones)?▼
Yes. Consumer durable loans are unsecured debts with no physical collateral. When these loans pass 180 days of delay, managers often settle them for 40% to 50% lump-sum payments because legal recovery costs more than the loan balance.
What interest rates apply when IDFC FIRST credit cards default?▼
IDFC FIRST credit cards charge annual interest between 9% and 42%. In a settlement, request a full statement, demand 100% waiver of finance charges and late fees, and settle the actual principal spent at a 35% to 50% discount.
How does National Lok Adalat help in settling IDFC FIRST Bank debt?▼
National Lok Adalat is a court-backed forum where bank officers issue legal compromise orders under Section 21 of the Legal Services Authorities Act. An order signed at Lok Adalat ends all Section 25 PSS cases and stops future collection action.
What should I do if AI calling bots or recovery agents call repeatedly?▼
The RBI Fair Practices Code bans repetitive calling and calls outside 8:00 AM to 7:00 PM. Keep audio recordings and call logs. File a complaint under Section 351 of BNS for criminal intimidation, and email the Principal Nodal Officer at pno@idfcfirstbank.com.
Can IDFC FIRST Bank seize my two-wheeler without prior notice?▼
No. Under Supreme Court orders and RBI rules, lenders cannot take vehicles without a 14-day pre-sale notice and an inventory list. Forcible vehicle seizures on the road by collection agents are illegal.
How long does IDFC FIRST Bank take to issue a No Dues Certificate?▼
Under RBI circular RBI/2023-24/60, IDFC FIRST Bank must issue your No Dues Certificate (NDC) and return original property documents within 30 days of full payment. Any delay entitles you to ₹5,000 compensation per day.
How does settling with IDFC FIRST Bank impact my CIBIL score?▼
The bank reports settled loans to bureaus as 'Settled', which drops your score by 50 to 100 points. You can rebuild your score above 750 within 18 to 24 months by using an FD-backed secured card and paying bills on time.

Official Statutory Resources & Regulatory Portals

RBI & GOVT VERIFIED

Official Indian statutory frameworks, regulatory ombudsman channels, and dispute resolution portals governing IDFC FIRST Bank and borrower rights:

Community Discussion & Case Notes

0 Comments

No comments posted yet. Be the first to share your experience below!

Join the Discussion & Share Your Experience

Have you dealt with this situation or received a notice? Share your questions or experience with other borrowers.

0/500

Find this content helpful?

If this guide has helped you navigate your settlement journey, consider showing some support to keep this platform running.