1. The Private Bank Reality: Provisioning Deadlines & Strict 30%–40% Caps
ICICI Bank handles retail debt defaults commercially based on quarterly capital provisioning rather than lengthy court litigation.
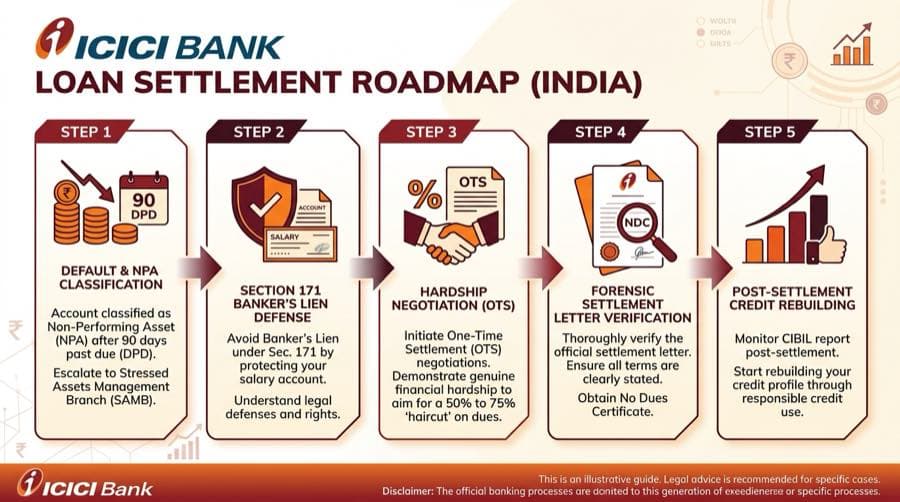
Under Reserve Bank of India (RBI) rules, the longer a loan stays unpaid, the more money ICICI is forced to lock away in an emergency reserve (called “provisioning”). This locked money directly hurts the bank's quarterly profits. However, as of September 2026, ICICI is strictly not offering high waivers. The bank has tightened recovery parameters: its specialized recovery division, the Stressed Assets Management Branch (SAMB), offers strictly 30% to 40% waivers—nothing more than that to close bad debts.
September 2026 Concession Cap:While the final two weeks of March, June, September, and December offer the fastest turnaround times as recovery managers race to meet quarter-end targets, ICICI credit committees maintain a firm policy ceiling: waivers are capped tightly at 30% to 40% maximum, with no higher haircuts approved.
2. The Banker's Lien (Section 171) Trap on ICICI Accounts
The single most dangerous trap when defaulting on an ICICI loan or credit card is keeping money in an ICICI savings, salary, or fixed deposit account.
Under Indian law (Section 171 of the Indian Contract Act, 1872, known as the *Banker's Right of Set-Off*), ICICI has the legal right to pull money from any account you hold with them to pay off your overdue credit card or personal loan without asking you or needing a court order.
Many borrowers wake up on salary day to discover their entire month's paycheck has been wiped out to ₹0, leaving them with no money for groceries or house rent. Reversing this deduction takes months of legal fighting.
Your #1 Survival Step:At least 60 days before your first missed EMI, instruct your office HR to transfer your salary to a completely different public sector bank (such as Punjab National Bank or Bank of Baroda). Cancel all auto-debit mandates and UPI handles linked to your ICICI accounts. Never keep your living money inside ICICI.
3. iMobile Instant Personal Loans: What Happens When You Default
Pre-approved personal loans disbursed through the iMobile Pay app are 100% unsecured digital debts without physical collateral.
When an iMobile loan defaults, collection agencies will bombard you with automated phone calls and threaten legal notices for auto-debit bounces.
The Settlement Reality: Because an iMobile personal loan is 100% unsecured (meaning you did not pledge any house, car, or gold), the bank cannot auction your home or take your belongings. Once the loan is delayed past 6 months (180 days) and reaches SAMB, the bank will negotiate an OTS, but as of September 2026, ICICI is offering only 30% to 40% waivers—nothing more than that (requiring the borrower to repay 60% to 70% of total dues). Do not believe false assurances of 50% to 70% waivers, and do not negotiate with junior tele-callers who offer negligible 5% to 10% concessions.
4. ICICI Credit Card Settlement: How to Defend Against 42%–45% APR Interest
ICICI credit cards-especially the popular Amazon Pay ICICI Card, Coral, Rubyx, and Sapphiro-charge interest rates of 42% to 45% per year plus 18% GST and heavy late fees. If you miss minimum payments for 6 months, your bill can nearly double because of compounding charges rather than your actual shopping spend.
Does defaulting on an Amazon Pay card affect your Amazon account? No! Amazon Pay ICICI cards are issued and managed entirely by ICICI Bank Ltd. Your Amazon shopping account and Prime membership will not be blocked. When negotiating a settlement, demand that 100% of the late fees and finance interest be erased, and settle strictly on your original shopping principal.
ICICI Credit Card Settlement Benchmarks (September 2026):- • Penal Fees & APR Interest: Conceded and adjusted in formal OTS agreements.
- • Overall Waiver Reality: As of September 2026, ICICI is not offering high waivers (such as 50%, 60%, or 70%). The bank is offering strictly only 30% to 40% waivers—nothing more than that on total claimed dues.
- • Payment Schedule: One lump-sum payment or 2 to 3 structured monthly installments backed by an official bank settlement letter.
5. Car & Bike Loan Repossession: The Supreme Court Shield
Under the landmark Supreme Court ruling ICICI Bank Ltd. v. Prakash Kaur (2007), banks and recovery agents are strictly prohibited by law from using force or recovery “musclemen” to seize vehicles from borrowers.
Under Indian motor vehicle laws, even though the vehicle is financed by the bank, you are the legal registered owner. If recovery agents attempt to stop your car on public roads or tow it from your driveway without a court order, they are committing criminal trespass and intimidation.
The Legal Repossession Steps ICICI Must Follow:The bank must send you a 7-day written notice, recovery officers must carry official bank ID cards, they must give you an inventory list of personal items inside the vehicle, and they must give you 14 days to pay before any auction. If your car is auctioned for less than the loan amount, the remaining shortfall becomes an unsecured debt where, under ICICI's September 2026 guidelines, settlement waivers are strictly capped at 30% to 40% maximum.
6. Home Loans & ICICI HFC SARFAESI Defense
Can you get a 50% discount on an ICICI home loan? No. ICICI Bank and its housing subsidiary, ICICI Home Finance (HFC), physically hold your original property papers (Registry / Sale Deed). Under the SARFAESI Act, 2002, if you stop paying, the bank has the legal right to take possession and auction the house.
- Section 13(2) Notice: Gives you 60 days to pay the overdue amount.
- Section 13(3A) Objection: You have the legal right to send an official reply within 15 days explaining your hardship. ICICI is legally required to reply to your letter.
- Sell the House Yourself: Ask ICICI for 90 days to sell the property yourself in the open market. When the bank puts a house in a public e-auction on
ibapi.in, they sell it cheap (20% to 30% below market value), destroying your life savings. Selling it yourself allows you to pay off the bank in full and keep the remaining cash.
The Realistic Relief: While ICICI will not waive the principal on a valuable house, they routinely agree to cancel 100% of accumulated penalty interest and late fees if you agree to regularize your base EMIs.
7. ICICI Gold Loan Default & Section 176 Auction Rules
If you pledged family jewelry for an ICICI Gold Loan and cannot pay the interest, the bank cannot quietly melt or sell your gold. Under Section 176 of the Indian Contract Act, 1872, you have 3 strict legal rights:
The bank must send you a mandatory 14-day written notice and publish public auction notices in local newspapers. The auction must be conducted with a certified valuer maintaining RBI's 90% reserve price floor.
Extra Money Belongs to You: Because gold prices have risen significantly in recent years, auctioned gold often sells for more than what you owed the bank. Under Section 176, ICICI is legally obligated to refund the extra surplus cash back to your bank account within 30 days. If ICICI tries to adjust that surplus against an old credit card without your permission, file an immediate objection with the Principal Nodal Officer and the RBI Banking Ombudsman.
8. Legal Notices: Section 138, Section 25 & Section 351 BNS Shields
When an ICICI loan defaults, collection agencies send legal notices drafted by bank advocates to push you to pay. Understanding what they actually mean will protect you from panic:
Section 138 NI Act (Cheque Bounce):Applies only if a physical paper cheque you signed bounced. You receive a 15-day notice to reply. Having a lawyer send an official reply proposing a settlement almost always moves the matter smoothly to Lok Adalat without jail time.
Section 25 PSS Act (eNACH / Auto-Debit Bounce):Applies when your automatic bank EMI deduction bounces due to low account balance. It is purely a civil dispute resolved through an amicable settlement.
Section 351 Bharatiya Nyaya Sanhita (BNS), 2024 (Your Legal Shield):This is your legal shield against abusive recovery agents. Under India's new penal code (Section 351 BNS, formerly 506 IPC), any agent who threatens your family, calls your workplace, abuses you, or visits your house outside 8 AM to 7 PM commits a crime punishable with up to 2 years imprisonment. You can register an immediate police complaint against the agent and the bank.
9. National Lok Adalat: ICICI's Fastest Settlement Channel
National Lok Adalats are government-organized settlement courts conducted every 3 months by NALSA across all district courts in India. ICICI Bank participates actively in Lok Adalat to close bad debts.
At Lok Adalat, senior ICICI managers attend with pre-approved settlement authority to close cases without waiting weeks for head office approvals. However, as of September 2026, ICICI has tightened compromise limits even for Lok Adalat benches: ICICI is not offering high waivers (50% to 70%) and is capping settlements at strictly 30% to 40% waivers, nothing more than that. Best of all, the settlement agreement signed before a Lok Adalat judge carries the permanent power of a civil court decree-meaning the bank or any collection agency can never reopen your file or demand money ever again. It is 100% free with zero court fees.
10. Operational Settlement Logistics: Why Local Branches Say NO & How to Pay
A major point of confusion is visiting your local neighborhood ICICI branch. Branch staff will almost always tell you: "ICICI does not do settlements. You have to pay the full amount."
Why? Because local branches are judged only on opening new accounts and selling fresh loans. They have ₹0 authority to approve loan discounts! Settlements are handled strictly by ICICI's specialized Stressed Assets Management Branch (SAMB) located at regional corporate offices.
Zero-Fraud Payment Rules:- • Never pay cash to any recovery agent, lawyer, or third-party collection agency.
- • Never transfer money to any personal UPI ID or third-party bank account.
- • Payments must be made strictly via NEFT/RTGS directly to
ICICI Bank Ltd - A/C [Your 16-Digit Loan Account Number]. - • ICICI is required by RBI rules to send your physical No Dues Certificate (NDC) to your registered home address within 21 to 30 working days.
11. iMobile App Digital Settlement Popups & How to Negotiate
ICICI Bank frequently shows pre-approved digital settlement banners inside the iMobile Pay app to borrowers who are 3 to 6 months late, stating: "Special One-Time Closure Offer: Pay ₹X to close your loan today."
These digital app offers are generated by automated computer models and usually offer only a small 15% to 25% discount. Smart Borrower Tip: Take a clear screenshot of the in-app offer. That screenshot proves ICICI has officially approved your account for a settlement discount. You can take that screenshot to senior SAMB recovery managers or Lok Adalat as your starting point to negotiate up to ICICI's current ceiling of 30% to 40% waiver (as of September 2026, ICICI does not offer high waivers like 50% to 70% under any circumstance).
12. 7 Checkpoints of a Real ICICI Settlement Letter
Never pay a single rupee based on a phone call or WhatsApp message! Fake collection agents often send fake letters, collect your money, and pocket it while your debt stays unpaid. Before paying, make sure your letter has all 7 safety checkpoints:
The 7-Point Safety Inspection Checklist:- Official Bank Letterhead: Printed on official stationery showing ICICI Bank Ltd logos and corporate office address (Bandra Kurla Complex, Mumbai).
- Unique Reference Number: Carries an internal tracking reference number verifiable in ICICI's computer system.
- Your Exact Details: Shows your full legal name, PAN card number, and exact 16-digit Loan or Credit Card account number.
- Clear Money Breakdown: Shows total claimed dues, the discount given, and the exact net settlement amount payable with a clear due date.
- Full & Final Closure Clause: Explicit sentence confirming that paying this amount extinguishes all debts and no further liability remains.
- Authorized Signature & Stamp: Signed and stamped by an authorized ICICI Bank SAMB manager with their official employee code.
- Official Email Delivery: Must be emailed directly from an official bank email address (
@icicibank.com)-never from Gmail, Yahoo, or WhatsApp.
13. What Happens to Your CIBIL Score & How to Rebuild It
After an OTS settlement, ICICI Bank reports the account to CIBIL and other credit bureaus as: "Settled" (or "Post-Write-off Settled"). Your score drops by 75 to 100 points, but all recovery calls, legal threats, and interest compounding stop permanently on that day.
Can You Change “Settled” to “Closed” Later? Yes! If your financial situation recovers 2 to 3 years later and you want to apply for a fresh home loan, ICICI allows you to pay the remaining discount difference that was originally waived (without extra interest), and they will update your CIBIL status to clean "Closed".
How to Rebuild a 750+ CIBIL Score Fast: Open a Fixed Deposit (FD) of ₹20,000 to ₹30,000 at any bank and get an FD-backed secured credit card. Spend a small amount each month and pay the full bill on time for 18 to 24 months. Your credit score will climb steadily back above 750+.