1. Why Kotak Bank Settles Bad Loans (The Provisioning & ARC Reality)
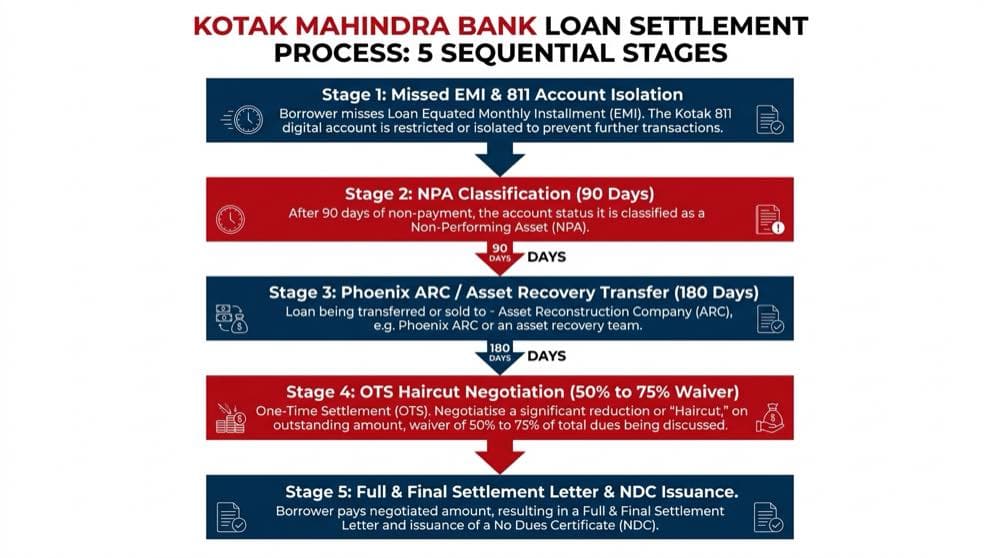
Kotak Mahindra Bank is a commercial private lender governed by Reserve Bank of India (RBI) capital provisioning mandates. When payments stop on an unsecured loan or credit card, the account moves through this statutory lifecycle:
● 0 to 90 Days Past Due (DPD): Loan remains in soft collections. Automated SMS notices and call centers dial daily. Credit bureaus record late marks.
● 90 to 180 DPD (NPA Stage): Under RBI rules, the account is classified as a Non-Performing Asset (NPA). Kotak must set aside 15% to 25% of the loan amount from its quarterly profits as capital provision.
● 180+ DPD (Loss Asset Pool): By 180 days, Kotak must make a 100% loss provision. The file is handed over to the specialized Asset Recovery department or packaged for assignment to an Asset Reconstruction Company (ARC).
At the 180+ DPD stage, filing a civil court suit takes 5 to 7 years in Indian courts and costs substantial legal fees. Recovering 35% to 50% cash through an OTS clears bad debt off the balance sheet immediately.