How Does a Loan of 5000 Become 2 Lakh Rupees: Trap & Exit
The 7-Day App Trap, Blackmail Cycles & Legal Ways to Stop
If you borrowed Rs 5,000 from an instant loan app and now face demands for Rs 2,00,000, you are not alone. You walked into an organized cyber extortion racket.
Thousands of borrowers fall into this trap every month. What starts as a small emergency loan becomes a nightmare of harassment, morphed photos, and threat calls. In this guide, we explain the math trap, why paying more fails, and how to stop harassment immediately.
01. The Rs 5,000 Hook: How Predatory Apps Lure Borrowers
Predatory loan apps advertise on Instagram, Facebook, and SMS. They promise instant cash with zero credit checks. They target students, gig workers, and daily wage earners. The hook is simple: get Rs 5,000 in two minutes using just your Aadhaar card.
Under RBI Digital Lending Guidelines (September 2022), every legal digital lending app must partner with a licensed bank or NBFC. Regulated lenders must issue a Key Fact Statement (KFS) showing the Annual Percentage Rate (APR). Predatory apps provide zero disclosures. They are unregistered, illegal APKs operating outside Indian law.
02. The Mathematical Trap: Upfront Cuts & 7-Day Rollover Math
Turning a Rs 5,000 loan into Rs 2 lakhs is a calculated trick. It uses massive upfront deductions and 7-day rollover cycles. The effective interest rate exceeds 3,000 percent per year.
| Stage | Deduction | Cash Got | Demanded |
|---|---|---|---|
| App 1 (Day 1) | Rs 1,800 (36%) | Rs 3,200 | Rs 5,000 |
| Rollover (Day 7) | Rs 2,000 fee | Rs 0 | Rs 5,000 |
| Apps 2 & 3 (Day 14) | Rs 3,600 | Rs 6,400 | Rs 10,000 |
| Apps 4 to 8 (Day 30) | Rs 12,600 | Rs 22,400 | Rs 35,000 |
| Apps 9 to 20 (Day 60) | Rs 45,000 | Rs 75,000 | Rs 2,10,000+ |
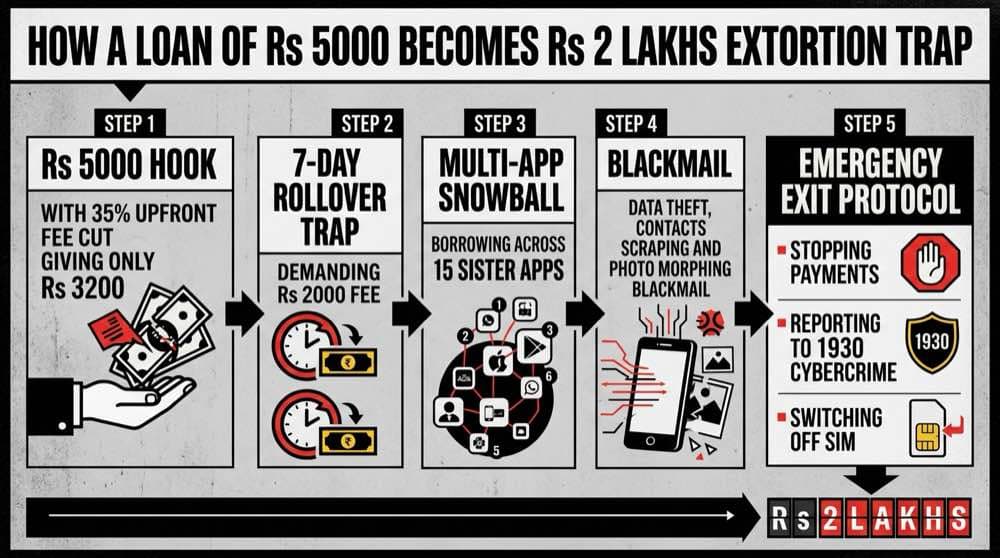
When you apply for Rs 5,000, the app deposits only Rs 3,200. It deducts Rs 1,800 upfront as fake processing fees. On Day 6, agents demand the full Rs 5,000. If you cannot pay, they offer an extension: pay Rs 2,000 as a rollover fee. This fee does not reduce your loan balance. You still owe Rs 5,000.
03. The Multi-App Snowball: How 1 App Turns into 20 Sister Apps
When you struggle to pay the rollover fee, recovery agents send links to sister apps. They say: "Download QuickMoney to clear your due today." All these apps belong to the same criminal syndicate.
To pay App 1, you borrow from App 2 and App 3. These apps also deduct 35 percent upfront and demand money in 7 days. Within two months, you borrow across 15 to 20 apps. You received less than Rs 40,000 in cash, but the syndicate demands over Rs 2,00,000.
04. Data Theft & APK Malware: Contacts Scraping and Photo Morphing
Illegal loan apps rely on stolen data, not legal power. When you install an untrusted APK, it asks for contacts, gallery, SMS, and location permissions.
Under the Supreme Court ruling in Puttaswamy v. Union of India, your data is protected under Article 21. RBI guidelines strictly ban lending apps from accessing mobile contacts or photos. Illegal apps violate this law. When you miss a payment, call centers harvest your contacts. They call your parents, spouse, and boss. They also create morphed vulgar images and threaten to leak them.
05. The Golden Rule of Cyber Extortion: Why Paying Never Works
Paying money never stops cyber extortion. It only confirms that you are afraid and have funds.
When you pay, extortionists mark you as a paying victim. If you transfer Rs 5,000 to close a loan, they often deposit another Rs 3,000 without consent and demand Rs 6,000 next week. You must stop paying immediately, cut off communication, and file cybercrime complaints.
Loan Extortion Spiral Simulator & Defense Tools
Simulate how a Rs 5,000 loan escalates into lakhs, verify illegal APKs, and generate emergency broadcast notices.
You received only Rs 38,400 in real money, yet the syndicate is demanding Rs 1,80,000. Paying rollover fees will never clear this balance because the principal amount remains untouched.
07. Criminal Laws & Statutory Shields (BNS & IT Act)
Illegal loan apps have zero legal authority in India. They cannot file civil suits, issue warrants, or harm your CIBIL score. Their collection methods violate multiple criminal laws:
Puts a person in fear of injury or character damage to extort money. Carries up to 7 years imprisonment.
Threatening injury to a person reputation or property. Carries up to 2 years imprisonment.
Punishes vulgar comments, threats, and morphed photos targeting women.
Penalizes privacy violations and transmitting obscene electronic content.
08. Immediate 4-Step Emergency Protocol to Neutralize Harassment
Open Phone Settings > Apps. Revoke Contacts, Gallery, and Location permissions. Clear cache and delete the APK.
Use a fresh secondary SIM for daily calls. Keep your old SIM on silent in a spare phone to preserve SMS evidence.
Lock your Facebook and Instagram profiles. Make friend lists private to block scammers from finding more relatives.
Never pay money to any UPI ID or bank account. A total financial cut-off forces the gang to abandon the account.
09. Broadcast Message Template to Protect Your Reputation
Send this message to your family and WhatsApp groups. Neutralizing public shame removes the primary weapon of extortionists:
"URGENT NOTICE TO ALL CONTACTS: My phone was compromised by a scam application that stole my contact list. Fraudsters are sending fake messages and altered photos from unknown numbers to extort money. Please DO NOT respond to or pay any caller claiming to represent a loan company on my behalf. A formal complaint has been filed on the National Cybercrime Portal (Helpline 1930). Thank you."
10. Official Helplines & Cybercrime Reporting Steps
File complaints across these three verified government channels to freeze fraud accounts and create police records:
All these RBI rules, regulatory guidelines, and police FIR provisions exist officially in the books. However, the ground reality is that the Indian judicial and police system moves very slowly. In most everyday cases, lodging a formal complaint or filing an FIR will not give you immediate relief from aggressive collection calls.
The honest fact is: until all of your outstanding loans are either officially settled (via One-Time Settlement) or fully closed, the probability of getting complete peace of mind from recovery agencies is very low.
1. Change Your Mobile Number: Switch to a fresh SIM card for daily use, sharing it strictly with close family. Keep your old loan-registered SIM on silent in a spare phone to check SMS once weekly for official bank notices. This instantly cuts off the non-stop daily barrage of abusive phone calls.
2. Shift Your Residential Address: If recovery agents or local collection musclemen know your rented flat and keep showing up to humiliate you before neighbors, relocate to a different address if possible to protect your family from doorstep embarrassment.
3. Delete the Loan App & Revoke All Permissions: Immediately uninstall the lending app from your smartphone. Before deleting, open phone settings, revoke all permissions (contacts, storage, camera, location), and clear app data so trackers cannot continue harvesting your real-time data or accessing your contact list.
Frequently Asked Questions
How does an instant loan of Rs 5000 turn into a debt of Rs 2 lakhs?+
The trap works through 7-day tenures, 35% upfront fee cuts, and weekly rollover fees. When borrowers struggle, agents offer sister app links. Borrowing across 15 to 20 apps compounds debt into Rs 2,00,000 within 60 days.
Can illegal loan apps send police to my house or issue an arrest warrant?+
No. Illegal loan apps have zero legal authority. Unpaid personal loans are civil disputes under Indian law. Harassment and photo morphing by recovery agents are criminal offenses under Sections 308 and 351 of Bharatiya Nyaya Sanhita.
Will defaulting on an illegal 7-day loan app ruin my CIBIL credit score?+
No. Only RBI-regulated banks and NBFCs can report data to credit bureaus like CIBIL and Experian. Unregistered 7-day loan apps have no credit bureau access and cannot alter your credit score.
What should I do if a loan app threatens to send morphed photos to my contacts?+
Stop paying immediately. Broadcast a warning message to your contacts stating your phone was compromised. Call the Cybercrime Helpline at 1930 and file a complaint at cybercrime.gov.in. Then revoke permissions and uninstall the app.
Will the harassment stop if I pay the full amount demanded by the loan app?+
No. Paying confirms you are vulnerable and encourages more extortion. Criminals often deposit fresh money without consent and demand new payments. The only solution is to stop paying and cut off contact.
How do I know if a loan app is genuine or an illegal Chinese scam app?+
Genuine loan apps provide at least 3 months tenure, list an RBI-licensed NBFC partner, and provide a Key Fact Statement. Illegal apps offer 7-day tenures, deduct 35% upfront, scrape contacts, and use personal UPI IDs.
Can I file an FIR at my local police station against loan app blackmail?+
Yes. File an FIR under Section 308 (Extortion) and Section 351 (Criminal Intimidation) of BNS, and Section 66E/67 of the IT Act. Provide screenshots of threats, call records, and UPI receipts as evidence.
Where can I report illegal lending apps to the Reserve Bank of India?+
Report illegal apps directly on the RBI Sachet portal at sachet.rbi.org.in. You can also report cyber extortion at cybercrime.gov.in or dial the national helpline at 1930.
Official Statutory Resources & Regulatory Portals
RBI & GOVT VERIFIEDAccess official government portals, regulatory ombudsman channels, and statutory dispute resolution bodies governing Indian banking and borrower rights:
- RBI Integrated Ombudsman Scheme (CMS)↗
File complaints against bank recovery abuse and fair practice violations
- RBI Sachet Portal (Illegal Recovery & Harassment)↗
Report unauthorized lending apps and aggressive recovery agency violations
- NALSA National Lok Adalat Schedules↗
Statutory alternative dispute resolution for mutually agreed OTS settlements
- National Consumer Helpline (NCH)↗
Government grievance redressal under Department of Consumer Affairs
- National Cyber Crime Reporting Portal (1930)↗
Official reporting for recovery blackmail, cyber threats, and extortion
Community Discussion & Case Notes
0 CommentsNo comments posted yet. Be the first to share your experience below!
Join the Discussion & Share Your Experience
Have you dealt with this situation or received a notice? Share your questions or experience with other borrowers.