Bank Auctioned Property for More Than Dues? Claim Surplus
Did your bank auction mortgaged property for more than your debt? Claim your surplus funds under Section 13(7) of the SARFAESI Act with interest today.
Settle defaulted bank loans and credit cards safely through National Lok Adalat. Learn how statutory conciliation works. Verify genuine DLSA notices. Calculate waiver discounts. Secure a binding civil decree under Section 21 of the Legal Services Authorities Act.
Lok Adalat is a people's court under the Legal Services Authorities Act, 1987. It settles loan defaults before or during court cases. It covers personal loans, credit cards, education loans, and vehicle loans up to ₹20 Lakhs. Appearing is 100% voluntary. The panel cannot force any settlement. When both sides agree, they sign a Razinaama agreement. The Lok Adalat then issues an Award. Under Section 21, this Award is a final civil court decree. No appeal can be filed against it. There are zero court fees, and penal interest is fully waived.

Lok Adalats are held four times a year across India. They are organized by NALSA and District Legal Services Authorities (DLSA). For borrowers facing unpaid debt, Lok Adalat provides a safe place to resolve loans. You can settle disputes peacefully without long court trials.
Regular civil courts and DRT tribunals take years to resolve cases. In contrast, Lok Adalat focuses only on mutual compromise. The bench includes a judge, an advocate, and a social worker. They act as neutral helpers to resolve the debt.
In State of Punjab v. Jalour Singh (2008), the Supreme Court stated that Lok Adalat panels cannot pass forced orders. They cannot fine you or issue arrest warrants. A settlement only happens if you and the bank agree on a discount.
Bank loan disputes in Lok Adalat fall into two clear groups under Sections 19 and 20 of the Act:
Status: No civil suit or cheque bounce case is filed yet.
Trigger: Bank or borrower applies directly to the DLSA.
Court Fee: Zero court fees for either party.
Outcome: Resolves debt early and stops heavy legal costs.
Status: Case is already pending in a regular court.
Trigger: Both parties file a joint referral memo in court.
Fee Refund: Bank gets a 100% refund of court fees under Section 16.
Outcome: Immediate closure of the court case.
Use our live verification screener below to check if your notice is genuine or calculate your estimated pre-litigation settlement discount.
Verify if your Lok Adalat notice is genuine or calculate your estimated pre-litigation compromise waiver.
This is an authentic pre-litigation conciliation notice issued under the Legal Services Authorities Act, 1987. Attendance is 100% voluntary with zero risk of arrest. This is your best opportunity to negotiate a 30% to 60% One-Time Settlement directly with bank decision-makers.
Action: Carry your loan statements, ID proof, and income hardship documents to the court bench on the scheduled date.
Settling a loan in Lok Adalat gives you complete legal safety. Under Section 21 of the Legal Services Authorities Act, 1987:
Every Lok Adalat award is equal to a civil court decree. It carries the exact same power as a final judgment from a District Judge.
Under Section 21(2) of the Act and Section 96(3) CPC, no appeal can be filed against a Lok Adalat award. Once signed, the bank cannot reopen the debt. Collection agencies cannot ask for more money.
In K.N. Govindan Kutty Menon v. C.D. Shaji (2012), the Supreme Court gave a key ruling. Even if a case started under Section 138 for a bounced cheque, the Lok Adalat award works as a civil decree under Order 21 CPC.
Under RBI Circular RBI/2023-24/40 (DOR.STR.REC.20/21.04.048/2023-24), banks follow set rules for Lok Adalat settlements:
Attending a Lok Adalat session is simple, quick, and informal. Follow this 6-step roadmap:
Arrive at the District Court Complex by 10:00 AM on the scheduled Saturday. Check the DLSA help desk to find your bank counter.
Show your medical bills, salary cut slips, or job loss letters to the bank officer before entering the bench.
Offer a realistic lump sum or a 2-month installment plan you can afford. Never agree to an amount you cannot pay.
If the bank refuses, the judge and panel step in. They review your situation and urge the bank to accept a fair discount.
The court clerk writes down the agreed terms. Check that the settlement amount, payment dates, and NOC promise are written clearly.
Collect your signed and stamped certified copy of the Lok Adalat Award before leaving. This is your permanent legal proof.
Collection agencies often send fake notices on WhatsApp with copied court logos. Look for these 3 facts:
All these RBI rules, regulatory guidelines, and police FIR provisions exist officially in the books. However, the ground reality is that the Indian judicial and police system moves very slowly. In most everyday cases, lodging a formal complaint or filing an FIR will not give you immediate relief from aggressive collection calls.
The honest fact is: until all of your outstanding loans are either officially settled (via One-Time Settlement) or fully closed, the probability of getting complete peace of mind from recovery agencies is very low.
1. Change Your Mobile Number: Switch to a fresh SIM card for daily use, sharing it strictly with close family. Keep your old loan-registered SIM on silent in a spare phone to check SMS once weekly for official bank notices. This instantly cuts off the non-stop daily barrage of abusive phone calls.
2. Shift Your Residential Address: If recovery agents or local collection musclemen know your rented flat and keep showing up to humiliate you before neighbors, relocate to a different address if possible to protect your family from doorstep embarrassment.
3. Delete the Loan App & Revoke All Permissions: Immediately uninstall the lending app from your smartphone. Before deleting, open phone settings, revoke all permissions (contacts, storage, camera, location), and clear app data so trackers cannot continue harvesting your real-time data or accessing your contact list.
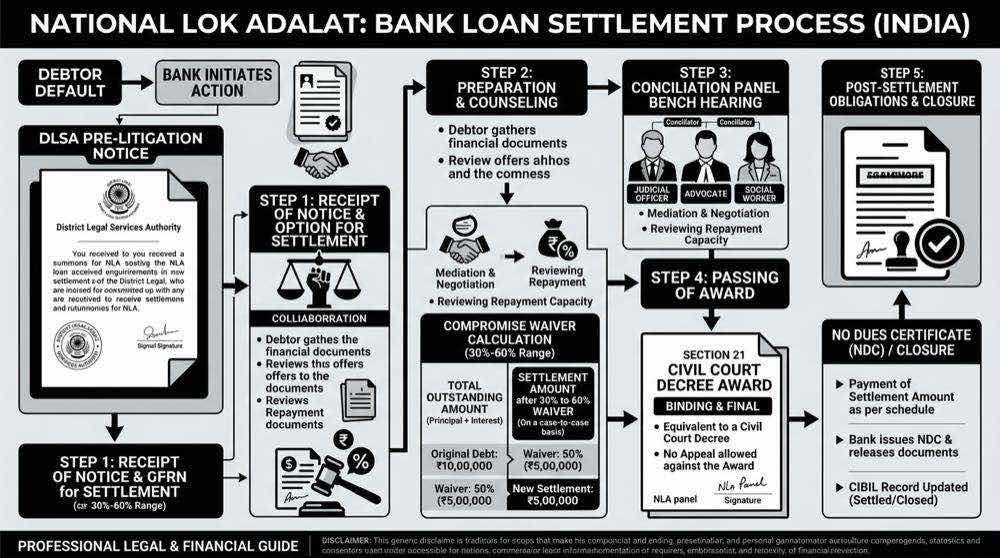
Once you complete the payment terms in the Lok Adalat Award, finish these closure steps:
Submit the Demand Draft receipt and your Lok Adalat Award copy to your bank branch manager. Get an official stamp on your duplicate copy.
The bank must issue a No Dues Certificate within 30 days and return any security cheques.
Under RBI rules, the bank must update your credit status across all 4 bureaus to Settled within 30 days. If the lender delays beyond 30 days, they must pay you ₹100 for each day of delay.
Use these official government bodies to check schedules, file complaints, or report fake notices:
No. Going to a Lok Adalat is completely voluntary. Lok Adalat is a mutual settlement forum, not a criminal court. If you do not attend, no police warrant or fine can be issued against you. However, attending helps you settle your debt directly with senior bank officers at a 30% to 60% discount with zero legal fees.
No. Lok Adalats cannot arrest borrowers or send anyone to jail. Under the Legal Services Authorities Act, the bench acts only as a neutral mediator. Defaulting on a personal loan or credit card is a civil issue, not a crime.
Under Section 21 of the Legal Services Authorities Act, 1987, a Lok Adalat award is equal to a civil court decree. It is final and binding on both sides. No court appeal can be filed against it. Once signed, the bank cannot demand any waived amount or file fresh cases.
Banks routinely waive 100% of penal charges, late fees, and bounce interest on the spot. For loans unpaid for over one to two years, banks frequently agree to a 30% to 60% discount on the principal and normal interest.
Do not panic and never pay money on UPI. Real Lok Adalat notices come from the District Legal Services Authority (DLSA) by physical post with an official court seal and PLR case number. Report fake WhatsApp threats to the Cybercrime Portal at cybercrime.gov.in or dial 1930.
No. You do not need to hire an advocate. Lok Adalat is designed for ordinary citizens to speak directly with the conciliation panel without paying lawyer fees or court charges.
When you settle a loan for a discounted amount, the bank reports the account status as Settled on CIBIL. This stops legal actions and default remarks. Your credit score will drop initially. You can rebuild it back to 750+ over 12 to 24 months using secured credit cards and on-time payments.
Carry your Aadhaar or PAN card, the Lok Adalat notice, loan account statements, and proof of financial hardship like medical bills, salary deduction slips, or job loss letters.
Access official government portals, regulatory ombudsman channels, and statutory dispute resolution bodies governing Indian banking and borrower rights:
File complaints against bank recovery abuse and fair practice violations
Report unauthorized lending apps and aggressive recovery agency violations
Statutory alternative dispute resolution for mutually agreed OTS settlements
Government grievance redressal under Department of Consumer Affairs
Official reporting for recovery blackmail, cyber threats, and extortion
Did your bank auction mortgaged property for more than your debt? Claim your surplus funds under Section 13(7) of the SARFAESI Act with interest today.
Bank claims pledged gold jewelry is fake or missing? Learn your legal rights under Contract Act, BNS 316, appraiser estoppel, and recover full value.
Can a bank seize your laptop or tools for loan default? Learn Section 60 CPC artisan exemptions, SARFAESI Section 31(g), and how to stop recovery agents.
Did your bank or NBFC unilaterally appoint a sole arbitrator for loan recovery? Learn how Section 12(5), Perkins Eastman, and 2024 SC rulings invalidate void arbitration awards and protect your salary.
No comments posted yet. Be the first to share your experience below!
Have you dealt with this situation or received a notice? Share your questions or experience with other borrowers.
If this guide has helped you navigate your settlement journey, consider showing some support to keep this platform running.