HomeAbout
BlogSoon
Bank specific setupSoon
LocationsSoon
WARNING: THIS IS NOT LEGAL ADVICE. THIS IS SURVIVAL ADVICE BASED ON REAL BORROWER EXPERIENCE.
UPDATED: SEPTEMBER 2026

Union Bank of India Loan Settlement Process & OTS Rules

How to Settle Union Bank Personal, Card & MSME Debt

If you are struggling with unpaid Union Bank of India loans or credit cards, you are not alone. This guide explains how to navigate public sector vigilance rules, stop recovery harassment, and negotiate an official One-Time Settlement (OTS) under Union Bank circulars for 40% to 65% less.

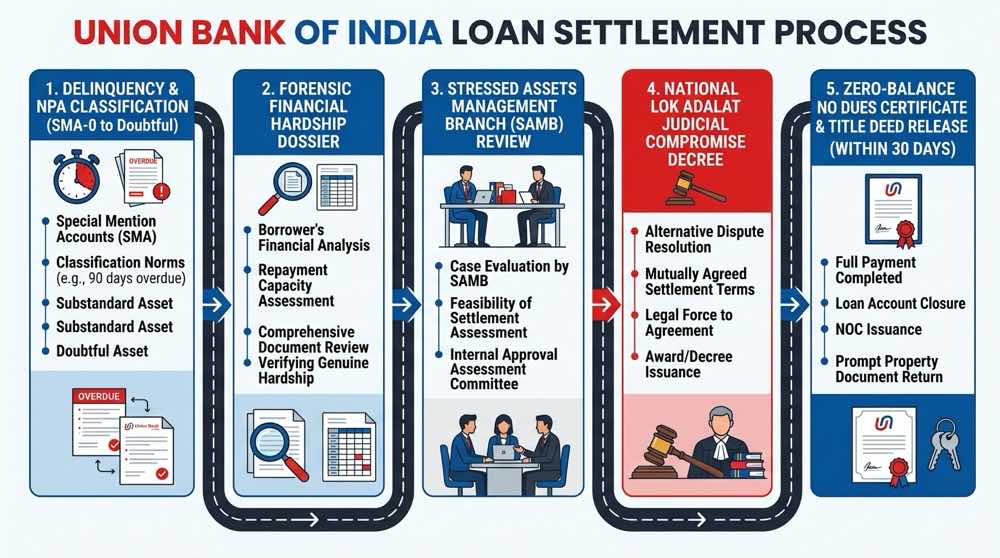
Union Bank of India Loan Settlement Process, SAMB Escalation and OTS Workflow

Figure 1: Official settlement hierarchy and Special OTS compromise procedure across Union Bank branches and SAMB offices.

Quick Answer Summary

Union Bank of India settlements follow clear rules under official Special OTS circulars and National Lok Adalat benches. Frontline branch staff cannot grant random discounts because government audit teams (CVC and CAG) track every rupee. For personal loans, credit cards, and Mudra accounts unpaid for over 6 months, authorized SAMB committees can approve 40% to 65% principal discounts with 100% penalty waivers. Always pay directly into your loan account and collect an unconditional No Dues Certificate within 30 days under RBI rules.

⚡ Empirical CalculatorUNSECURED NPA

Union Bank Settlement & Haircut Estimator

Calculate realistic One-Time Settlement (OTS) compromise ranges based on Union Bank Special OTS & Lok Adalat recovery guidelines.

Unsecured retail advance. Delinquent accounts past 180 DPD qualify for 100% penal interest waiver and up to 55% principal reduction.

₹5,00,000
₹50,000₹25,00,000₹50,00,000
Target Settlement Offer:45%–60% Haircut
Realistic Settlement Range:₹2,00,000₹2,75,000
Estimated Debt Forgiven:₹2,25,000₹3,00,000
*100% of accumulated penal interest & bounce charges waived under Special OTS.
⚠️
Union Bank Recovery Caveat:Union Bank core banking enforces automated Banker's General Lien under Section 171. Move your salary or pension account to another bank before starting compromise talks.

1. Union Bank Institutional Reality: Public Sector Vigilance Architecture

Union Bank of India is a major public sector bank. It grew even larger after merging with Andhra Bank and Corporation Bank. However, settling an unpaid loan with a government bank is very different from dealing with a private lender.

Private banks make fast deals to clear bad debts. But Union Bank handles public funds. Every loan waiver or interest cut is checked by the Central Vigilance Commission (CVC) and the Comptroller and Auditor General (CAG).

Because of these strict checks, bank officers cannot give you personal discounts. If an officer cuts your debt without a written circular, they face internal inquiries and risk losing their job or pension.

The Public Sector Audit Rule

Do not rely on verbal promises from branch staff or recovery callers. They have zero power to cut your loan on their own. To get a real discount, you must apply under an official Union Bank OTS scheme or settle in National Lok Adalat.

2. SAMB & Zonal Recovery Desks: Delegated Settlement Powers

When you miss payments for 90 days, your loan becomes a Non-Performing Asset (NPA). At this stage, your local branch cannot handle the settlement alone.

Branch Level (Scale I to IV)

Branch managers handle small retail accounts and minor Mudra loans. They can only waive small penalty fees. For larger balances, branch staff simply collect your papers to send upward.

Stressed Assets Management Branches (SAMB)

SAMBs and Regional Recovery branches hold real decision power. Senior panels run by Deputy General Managers (DGMs) review settlements from ₹10 lakh to ₹5 crore.

If your debt is large, do not waste time arguing with branch clerks or phone recovery callers. Submit your formal settlement application directly to the Regional Recovery Head / DGM SAMB.

3. Union Special OTS Scheme Formula: How Waivers Are Calculated

Union Bank launches official Special OTS Schemes every year. The best discounts come near September and March when the bank cleans its books before financial deadlines.

Loan StatusTime OverdueSettlement RuleTarget Discount
Sub-Standard (NPA)90 to 365 days100% Principal + Simple Interest15% to 30% Off
Doubtful Category 1 (D1)1 to 2 years100% Principal, Zero Penal Fees30% to 45% Off
Doubtful Category 2/3 (D2/D3)2 to 4+ years70% to 80% Principal Compromise45% to 60% Off
Loss Asset / Written-OffFully written-off35% to 50% of Ledger Balance50% to 65%+ Off

Who Cannot Get an OTS: Wilful defaulters (people who have money but refuse to pay) and fraud cases cannot get a settlement. But if you lost your job, had a medical emergency, or your business shut down, you qualify easily.

4. National Lok Adalat: The 40% to 65% Judicial Shield

The fastest and safest way to settle your Union Bank debt is the National Lok Adalat. These court drives happen every three months in all district courts across India.

Why Union Bank Officers Prefer Lok Adalat

Bank officers who hesitate at the branch gladly approve 40% to 65% discounts in Lok Adalat. Under Section 21 of the Legal Services Authorities Act, 1987, a Lok Adalat order is a final civil court decree. It cannot be challenged in court, and it shields bank officers completely from future audit inquiries.

If you receive a Lok Adalat notice from Union Bank, attend the session in person. Bring your medical records, salary slips, or business loss proof, and offer an immediate one-time payment.

5. Personal & Pensioner Loans: Section 171 Banker's General Lien

Union Bank gives out unsecured loans like Union Personal Loans, Union Ashiyana Personal, and Pensioner Advances. If you miss payments, the bank acts fast inside its computer systems.

Automated Section 171 Banker's Lien

Under Section 171 of the Indian Contract Act, 1872 (called the Banker's Right of Set-Off), Union Bank can freeze your savings account. If your loan is unpaid, their Finacle computer system puts an internal debit freeze on any savings account, current account, or fixed deposit under your CIF ID.

If you are a defense or government pensioner, this freeze can lock your family's living money without warning. Protect your money with three simple steps:

  • Open a fresh savings account in another bank before your loan is 60 days overdue.
  • Submit a request to your pension office to send your pension to your new bank.
  • Keep zero balance in your Union Bank accounts while you negotiate your settlement.

6. Union Bank Credit Cards: Tackling 39.5% Compounded APR

Credit cards issued by Union Bank charge monthly interest up to 3.25%. That adds up to nearly 40% per year once you add late fees and 18% GST.

How to Negotiate Your Union Bank Card Bill

When talking to Union Bank credit card recovery teams, never accept the total inflated bill. Ask for your complete itemized statement. Strip away all interest, late fees, and overlimit charges to find your pure principal spend. Union Bank settlement officers can waive 100% of these extra charges. This lets you settle the money you actually spent for 30% to 50% less.

7. Union Home Loans vs Andhra/Corporation Mortgages & Farmland Exemption (Sec 31(i))

The amalgamation of Andhra Bank and Corporation Bank into Union Bank of India created a consolidated mortgage ledger spanning multiple legacy systems. All legacy advances are now governed by Union Bank's SARFAESI enforcement desks.

SARFAESI Timelines & Agricultural Land Protections

  • Section 13(2) Demand: 60-day window to file written objections and OTS representations under Section 13(3A).
  • Section 14 Eviction Safeguards: Recovery teams cannot dispossess residential occupants without a formal physical warrant issued by the District Magistrate (DM) or Chief Metropolitan Magistrate (CMM).
  • Agricultural Farmland Protection: Under Section 31(i) of the SARFAESI Act, 2002, agricultural land is completely exempt from SARFAESI enforcement. Union Bank has zero statutory authority to issue notices, attach, or auction farmlands under this enactment.

On primary residential mortgages, while principal reductions are restricted by policy, SAMB desks routinely sanction 100% waivers of penal interest, administrative levies, and court expenses upon full cash settlement.

8. SAMB Sanction Letter Audit, Direct CBS Remittance & 30-Day NDC SLA

Never remit funds based on verbal promises or collection agency communications. An authentic Union Bank compromise requires a formal sanction letter issued by the Stressed Assets Management Branch (SAMB) or Regional Recovery Committee.

● CBS Core Account Payment Only: Deposit settlement sums directly into your 15-digit Union Bank loan account number using NEFT/RTGS with your branch IFSC code (UBIN0...), or submit an Account Payee Demand Draft drawn to "Union Bank of India A/C [Your Loan Number]". Never pay cash to recovery agents.

● Statutory 30-Day NDC & Document Release SLA: In strict compliance with RBI circular RBI/2023-24/60, Union Bank must issue your formal No Dues Certificate and return all original property title deeds within 30 calendar days of receiving full settlement proceeds. Any unjustified delay mandates the bank to pay compensation of ₹5,000 for each day of delay.

● Bureau Updating & Rebuilding: 45 days after payment, inspect your CIBIL report to confirm the balance is reported as ₹0 with status "Settled". Rebuild your credit score back above 750 over 18 to 24 months by maintaining disciplined on-time payments on an FD-backed credit card.

Tier 1Base Branch Manager & Regional Office
SLA: 7 - 10 Working Days

Authority: Initial Grievance / Branch Recovery Point

Contact: Toll-free: 1800 22 22 44 / 1800 208 2244 | Online: ICMT Portal (icmt.unionbankofindia.co.in)

Jurisdiction: Handles factual ledger balance errors, initial OTS proposal collection, and branch service issues.

Tier 2Stressed Assets Management Branch (SAMB) & Zonal Head
SLA: 10 - 15 Working Days

Authority: Zonal Recovery Head / DGM SAMB

Contact: Jurisdictional SAMB / Zonal Office via ICMT Level 2 Escalation

Jurisdiction: Evaluates and sanctions compromise proposals between ₹10 lakh and ₹1 crore under Union Special OTS schemes.

Tier 3Chief Grievance Officer (CGO) & Principal Nodal Officer
SLA: 15 Working Days

Authority: Chief General Manager & Chief Operations Officer

Contact: The Arcade, Tower 4, 2nd Floor, World Trade Centre, Cuffe Parade, Mumbai - 400005 | Phone: 022-2178871 | Email: cgo@unionbankofindia.bank

Jurisdiction: Senior-most internal apex authority for recovery agent misconduct, unlawful liens, and rejected OTS appeals.

Tier 4RBI Banking Ombudsman (Statutory Regulator)
SLA: 30 Days Post-CGO

Authority: Reserve Bank of India Consumer Education and Protection Cell

Contact: Portal: cms.rbi.org.in | Toll-Free: 14448 | Postal: CRPC, RBI, 4th Floor, Sector 17, Chandigarh - 160017

Jurisdiction: Binding regulatory adjudication under the Reserve Bank - Integrated Ombudsman Scheme, 2021.

📝

1-Click Union Bank CGO Harassment & OTS Template

Personalize the bracketed variables and email directly to cgo@unionbankofindia.bank.

Subject: URGENT: Third-Party Harassment & Formal OTS Settlement Submission - Loan A/C [Your Account Number]

To:
The Chief Grievance Officer (CGO) / Principal Nodal Officer,
Union Bank of India, World Trade Centre, Cuffe Parade,
Email: cgo@unionbankofindia.bank

Cc:
Customer Care: customercare@unionbankofindia.bank.in

Dear Sir/Madam,

I am writing regarding my Loan/Credit Card Account Number [Your Account Number] maintained with Union Bank of India [Branch Name].

Due to severe involuntary financial hardship resulting from [State Reason: e.g., Critical Medical Illness / Sudden Unemployment / Enterprise Insolvency], I have suffered a total breakdown in regular EMI servicing capacity. I have formally approached the branch to execute a legitimate One-Time Settlement (OTS) compromise within my genuine financial means.

However, recovery agents claiming to represent Union Bank of India have engaged in unlawful recovery intimidation:
1. Contacting me outside the RBI-prescribed window (8:00 AM to 7:00 PM).
2. Using abusive, coercive, and threatening language in clear breach of the RBI Master Direction on Fair Practices Code.
3. Attempting to intimidate third parties and relatives who have no legal privity of contract with the bank.

Please note that these actions violate RBI guidelines and constitute an offense under Section 351 of the Bharatiya Nyaya Sanhita (BNS) for criminal intimidation.

I hereby formally demand:
1. Immediate cessation of all unauthorized collection visits and abusive telecalling.
2. Formal processing of my compromise settlement proposal under the Union Bank Special OTS framework.
3. Official written communication sent exclusively to my registered email address.

Yours faithfully,
[Your Name]
[Contact Number]
[City]

9. Frequently Asked Questions (Union Bank of India Loan Settlement)

Can I negotiate a loan settlement directly with my Union Bank branch manager?
Branch managers cannot approve big debt waivers. They face strict audits from the CVC and CAG. For 40% to 65% discounts, your request must go to the Stressed Assets Management Branch (SAMB) or be settled in National Lok Adalat.
What is Union Bank's Special OTS Scheme and who is eligible?
It is an official board-approved compromise scheme for overdue NPA loans. Discounts depend on how long your loan has been unpaid. Wilful defaulters and fraud cases cannot apply. Genuine borrowers facing job loss or medical trouble qualify easily.
Can Union Bank freeze my savings account under Section 171?
Yes. Under Section 171 of the Indian Contract Act (Banker's Right of Set-Off), Union Bank's system can freeze any account linked to your CIF ID. Move your salary and living money to another bank before you default.
What percentage waiver is realistic on an unsecured Union Bank personal loan?
If your personal loan is overdue for more than 6 months, you can get a 35% to 60% discount on the principal balance. The bank will also waive 100% of penalty interest and late fees.
How are legacy Andhra Bank and Corporation Bank loans resolved post-merger?
All old Andhra and Corporation Bank accounts are now part of Union Bank of India. You follow the exact same Union Bank OTS rules and settlement steps to resolve them.
Can Union Bank auction my agricultural land under the SARFAESI Act?
No. Section 31(i) of the SARFAESI Act protects agricultural land. Union Bank cannot seize or auction your farm fields under SARFAESI. They must go to a civil court instead.
Why is National Lok Adalat the most effective venue to settle with Union Bank?
Lok Adalat orders have the power of a civil court decree under Section 21 of the Legal Services Authorities Act. Bank officers get full legal protection from audit checks, so they offer their biggest discounts (40% to 65%).
What finance charges apply when Union Bank credit cards default?
Overdue cards charge up to 3.25% per month (nearly 40% per year) with taxes and fees. Ask for your full billing statement. Demand 100% waiver on interest and fees, and settle the pure principal spend for 30% to 50% less.
How many days does Union Bank have to issue my No Dues Certificate?
Under RBI rules (RBI/2023-24/60), Union Bank must give you your No Dues Certificate and return all property papers within 30 days of full payment. If they delay, they must pay you ₹5,000 for every day of delay.
What happens to my CIBIL credit report after completing a Union Bank settlement?
The bank marks your loan as 'Settled' instead of 'Closed'. Your score may drop by 50 to 100 points temporarily. You can rebuild your score back above 750 within 18 to 24 months by using a fixed deposit credit card responsibly.

Find this content helpful?

If this guide has helped you navigate your settlement journey, consider showing some support to keep this platform running.