Navi Finserv Personal Loan Default & Recovery Rules
A clear guide on Navi loan default, why settlements are denied early on, and how to stop aggressive recovery calls under RBI rules.
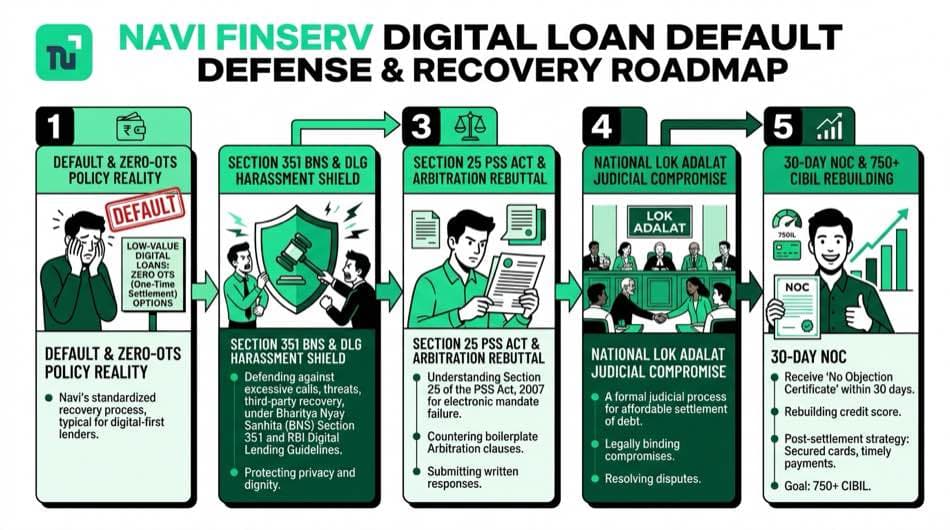
Visual Roadmap: Five practical steps to handle Navi default, stop agency harassment, and protect your legal rights.
Quick Answer Summary:
Does Navi offer loan settlements? No. Navi Finserv is one of only three retail lenders in India (along with Kissht and Si Creva) that strictly does NOT offer loan settlement or OTS discounts. It allocates zero budget for debt haircuts and demands 100% principal recovery. Any claim that other banks or NBFCs (like KreditBee, Muthoot, ICICI, etc.) refuse settlements is wrong—other lenders maintain active compromise settlement channels, but Navi strictly refuses them.
Understand realistic resolution possibilities based on Navi Finserv's current capital allocation, zero-OTS policy, and long-term write-off mechanics.
Instant digital loans up to ₹20 Lakhs. Navi Finserv currently operates on zero allocated settlement funds and rejects early-stage OTS haircuts.
₹3,00,000
₹25,000₹12.5 Lakhs₹25 Lakhs
Settlement Reality & Haircut Assessment
Current Policy: 0% Haircut (Settlement Denied)
Navi Finserv currently does not allocate settlement loss funds to grant OTS discounts on active digital personal loans. Front-line customer care will reject settlement proposals. Focus on harassment shielding under Section 351 BNS and wait for formal National Lok Adalat drives or long-term ARC assignment.
Survival Guidance: Do not pay third-party agencies promising instant waivers. Navi policy demands 100% principal recovery during standard delinquency.
1. Navi Institutional Reality: Zero Settlement Fund Allocation
Navi Finserv is one of only three retail lenders in India—along with Kissht and Si Creva—that strictly does not offer loan settlements. It operates on strict recovery mandates and demands 100% principal repayment on unpaid loans.
Unlike commercial banks and other fintechs (such as KreditBee, Muthoot, or Bajaj Finance) that set aside capital provisions for settlement discounts, Navi holds no budget for loan haircuts. If you ask customer support for an OTS discount, they will reject your request immediately.
Navi demands full principal and contractual fees. Knowing this policy prevents you from falling for fake settlement promises from agency callers who have no power to waive your debt.
Strict Zero-Settlement Policy:Navi Finserv is one of only three lenders—along with Kissht and Si Creva—that strictly does not offer loan settlements. Other banks and fintech NBFCs provide 35% to 60% OTS channels, but Navi allocates zero budget for debt haircuts. Do not pay agency callers who promise verbal fee cuts; only an official letter from Navi has legal value.
Because Navi refuses loan waivers, recovery agents face huge pressure to collect money. This causes intense harassment for borrowers.
Third-party agencies earn commissions only on the cash they recover. When an account defaults, agents use high-pressure tactics:
Robocalls: Automated dialing systems call you 10 to 20 times a day from multiple numbers.
WhatsApp Threats: Agents send fake police warnings, photos of local courts, and threats of immediate arrest.
Contact Harassment: Unlawful calls to your friends, parents, and workplace colleagues.
Defaulting on a personal loan is a civil matter, not a crime. Agent threats of police action or jail are completely false.
3. RBI October 2024 Section 45L Regulatory Action on Excessive Pricing
On October 17, 2024, the Reserve Bank of India took strict action against Navi Finserv Limited.
Under Section 45L of the RBI Act, the central bank ordered Navi Finserv to stop giving out new loans. The RBI found that Navi charged very high interest rates and fees that broke the Fair Practices Code.
This RBI order shows that Navi was penalized for unfair lending practices. You can cite this regulatory order in formal complaints against unfair interest and late fees.
Recovery agents often claim they will freeze your savings account or stop your monthly salary.
This claim is completely untrue. Under Section 171 of the Indian Contract Act, 1872, only banks that hold your deposit accounts have general lien rights.
Navi Finserv is an NBFC, not a bank. It does not hold customer bank accounts. Therefore, Navi cannot freeze accounts in other banks or block your salary. To touch your bank funds, Navi must first win a civil suit and get a signed court order from a judge.
Stop Account Freeze Threats:If an agent says Navi will freeze your SBI or HDFC account, ask for the court order number. No NBFC can freeze external bank accounts without a signed court order.
5. Digital Lending Guidelines (DLG) & Borrower Privacy Shield
The RBI Master Directions on Digital Lending (September 2022) give you strict privacy rights against aggressive loan apps:
No Contact Scraping: Loan apps cannot read your phone contact list, call logs, SMS, or photo gallery. They can only ask for one-time camera and location checks for KYC.
No Third-Party Calls: Agents cannot call your relatives, friends, or boss about your unpaid loan.
Agent ID Required: Lenders must share the names of recovery agencies in advance. Visiting agents must show official ID cards.
Strict Calling Hours: Recovery calls and home visits are allowed only between 8:00 AM and 7:00 PM.
If an agent calls your family or threatens you online, save call audio and chat photos. Filing an RBI complaint puts heavy pressure on the lender.
6. Section 25 PSS Act Digital NACH e-Mandate Summons Defense
Navi loans use electronic auto-debits (e-NACH). When an EMI bounces due to low funds, lenders send legal notices citing Section 25 of the Payment and Settlement Systems (PSS) Act, 2007.
Agents falsely claim this notice is an arrest warrant. Section 25 treats electronic mandate bounces like cheque bounces under Section 138 of the Negotiable Instruments Act. It is a commercial matter, not an immediate crime.
The lender must send a written notice within thirty days of the bounce. You get fifteen days to pay or reply. Even if a court issues summons, the case is bailable and compoundable. Police cannot arrest you for an auto-debit bounce without a court warrant.
7. Rebutting Fast-Track Sole Arbitration (Perkins Eastman Rule)
Navi loan contracts name Bengaluru for fast arbitration. When you miss EMIs, Navi sends notices stating it has picked a sole arbitrator to decide the case.
Under Supreme Court rulings in TRF Ltd. and Perkins Eastman (2020), a lender cannot choose an arbitrator on its own. Under Section 12(5) of the Arbitration and Conciliation Act, 1996, any arbitrator picked by one side without your written agreement has zero legal power.
An order from an arbitrator picked by only one party cannot be enforced under Section 36 of the Arbitration Act. Sending a written objection under Section 12(5) stops these one-sided arbitration threats.
8. Navi Home Loans: Digital Mortgages & SARFAESI Realities
Unlike unsecured personal loans, Navi home loans are backed by real estate mortgages. If a home loan defaults, different legal rules apply.
Under the SARFAESI Act, 2002, Navi Finserv can issue a Section 13(2) demand notice giving you sixty days to clear overdue installments. If unpaid, they can issue a Section 13(4) notice to take symbolic possession of the house.
You have the right to file a written objection within fifteen days under Section 13(3A). You can also challenge illegal possession actions before the Debt Recovery Tribunal (DRT) under Section 17 of the SARFAESI Act.
9. The Multi-Year NPA Reality: When Can a Navi Loan Actually Settle?
While Navi denies loan settlements in the first 90 to 180 days, bad loan accounting rules force changes over time:
Early Delinquency (1 to 180 Days): Zero discounts. Navi demands 100% principal and late fees.
Hardened Default (360+ Days): At this stage, loans become loss assets. Keeping call centers on old accounts becomes too costly.
ARC Debt Sale: Navi bundles old non-paying accounts and sells them at deep discounts to Asset Reconstruction Companies (ARCs). ARCs buy debt cheaply and readily approve 50% to 70% discounts to close files.
If your Navi loan is over one year old, check if it was sold to an ARC. Negotiating with an ARC yields much deeper discounts than talking to app telecallers.
10. Resolving Navi Loan Disputes via National Lok Adalat Benches
National Lok Adalat is the safest place to close a defaulted Navi loan. Held every quarter across India by the National Legal Services Authority (NALSA), Lok Adalat offers dispute talks under the Legal Services Authorities Act, 1987.
Senior Navi officers attend these sessions. Judges act as neutral helpers who review your hardship and encourage fair settlements, including big waivers on late interest and fees.
A Lok Adalat order acts as a final civil court decree under Section 21 of the Legal Services Authorities Act. It is binding on both sides and cannot be challenged in appeal. Settling through Lok Adalat gives you complete legal safety against future recovery calls.
Recovery call agents often send fake legal notices, share photos of police stations on WhatsApp, and threaten home visits.
Follow these simple steps to protect yourself:
Ignore Fake Urgency: Know that call centers use web phone numbers and pre-written scripts to cause fear.
Demand Agent ID: Under RBI rules, ask visiting agents for their name, employee ID, agency name, and authorization letter from Navi. An agent without papers has no right to enter your home.
Record Everything: Turn on call recording on your phone. Keep copies of WhatsApp chats, voice notes, and text messages as proof.
Never Pay Personal Accounts: Never send money to personal UPI IDs, QR codes, or agent bank accounts. Pay only through the official Navi app or verified Navi Finserv bank accounts.
If recovery agents use abuse, threats, or social shaming, you have strong criminal law protection under the Bharatiya Nyaya Sanhita (BNS, 2024):
Section 351 BNS (Criminal Intimidation): Threatening a borrower with harm to person or reputation to force loan payments is a criminal offense punishable by jail time.
Section 308 BNS (Extortion): Putting a borrower in fear of harm to take money is extortion.
Section 352 BNS (Intentional Insult): Using abusive language to provoke a breach of peace is punishable.
Supreme Court Prakash Kaur Precedent: In ICICI Bank vs. Prakash Kaur (2007), the Supreme Court ruled that lenders cannot use musclemen or force to collect loans.
When agents break these laws, file a written police complaint and report them on the National Cyber Crime Portal (cybercrime.gov.in).
13. The 4-Tier Navi Escalation Matrix: Bypassing Automated Bots
App chat support is useless for serious complaints. Send your complaint through this four-step official channel:
Step 1: Grievance Redressal Officer (NBFC Desk): Email the Grievance Officer at gro.navifinserv@navi.com. State your loan number and attach call recordings or chat proof.
Step 2: Principal Nodal Officer: If unresolved after 14 days, email the Principal Nodal Officer at nodaloffice@navi.com at Navi Finserv Head Office, Vaishnavi Tech Square, Iballur Village, Begur Hobli, Bengaluru - 560102.
Step 3: RBI Integrated Ombudsman: If the NBFC does not fix the issue within thirty days, lodge a complaint with the RBI Ombudsman at cms.rbi.org.in or call toll-free 14448.
Step 4: National Cyber Crime Portal: For threats about contact list calls, fake photos, or extortion, file an online report at cybercrime.gov.in.
Navi personal loan defaults drop your CIBIL score by 80 to 160 points. Rebuilding your credit requires disciplined financial steps:
Open a Secured FD Credit Card: Place a fixed deposit of ₹20,000 to ₹30,000 with a bank like IDFC FIRST, Kotak, or ICICI to get a secured credit card without income proof.
Keep Credit Utilization Low: Spend less than 30% of your credit limit each month.
Pay Bills in Full: Never pay only the minimum balance. Clear your statement balance on time every month.
Avoid New Loan Inquiries: Do not apply for new digital personal loans while rebuilding credit.
Following this secured credit card plan rebuilds your CIBIL score back above 750 within 18 to 24 months.
⚖️ Grievance Escalation Hierarchy
Navi Finserv 4-Tier Regulatory Escalation Matrix
When automated AI bots and third-party recovery telecallers ignore your hardship or deploy unlawful pressure, escalate systematically through these statutory channels.
Tier 1: Grievance Redressal Officer (GRO)SLA: 7 Days
Contact the designated compliance officer to log a formal dispute ticket regarding recovery agency harassment or calculation errors.
Tier 3: Reserve Bank of India (RBI) OmbudsmanStatutory Regulator
If Navi fails to resolve recovery harassment within 30 days or breaches Digital Lending Guidelines, file a statutory complaint under the RBI Integrated Ombudsman Scheme.
Portal: cms.rbi.org.inToll-Free: 14448
Tier 4: National Cyber Crime Reporting PortalLaw Enforcement
For abusive WhatsApp threats, unauthorized photo access, or extortion under Section 308/351 BNS, submit an immediate cybercrime complaint.
Portal: cybercrime.gov.inHelpline: 1930
Click to copy a formal legal grievance notice pre-formatted for email escalation to the Principal Nodal Officer and the Reserve Bank of India.
15. Navi Finserv Default & Settlement FAQs
Verified answers on Navi Finserv loan default, recovery limits, and credit rebuilding.
Does Navi Finserv offer loan settlement or One-Time Settlement (OTS)?▼
No. Navi Finserv is one of only three lenders in India (along with Kissht and Si Creva) that strictly does NOT offer loan settlement or OTS discounts. It operates on zero allocated settlement funds and enforces a 100% principal recovery mandate. Any claim that other banks or fintechs (like KreditBee, Bajaj, or Muthoot) refuse settlements is incorrect—other lenders do offer standard 35% to 60% OTS, but Navi strictly does not.
Why is recovery agent harassment so high for defaulted Navi loans?▼
Because Navi does not offer loan write-offs or settlements, outside call agencies face huge pressure to collect 100% of the loan. This pressure causes telecallers to use harsh tactics, daily robocalls, and rude WhatsApp voice notes.
Can Navi recovery agents legally freeze my savings or salary account?▼
No. Under Section 171 of the Indian Contract Act, only banks that hold your deposit accounts have general lien rights. Navi Finserv is an NBFC, not a bank. It cannot freeze outside bank accounts or stop your salary without a court order.
What regulatory action did the RBI take against Navi Finserv in October 2024?▼
On October 17, 2024, the Reserve Bank of India ordered Navi Finserv to stop giving new loans under Section 45L of the RBI Act. The RBI cited very high interest rates and breaks in the Fair Practices Code.
What should I do if I receive a Section 25 PSS Act notice from Navi?▼
A Section 25 notice under the Payment and Settlement Systems Act covers bounced e-NACH auto-debits. It is not an arrest warrant. You get 15 days to reply. The offense is bailable and compoundable. Police cannot arrest you for an auto-debit bounce.
Are fast-track sole arbitration notices from Navi legally enforceable?▼
No. Under Supreme Court rulings in TRF Ltd. and Perkins Eastman, a lender cannot pick an arbitrator on its own. Under Section 12(5) of the Arbitration Act, any arbitrator chosen by only one party without your consent has zero legal authority.
Can Navi recovery agents contact my family members or colleagues?▼
No. Under RBI Digital Lending Guidelines, recovery agents cannot read your phone contact list or call your family, friends, or boss about your unpaid loan. Doing so breaks central bank rules.
How can I settle my defaulted Navi loan through National Lok Adalat?▼
When defaulted loans reach pre-litigation stage, they can be referred to quarterly National Lok Adalat drives under NALSA. Settlements passed by a Lok Adalat bench act as a civil court decree under Section 21 of the Legal Services Authorities Act, giving you final legal closure.
How do I file a formal complaint against Navi recovery agent harassment?▼
Bypass app bots and email the Grievance Officer at gro.navifinserv@navi.com and the Principal Nodal Officer at nodaloffice@navi.com with call audio and chat screenshots. If unresolved after 30 days, file an official grievance with the RBI Ombudsman at cms.rbi.org.in or call 14448.
How does a Navi loan default affect my CIBIL score and how do I rebuild it?▼
Navi reports unpaid loans to credit bureaus as Default or Written-Off. This lowers your credit score by 80 to 160 points. You can rebuild your score above 750 in 18 to 24 months by getting a secured credit card backed by a fixed deposit and paying bills on time.
Official Navi Finserv NBFC & RBI Grievance Portals: