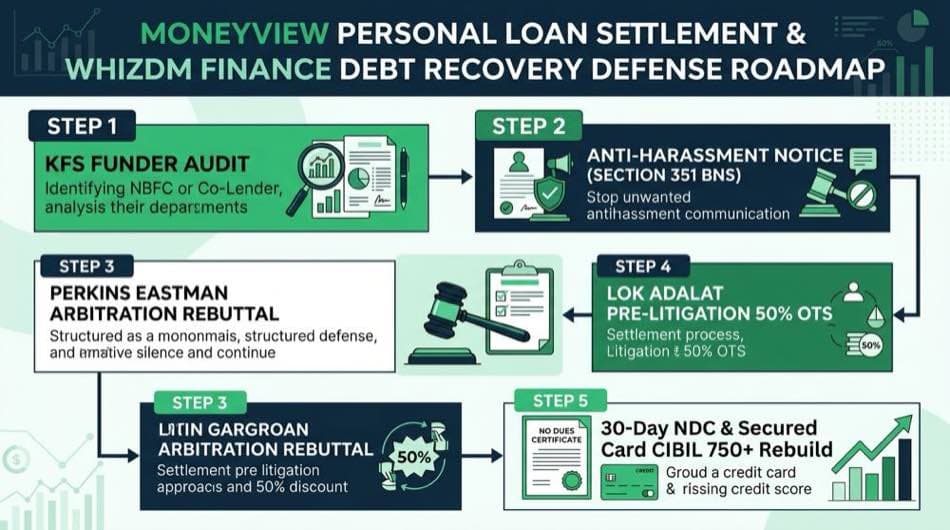
Whizdm Finance Personal Loan Default & Recovery Rules
A clear guide for borrowers who face default on Moneyview loans from Whizdm Finance NBFC or partner lenders.
Visual Roadmap: Five clear steps to settle your Moneyview loan and stop recovery agent threats.
Quick Answer Summary:
Moneyview is an app, not a bank. Whizdm Innovations runs the app, while Whizdm Finance NBFC or co-lenders fund the loans. App chats cannot give discounts. Real settlements (OTS) with 40% to 60% cuts happen only after 180 days past due. Under RBI digital loan rules, recovery agents cannot touch your phone contacts or call your friends.
WHIZDM / MONEYVIEW SETTLEMENT CALCULATOR
Moneyview Loan Settlement Haircut Estimator
Estimate realistic settlement waiver ranges based on loan facility type and default aging.
Unsecured medium-term personal loans underwritten by Whizdm Finance Private Limited or partner banks.
₹2,50,000
₹25,000₹5,00,000₹10,00,000
ESTIMATED SETTLEMENT OUTCOME40% to 60% WAIVER
Target Settlement Range:₹1,00,000 - ₹1,50,000
Projected Debt Relief:₹1,00,000 - ₹1,50,000
Penal Charge Relief: 100% accumulated late fees and penal interest waived in formal OTS
Negotiation Strategy: Audit your KFS to identify whether Whizdm Finance or an external NBFC holds your loan book. File documented proof of job loss or medical emergency to secure 50%+ waivers.
* Estimates based on RBI prudential provisioning norms and empirical fintech compromise trends. Actual settlement values depend on hardship verification and approval by the Whizdm Finance Collections Committee.
1. The Dual-Entity Architecture: Moneyview App vs. Whizdm NBFC
Moneyview is an app, not a bank. It operates through two distinct companies.
Whizdm Innovations Private Limited runs the app as a tech service provider. It handles customer sign-ups and app code. But it does not lend its own money.
Whizdm Finance Private Limited is the actual lender. It is a Non-Banking Financial Company (NBFC) registered with the Reserve Bank of India (Registration No. N-02.00259).
App chat support has no power to settle your loan. Front-line staff cannot give discounts. Only Whizdm Finance or its co-lending partner can approve a One-Time Settlement (OTS). Knowing your lender helps you protect your rights under RBI rules.
App vs. Licensed Lender:Whizdm Innovations builds the software. Whizdm Finance holds the loan. Do not waste time asking app chatbots for fee cuts. They have no legal authority to settle debts.
2. Co-Lending Creditor Audit: Identifying Your Actual Disbursing Funder
Moneyview works with several partner lenders. Your loan may not come from Whizdm Finance alone.
Under RBI digital lending rules, your loan may be funded by one of these licensed lenders:
Whizdm Finance Private Limited
DMI Finance Private Limited
Aditya Birla Finance Limited
Clix Capital Services Private Limited
Cholamandalam Investment and Finance Company
Piramal Capital and Housing Finance
Vivriti Capital Limited
Grow Money Capital Private Limited
Check your Key Fact Statement (KFS) and Sanction Letter. Look for the name of the Disbursing Lender. If DMI Finance or Aditya Birla funded your loan, Whizdm cannot settle it alone. You must settle with the actual lender who holds your loan account.
When an EMI fails, Moneyview starts auto-calling systems. The app sends daily SMS alerts, voice bots, and WhatsApp reminders.
After thirty days of default, accounts move to third-party recovery agencies. Call agents earn commissions based on the money they collect from you. Because they want fast payouts, agents often use aggressive pressure tactics.
Agents may claim that police will arrest you. They may threaten home visits within two hours. They may also send fake legal notices with false court stamps over WhatsApp. An unsecured personal loan default is a civil dispute, not a crime. Threats of police action or jail have no legal backing.
4. Digital Lending Guidelines (DLG) & Anti-Contact-Scraping Shield
Loan apps and recovery agents cannot read your contact list or harass your friends. The RBI Master Directions on Digital Lending (September 2022) give you strict legal shields:
No Contact List Access: Loan apps cannot read your phone contacts, call logs, SMS, or photo gallery. They can only ask for one-time camera and location checks for KYC.
No Calls to Third Parties: Agents cannot call your parents, relatives, friends, or boss about your unpaid loan.
Agent ID Required: Lenders must share the names of recovery agencies in advance. Visiting agents must show official ID cards.
Strict Calling Hours: Recovery calls and home visits are allowed only between 8:00 AM and 7:00 PM.
If an agent calls your family or threatens you on social media, save call audio and chat photos. Filing an official RBI complaint puts heavy pressure on the lender.
5. Inapplicability of Section 171 Banker General Lien to Whizdm NBFC
Recovery agents often claim they will freeze your bank accounts or stop your salary.
This claim is completely untrue. Under Section 171 of the Indian Contract Act, 1872, only banks that hold your savings or current accounts have general lien rights. For example, SBI can hold funds in an SBI savings account for an SBI loan default.
Whizdm Finance is an NBFC, not a bank. It does not hold customer bank accounts. Therefore, Whizdm Finance has zero legal power to freeze accounts in other banks or block your salary. To touch your bank account, Whizdm Finance must first win a civil suit and get an execution order from a court judge.
Stop Account Freeze Lies:If an agent claims that Moneyview will freeze your HDFC or SBI account, ask for the court order number. No NBFC can touch external bank accounts without a signed civil court order.
Moneyview loans use electronic auto-debits (e-NACH). When an EMI fails due to low balance, lenders send legal notices citing Section 25 of the Payment and Settlement Systems (PSS) Act, 2007.
Agents falsely claim this notice is an arrest warrant. Section 25 treats electronic mandate bounces like cheque bounces under Section 138 of the Negotiable Instruments Act. It is a commercial dispute, not a major crime.
The lender must send a written notice within thirty days of the bounce. You get fifteen days to pay or reply. Even if a court issues summons, the case is bailable and compoundable. Police cannot arrest you for an auto-debit bounce without a court warrant.
7. Rebutting Whizdm Bengaluru Sole Arbitration Notices (Perkins Eastman Rule)
Moneyview loan contracts name Bengaluru for fast arbitration. When EMIs default, Whizdm Finance sends notices stating it has picked a sole arbitrator to decide the case.
Under Supreme Court rulings in TRF Ltd. and Perkins Eastman (2020), a lender cannot choose an arbitrator on its own. Under Section 12(5) of the Arbitration and Conciliation Act, 1996, any arbitrator picked by one side without your written agreement has zero legal power.
An order from an arbitrator picked by only one party cannot be enforced under Section 36 of the Arbitration Act. Sending a formal written objection under Section 12(5) stops these one-sided arbitration threats.
8. Moneyview Settlement Stages: 0% Early Concession to 40%–60% NPA Haircuts
Knowing how Whizdm Finance handles bad loans helps you time your settlement for maximum savings:
1 to 30 Days Late (SMA-0): Early default stage. The lender demands full payment and late fees. Settlement requests are rejected.
31 to 60 Days Late (SMA-1): Agency calls begin. Whizdm Finance offers zero discounts at this stage.
61 to 90 Days Late (SMA-2): Approaching NPA status. The lender may offer loan restructuring, but no principal waivers.
180+ Days Late (NPA Loss Pool): At 180 days, RBI rules force the lender to write off the loan on its balance sheet. To recover cash, senior managers can approve One-Time Settlements (OTS) with 40% to 60% principal waivers and 100% late fee cuts.
Starting settlement talks after 180 days puts you in contact with managers who have the authority to grant deep discounts.
When an unsecured loan stays unpaid past 360 days, it becomes a loss asset. At this point, running call centers costs more than the loan is worth.
Whizdm Finance clears these accounts in two ways:
Sale to Asset Reconstruction Companies (ARCs): Whizdm Finance sells pools of bad loans at deep discounts (often 15 to 25 paise per rupee) to licensed ARCs. Because ARCs buy cheap under Section 5 of the SARFAESI Act, they often accept 50% to 70% discounts to close files quickly.
Pre-Litigation Settlement Drives: Special company drives where big write-offs are cleared for old non-paying loans.
If your loan is over one year old, check if it was sold to an ARC. Settling with an ARC usually yields larger discounts than dealing with app telecallers.
10. National Lok Adalat: Pre-Litigation Statutory Compromise Decrees
National Lok Adalat is the safest place to close a defaulted Moneyview loan. Held every quarter across India by the National Legal Services Authority (NALSA), Lok Adalat offers dispute talks under the Legal Services Authorities Act, 1987.
Senior Whizdm Finance officers attend these sessions. Judges act as neutral helpers who review your hardship and encourage fair settlements, including big waivers on late interest and fees.
A Lok Adalat order acts as a final civil court decree under Section 21 of the Legal Services Authorities Act. It is binding on both sides and cannot be challenged in appeal. Settling through Lok Adalat gives you complete legal safety against future recovery calls.
Recovery call agents often send fake legal notices, share photos of police stations on WhatsApp, and threaten home visits.
Follow these simple steps to protect yourself:
Ignore Fake Urgency: Know that call centers use web phone numbers and pre-written scripts to cause fear.
Demand Agent ID: Under RBI rules, ask visiting agents for their name, employee ID, agency name, and authorization letter from Whizdm Finance. An agent without papers has no right to enter your home.
Record Everything: Turn on call recording on your phone. Keep copies of WhatsApp chats, voice notes, and text messages as proof.
Never Pay Personal Accounts: Never send money to personal UPI IDs, QR codes, or agent bank accounts. Pay only through the official Moneyview app or verified Whizdm Finance bank accounts.
If recovery agents use abuse, threats, or social shaming, you have strong criminal law protection under the Bharatiya Nyaya Sanhita (BNS, 2024):
Section 351 BNS (Criminal Intimidation): Threatening a borrower with harm to person or reputation to force loan payments is a criminal offense punishable by jail time.
Section 308 BNS (Extortion): Putting a borrower in fear of harm to take money is extortion.
Section 352 BNS (Intentional Insult): Using abusive language to provoke a breach of peace is punishable.
Supreme Court Prakash Kaur Precedent: In ICICI Bank vs. Prakash Kaur (2007), the Supreme Court ruled that lenders cannot use musclemen or force to collect loans.
When agents break these laws, file a written police complaint and report them on the National Cyber Crime Portal (cybercrime.gov.in).
13. The 4-Tier Moneyview & Whizdm Escalation Matrix (Bypassing Chatbots)
App chat support is useless for serious complaints. Send your complaint through this four-step official channel:
Step 1: Grievance Redressal Officer (NBFC Desk): Email Mr. Gagan Nanda, Grievance Redressal Officer of Whizdm Finance, at gr@whizdmfinance.com or customercare@whizdmfinance.com (Phone: 080-6566-1137 / 080-6566-1032). Give your loan number and attach call recordings or chat proof.
Step 2: Principal Nodal Officer: If unresolved after 14 days, email the Principal Nodal Officer at Whizdm Finance headquarters, 17/1, 3rd Floor, The Address Building, Outer Ring Road, Marathahalli, Bangalore - 560103 (grievance@moneyview.in).
Step 3: RBI Integrated Ombudsman: If the NBFC does not fix the issue within thirty days, lodge a complaint with the RBI Ombudsman at cms.rbi.org.in or call toll-free 14448.
Step 4: National Cyber Crime Portal: For threats about contact list calls, fake photos, or extortion, file an online report at cybercrime.gov.in.
Never pay money without checking the settlement letter first. Follow these safety rules:
Check Letterhead: The letter must come on official Whizdm Finance Private Limited letterhead. If an external partner funded the loan, it must come on their letterhead.
Verify Loan Details: Check that your name, loan number, PAN, and settlement amount match your records exactly.
Full Discharge Clause: The letter must state that once you pay the agreed sum, all remaining dues are waived in full and no further claims will be made.
Pay Only to the Lender: Transfer money directly through the Moneyview app or into official Whizdm Finance bank accounts. Never pay cash to an agent or send money to a personal UPI ID.
Get a No Dues Certificate: Within thirty days of payment, obtain your formal No Dues Certificate (NDC) and check that your CIBIL status is updated to Settled.
Settling a loan drops your CIBIL score by 75 to 140 points. You can rebuild your credit back above 750 within 18 to 24 months by getting a secured fixed-deposit credit card and paying all bills on time.
When automated chatbots and outsourced telecallers ignore your hardship or deploy unlawful pressure, escalate systematically through these statutory channels.
Tier 1: Whizdm Finance Grievance Redressal Officer (NBFC)SLA: 7 Days
Contact Mr. Gagan Nanda, Grievance Redressal Officer of Whizdm Finance Private Limited.
Tier 3: Reserve Bank of India Integrated OmbudsmanSTATUTORY ARBITRATION
File an official complaint if Whizdm Finance fails to resolve recovery harassment or provide sanction verification within 30 calendar days.
Portal: cms.rbi.org.inToll-Free: 14448
Tier 4: National Cyber Crime Portal & Police StationCRIMINAL REMEDY
Immediate criminal recourse for threats involving leaked contacts, morphed photos, or extortion under Section 351 BNS.
Portal: cybercrime.gov.inHelpline: 1930
Formal Dispute Representation Notice:
Copy this pre-drafted statutory notice, insert your loan details, and email it to the Whizdm Grievance Officer and Nodal Desk to establish a legal paper trail.
15. Moneyview Loan Default & Settlement FAQs
Verified answers on Moneyview personal loan default, recovery limits, and credit rebuilding.
Can I settle my Moneyview personal loan directly through the mobile app?▼
No. The Moneyview app does not offer settlement discounts. Whizdm Innovations runs the app as a service platform. All One-Time Settlements must be approved by Whizdm Finance or your co-lending partner.
Who actually funds loans taken on Moneyview?▼
Loans on Moneyview come from Whizdm Finance NBFC or co-lending partners like DMI Finance, Aditya Birla, Clix Capital, and Piramal. Check your Key Fact Statement to see your exact lender.
Can Moneyview recovery agents legally contact my relatives or friends?▼
No. Under RBI Digital Lending Guidelines, lending apps and recovery agents cannot read your contact list or call third parties about your loan default.
Can Whizdm Finance freeze my external bank accounts or attach my salary?▼
No. Whizdm Finance is an NBFC, not a bank. Under Section 171 of the Indian Contract Act, only deposit-taking banks hold lien rights. An NBFC cannot freeze external accounts without a civil court order.
What should I do if I receive a Section 25 PSS Act legal notice from Moneyview?▼
Section 25 of the PSS Act covers failed electronic auto-debits. It is not an arrest warrant. It is bailable and compoundable. You have fifteen days from notice receipt to reply or start settlement talks.
Is fast-track sole arbitration in Bengaluru initiated by Moneyview legally valid?▼
No. Under Supreme Court rulings in TRF Ltd. and Perkins Eastman, a lender cannot pick an arbitrator on its own. Any unilateral appointment is void under Section 12(5) of the Arbitration Act.
What percentage discount can I negotiate on a defaulted Moneyview loan?▼
Moneyview gives zero discounts in the first 90 days. But accounts past 180 days can get 40% to 60% waivers on total dues once full loss provisioning sets in.
Can I settle my Moneyview loan through National Lok Adalat?▼
Yes. National Lok Adalat sessions happen quarterly under NALSA. Lenders can grant compromise settlements with deep fee waivers. The Lok Adalat award is final and acts as a civil court decree.
How can I verify if a Moneyview settlement letter is genuine?▼
A real letter comes on official Whizdm Finance letterhead. It states your loan number, PAN, exact settlement sum, and a full discharge clause. You must pay only into official lender accounts.
How does settling a Moneyview loan impact my CIBIL credit score?▼
Settling marks your loan as Settled instead of Closed in credit bureau files. This drops your score by 75 to 140 points. You can rebuild your score above 750 in 18 to 24 months with a secured credit card.