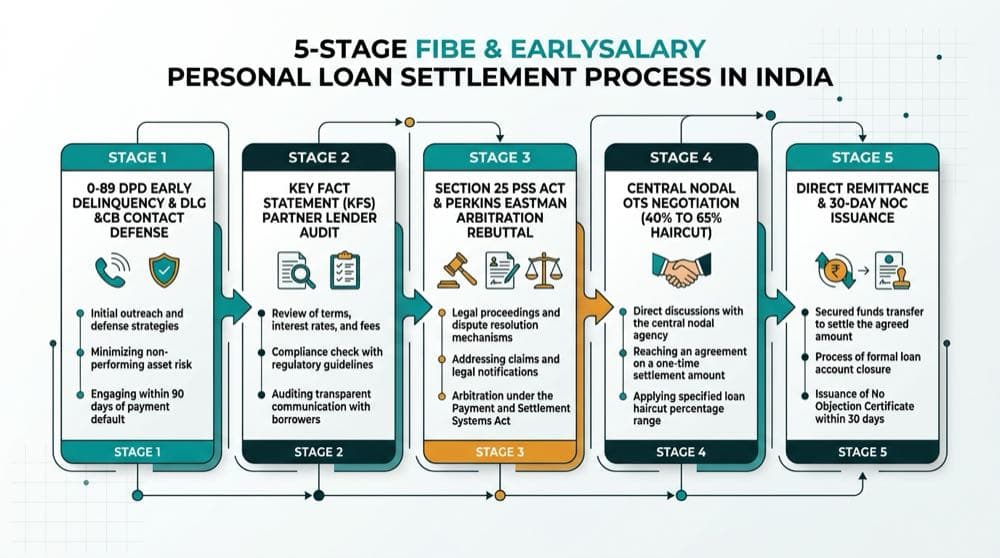
A practical guide for defaulted Fibe instant loans, EarlySalary cash advances, and Axis Bank cards.
Visual Blueprint: 5-stage roadmap from defense to 40% to 65% OTS closure and formal NOC delivery.
Quick Answer Summary
Fibe loans can settle for 40% to 65% of total dues after 180 days of default. Under Section 171 of the Contract Act, Fibe cannot freeze outside bank accounts. Under RBI rules, agents cannot call your family or employers. All valid settlements require a signed letter from EarlySalary Services Private Limited.
Empirical CalculatorUNSECURED 180+ DPD
Fibe Settlement & Haircut Estimator
Calculate realistic settlement waiver ranges based on Fibe and EarlySalary recovery guidelines.
Unsecured personal loans up to ₹5,00,000 funded by EarlySalary Services NBFC. Accounts past 180 days qualify for 40% to 65% OTS waivers.
₹1,00,000
₹10,000₹2,50,000₹5,00,000
Estimated OTS Haircut:45% to 60% DISCOUNT
Target Settlement₹40,000 to ₹55,000
Estimated Savings₹45,000 to ₹60,000
✓Automatic Waiver: 100% waiver of late fees, bounce charges, and penal interest.
Negotiation Rule for Fibe Personal Loan:Never settle over a phone call. Demand an official letter on EarlySalary Services letterhead. Check for a verified settlement ID.
Grievance Escalation Hierarchy
Fibe & EarlySalary 4-Tier Escalation Matrix
Do not waste time with chatbots. Escalate your debt dispute directly through these verified statutory channels.
Tier 1: Customer Care Support DeskSLA: 7 Days
File your first grievance ticket here. Ask for a formal review of your loan hardship.
Email: care@fibe.inPhone: 020-67639797
Tier 2: Grievance Redressal Officer (GRO) & PNOSLA: 14 Days
Send your dispute to the Principal Nodal Officer. Report agent abuse and request an OTS waiver.
Officer: Mr. Amit NosinaEmail: grievance@earlysalary.comDirect Line: 020-67639797Address: Unit No. 404, The Chambers, Viman Nagar, Pune, Maharashtra 411014
Tier 3: Partner NBFC Nodal DeskSLA: 30 Days
Check your KFS statement for partner lenders. Escalate to Northern Arc, InCred, or HDB if they funded your loan.
Procedure: Check designated lender in your Key Fact Statement (KFS)Requirement: Demand co-lender formal concurrence on settlement waiver
If Fibe does not resolve your case in 30 days, file an online complaint with the RBI.
CMS Portal: cms.rbi.org.inToll-Free: 14448
Official Formal Dispute Representation Template
Copy this notice. Email it to grievance@earlysalary.com. Demand an immediate end to recovery calls.
01. Fibe Corporate Reality: Social Worth Tech & EarlySalary NBFC
Fibe runs through two distinct firms. Social Worth Technologies Limited owns the mobile app and website. Its CIN is U72200PN2015PLC157014. This tech firm signs up users. It builds app code. But it holds no RBI license to lend money. Real loan funds come from an RBI-registered NBFC. That NBFC is EarlySalary Services Private Limited. Its CIN is U67120PN1994PTC184868.
This split is vital during debt settlement talks. In-app chat agents cannot cut your balance. They lack legal power to waive penal interest. Any valid One-Time Settlement (OTS) requires a formal sanction letter. That letter must come directly from EarlySalary Services Private Limited.
Corporate Entity Summary:Platform operator: Social Worth Technologies Limited (CIN: U72200PN2015PLC157014). Balance sheet NBFC: EarlySalary Services Private Limited (CIN: U67120PN1994PTC184868). Valid settlement letters must come from EarlySalary Services.
02. The Multi-Lender Network: Inspecting Your Key Fact Statement (KFS)
Fibe works with several lending partners. Your loan may come from an outside lender. Partners include Northern Arc, InCred, HDB, and Vivriti Capital.
Under RBI rules, lenders must give you a Key Fact Statement. This form names your true lender. If Northern Arc funded your loan, Fibe cannot settle it alone. Your settlement letter must name the lender in your statement.
Mandatory Action: Check Your KFSOpen your original loan email from Fibe. Look for the Key Fact Statement table. Check if your loan belongs to EarlySalary Services, Northern Arc, InCred, HDB, or Vivriti Capital before paying.
HDB Financial Services Ltd:HDFC Bank Subsidiary NBFC
Vivriti Capital Ltd:Enterprise Debt Partner
03. Why Section 171 Banker's General Lien Does NOT Apply to Fibe NBFC
Under Section 171, only regular banks hold lien rights. A bank can deduct funds to clear a debt. But EarlySalary Services is an NBFC. It does not hold your deposits.
An NBFC cannot freeze your outside bank account. It cannot attach your salary without a court order. If an agent threatens to freeze your account, ignore the threat. Your savings in your regular bank remain safe.
Statutory Fact: No Account Freezing AuthorityEarlySalary Services Private Limited is an NBFC, not a deposit bank. It has zero power under Section 171 to place a lien on your salary account. Threats to freeze external accounts violate Indian law.
04. The RBI Digital Lending Guidelines (DLG) Shield: Stopping Harassment
The RBI Digital Lending Rules set strict collection limits. Apps cannot copy your phone contacts. They cannot view your photos or social media. Any threat to call your friends, parents, or coworkers is illegal.
Agents can only call between 8:00 AM and 7:00 PM. They cannot send rude WhatsApp messages. They cannot call your boss. If agents break these rules, save call recordings and screenshots. Send this proof to the Fibe Nodal Officer. Also file a complaint on the RBI Sachet portal.
Calling your phone contacts or workplace is strictly banned under RBI rules.
Calls are only allowed between 8:00 AM and 7:00 PM.
Agents must show an official ID card and bank letter.
Report abusive messages directly to the RBI Sachet portal (sachet.rbi.org.in).
05. Rebutting Unilateral Sole Arbitration Under Perkins Eastman & Section 12(5)
Digital lenders often send automated arbitration notices. These notices claim a private arbitrator will hear your case. But the lender cannot pick an arbitrator alone. The Supreme Court confirmed this rule in Perkins Eastman and TRF Ltd.
Under Section 12(5) of the Arbitration Act, a unilateral appointment has no legal force. Any order passed is void. If you receive a notice, object in writing under Section 12(5). Cite the Perkins Eastman ruling to protect your rights.
Statutory Defense Rule:Any arbitration notice picking a private arbitrator without your agreement is legally void. Object in writing under Section 12(5) citing the Supreme Court Perkins Eastman precedent.
06. Fibe Personal Loans: Delinquency Timelines & 40% to 65% Haircuts
Fibe personal loans are unsecured credit lines. If you miss EMIs, your account moves through overdue stages. The first 90 days are early default. In this stage, collection teams seek full dues. They do not offer discounts.
After 90 days, the loan becomes an NPA. The lender must set aside capital reserves for the bad debt. Between 90 and 180 days, you can negotiate 25% to 40% waivers. Past 180 days, EarlySalary approves 40% to 65% OTS waivers. They also cancel 100% of penal interest and late fees.
Empirical Haircut Benchmarks:
• 0 to 89 DPD: 0% waiver. The focus is on EMI tenure extension.
• 90 to 179 DPD: 25% to 40% waiver for proven financial hardship.
• 180 to 365 DPD: 40% to 55% waiver plus full fee cancellation.
• 365+ DPD: 50% to 65% waiver for written-off debt.
07. Fibe Axis Bank Credit Card: Unraveling Bank Liability vs FinTech Desks
Many borrowers confuse the Fibe Axis Bank Credit Card. You view the card inside the Fibe app. But Axis Bank issues and owns the card debt. Fibe acts only as a tech partner. Fibe staff have no authority to settle card debt.
You must negotiate directly with Axis Bank. The card file goes to the Axis Bank SAMB desk. You can settle the debt at a discount. Make sure your settlement letter comes from Axis Bank Limited.
Critical Entity Warning:Never pay settlement money for a Fibe Axis Bank card into a Fibe account. Card settlements must be signed by Axis Bank and paid to your 16-digit card number.
Resolution Desk Comparison:
Fibe Personal LoanLender: EarlySalary Services NBFC. Settled by Pune Central Nodal Desk.
Fibe Axis Credit CardLender: Axis Bank Ltd. Settled by Mumbai Axis Bank SAMB Desk.
When auto-debits bounce, lenders send Section 25 PSS Act demand notices. Section 25 treats bounced auto-debits like bounced cheques under Section 138. You get 15 days to respond and clear the dues.
These are bailable recovery cases, not sudden arrest warrants. If a summons arrives, appear with a lawyer to get bail. Ask the judge to refer the case to Lok Adalat for an agreed settlement.
Courtroom Fact:A Section 25 notice gives you 15 days to answer. If a summons arrives, you can get bail easily and ask the court for an amicable settlement at Lok Adalat.
09. Countering Field Recovery Agents Under Bharatiya Nyaya Sanhita (BNS 351)
Lenders may send field agents to your home. In ICICI Bank v. Prakash Kaur (2007), the Supreme Court banned muscle tactics and threats.
Under Bharatiya Nyaya Sanhita (BNS), recovery abuse is a crime. Threatening you is criminal intimidation under Section 351 BNS. Entering your home without consent is trespass under Section 329 BNS. Always ask for an agent ID card and record any threats.
Statutory Shield (BNS 2024):Any visiting collection agent must present an official letter from EarlySalary Services. Threatening language can be prosecuted under Section 351 BNS.
10. Settle Legally Through National Lok Adalat: Conciliation Decrees
The safest way to settle a Fibe loan is through National Lok Adalat. NALSA organizes Lok Adalat four times a year across India. Judges and senior lawyers preside over the panels.
Settling at Lok Adalat offers two major benefits. You can secure waivers of 50% to 65% on total dues. Under Section 21 of the Legal Services Act, a Lok Adalat award acts as a court decree. It is final and protects you from any future collection claims.
Lok Adalat Decree Advantage:Under Section 21 of the Legal Services Authorities Act, a Lok Adalat award acts as a court decree. Fibe or any ARC cannot reopen the debt ever again.
11. Direct Grievance Escalation: Reaching Amit Nosina (GRO / PNO)
In-app chatbots and general email desks give only automated replies. They cannot grant settlement discounts. To get real relief, escalate directly to the Principal Nodal Officer.
The Nodal Officer for EarlySalary Services is Mr. Amit Nosina. Send your hardship letter to grievance@earlysalary.com. If unresolved in 30 days, file a complaint on the RBI CMS portal.
Official Nodal Desk Contact:
• Officer: Mr. Amit Nosina (GRO & Principal Nodal Officer)
• Office: Unit No. 404, The Chambers, Viman Nagar, Pune, Maharashtra 411014
12. Forensic Settlement Letter Checklist: 7 Mandatory Checkpoints
Never pay money based on phone calls or WhatsApp messages. Without a signed letter, your money goes to late fees. Check your sanction letter against these 7 checkpoints before paying:
1. Official Letterhead: Check the letterhead. It must show EarlySalary Services Private Limited or your KFS lender. Check the CIN number.
2. Exact Loan Details: Check your loan details. Your name, phone number, and loan account must match your contract.
3. Clear Settlement Sum: Check the settlement sum. The agreed amount must appear in both figures and words.
4. Full Waiver Clause: Check the waiver terms. The letter must state that all remaining dues and late fees are waived.
5. Exact Due Date: Check the due date. It must give the exact date to make your payment.
6. NOC Delivery Timeline: Check the NOC timeline. It must state that your No Dues Certificate will arrive within 30 days.
7. Authorized Signature: Check the signature. It must carry an official signature and company seal.
Never pay cash to collection agents. Agents have no right to collect physical cash for EarlySalary Services. Any cash given to agents disappears. Your loan will remain unpaid on official records.
Always pay through official channels. Pay inside the official Fibe mobile app. You can also pay via NEFT or RTGS to your Virtual Account Number. Always save your bank UTR receipt as legal proof.
Zero-Cash Rule:Never send funds to personal UPI IDs or hand over cash. Pay only inside the official Fibe app or via bank transfer to EarlySalary Services Private Limited.
14. Post-Settlement Credit Rehabilitation: From Settled to 750+ CIBIL
Settling a loan clears your debt. But it leaves a mark on your credit history. The lender reports the loan to CIBIL as SETTLED. This mark lowers your credit score at first.
You can rebuild your credit score step by step. First, verify your zero-balance status in 30 days. Then open a secured card backed by a fixed deposit. Keep your card usage below 30 percent. Pay your bill on time every month. Your CIBIL score will cross 750 in 18 to 24 months.
Score Rehabilitation Roadmap:Get your formal No Dues Certificate within 30 days. Open an FD-backed secured card with a ₹25,000 deposit. Keep usage under 30% and pay on time to rebuild a 750+ score in 18 to 24 months.
Regulatory Answers
15. Fibe & EarlySalary Loan Settlement FAQs
Verified answers regarding Fibe personal loan default, recovery agency boundaries, and credit rehabilitation.
What is the corporate relationship between Fibe, EarlySalary, and Social Worth Technologies?▼
Fibe is the brand name owned by Social Worth Technologies Limited. It runs the app. EarlySalary Services Private Limited is the licensed NBFC. It lends the funds.
Can Fibe or EarlySalary freeze my salary or savings bank account without a court order?▼
No. Section 171 applies only to regular banks. EarlySalary Services is an NBFC. It cannot freeze your bank accounts or salary without a court order.
How much settlement waiver can I negotiate on a defaulted Fibe personal loan?▼
Loans unpaid past 180 days qualify for 40% to 65% waivers on total dues. Lenders also wipe out 100% of penal fees.
Are digital arbitration notices issued by Fibe with a unilaterally appointed arbitrator legally binding?▼
No. Under Perkins Eastman and TRF Ltd rulings, lenders cannot pick a sole arbitrator alone. Under Section 12(5), one-sided awards are void.
What legal protection do I have if Fibe recovery agents contact my friends, family, or employer?▼
Under RBI Digital Lending Rules, apps and agents cannot call your contacts or boss. Report violations to the Fibe Nodal Officer and the RBI Sachet portal.
How do I know whether my loan is funded by EarlySalary or a partner NBFC like Northern Arc or InCred?▼
Open your loan sanction email. Check the Key Fact Statement (KFS). It lists your true lender, such as EarlySalary Services, Northern Arc, InCred, or HDB.
Can Fibe file a criminal case under Section 25 PSS Act or Section 138 NI Act for an unpaid personal loan?▼
Bounced auto-debits trigger Section 25 notices. But debt default is a civil matter. You can get bail on the same day in court and settle.
How does settlement work for the co-branded Fibe Axis Bank Credit Card?▼
Axis Bank Limited owns the card debt, not Fibe. Fibe staff cannot settle card accounts. You must negotiate directly with the Axis Bank SAMB desk.
What are the mandatory checkpoints to verify an authentic Fibe settlement sanction letter?▼
A valid letter uses EarlySalary Services letterhead with CIN U67120PN1994PTC184868. It shows your loan number, settlement amount, and NOC delivery date.
How long does Fibe take to issue a No Dues Certificate (NOC) and update credit bureau records?▼
Under RBI rules, lenders must give you a No Dues Certificate within 30 days. They must also update CIBIL and other bureaus in 30 days.
Official Statutory Grievance Portals & Regulatory Sources: