HomeAbout
BlogSoon
Bank specific setupSoon
LocationsSoon
WARNING: THIS IS NOT LEGAL ADVICE. THIS IS SURVIVAL ADVICE BASED ON REAL BORROWER EXPERIENCE.
UPDATED: SEPTEMBER 2026

Federal Bank Loan Settlement Process & OTS Rules in India

How to Settle Federal Personal, Card & NRI Debt

Headquartered in Kerala, Federal Bank settles bad loans through its branch teams and Stressed Assets Recovery Branches (SARB). Learn how to negotiate an OTS discount, protect NRI savings from Section 171 banker's lien, and get a safe court order at Lok Adalat.

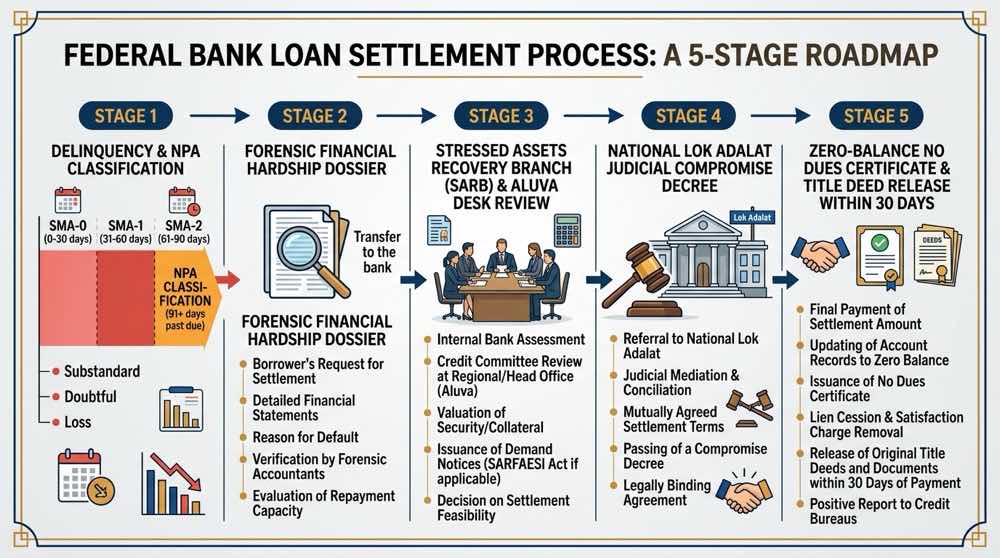
Federal Bank Loan Settlement Process and OTS Debt Relief Roadmap

Figure 1: Official settlement hierarchy and SARB compromise procedure across Federal Bank branches and recovery offices.

Quick Answer Summary

You can settle Federal Bank personal loans, FedMobile debts, credit cards, and gold loan shortfalls through its Stressed Assets Recovery Branches (SARB). Borrowers in financial hardship can get a 100% waiver on late fees and interest. You can also get a 35% to 55% discount on loan principal (and 40% to 65% on credit cards). Beware of Section 171 banker's lien. The bank can freeze your linked NRE or NRO accounts if you default. Settle at National Lok Adalat to receive an order under Section 21 of the Legal Services Authorities Act. This closes all Section 138 cheque bounce and Section 25 NACH court cases for good.

1. Federal Bank Settlement Landscape & Retail Framework

The Federal Bank Limited is a major private bank based in Aluva (Kochi), Kerala. It is well known for retail banking, NRI remittances, and gold loans. In recent years, the bank grew rapidly in digital lending. Through its FedMobile app and credit card partnerships, it gave out thousands of instant personal loans across India.

When unexpected setbacks happen - such as job loss, salary cuts, business slowdowns, or medical emergencies - borrowers struggle to pay high interest rates.

Federal Bank follows strict rules to resolve bad debts. It does not act like aggressive illegal lending apps. Understanding how the bank works helps you negotiate a legal One-Time Settlement (OTS) with real savings.

2. Statutory Framework: RBI Master Directions & SARFAESI

Compromise settlements at Federal Bank follow clear legal rules. Knowing these rules protects you from unfair pressure from recovery teams:

RBI Master Direction on Compromise Settlements (2023)

Under RBI circular RBI/2023-24/40, every bank must have a clear settlement policy. The bank can legally waive interest and reduce loan principal for Non-Performing Assets (NPAs). They can do this without going to court.

SARFAESI Act, 2002 & Kerala Judicial Precedents

For home loans, Federal Bank uses Section 13(2) (demand notice) and Section 13(4) (possession notice). The Kerala High Court ruled in S. Radhakrishnan v. Federal Bank that banks must review your hardship reply under Section 13(3A) before taking your home through the Chief Judicial Magistrate (CJM).

Section 138 Negotiable Instruments Act & Section 25 PSS Act

When an EMI cheque or NACH auto-debit bounces, banks often file court cases. They use these notices to push you to pay. When you sign an OTS and pay the agreed amount, the bank withdraws all Section 138 and Section 25 cases from court.

3. Internal Recovery Desks: Branch Operations vs SARB

Federal Bank divides recovery work based on your loan amount and delay time:

Branch-Level Recovery & Collections

For small delays (1 to 89 days) and loans under ₹5 lakh, local branch managers handle your file. They can remove late payment charges or give you more time. But local branch managers cannot write off your principal loan balance.

Stressed Assets Recovery Branches (SARB)

When an unpaid loan crosses 90 days, it moves to a specialized SARB office. Federal Bank has SARB offices in Ernakulam, Kozhikode, Thiruvananthapuram, Chennai, Bengaluru, Mumbai, and New Delhi. Senior officers (AGMs and DGMs) here have the power to approve deep OTS discounts.

4. Loan Products Breakdown & Realistic Haircuts (35% to 65%)

Settlement discounts depend on your loan type and collateral:

Loan FacilityCollateral StatusInterest / Penal WaiverExpected Principal Haircut
FedMobile Personal LoanUnsecured100% Waiver35% - 55%
Federal Credit CardsUnsecured100% Finance Charges40% - 65%
NRI Clean AdvanceUnsecured / Cross-Lien100% Penal Interest25% - 45%
MSME / Gold Loan ShortfallDeficit Post-Auction100% Penal Interest50% - 75%
Housing Loan (Mortgage)Secured Real EstatePartial Penal Waiver0% - 15% (Rare)
  • Penal Interest & Late Fees: Federal Bank routinely waives 100% of all penalty charges.
  • Unapplied Interest: Once an account becomes an NPA under RBI rules, the bank stops counting interest as income. Waiving this unapplied interest costs the bank nothing.
  • Principal Haircut: For unsecured loans unpaid for more than a year, Federal Bank usually agrees to a 45% to 65% discount on the core principal, especially for single lump-sum payments.
⚡ Empirical CalculatorUNSECURED NPA

Federal Bank Settlement & Haircut Estimator

Calculate realistic One-Time Settlement (OTS) compromise ranges based on Federal Bank SAMD recovery metrics and Lok Adalat guidelines.

Unsecured personal advance disbursed via FedMobile / branch channels. Accounts past 90 DPD move to SAMD recovery branch.

₹3,50,000
₹25,000₹25,00,000₹50,00,000
Target Settlement Offer:50%–65% Haircut
Realistic Settlement Range:₹1,22,500₹1,75,000
Estimated Debt Forgiven:₹1,75,000₹2,27,500
*100% penal interest and late payment charges waived under Federal Bank compromise norms.
⚠️
Federal Bank Recovery Caveat:Federal Bank enforces Section 171 Banker's Lien on any existing NRE/NRO or resident savings accounts. Drain operational balances before entering compromise negotiations.

5. Section 171 Banker's General Lien: NRI & Remittance Defense

A major risk with Federal Bank defaults is Section 171 of the Indian Contract Act, 1872 (Banker's General Lien). Federal Bank links all accounts through your PAN and Customer Identification File (CIF).

Immediate Defense Actions for Federal Bank Borrowers:

  • If you miss payments on a FedMobile loan or credit card, the bank can freeze your linked savings, NRE, or NRO accounts. They can deduct your balance toward loan dues.
  • Joint accounts where you are a secondary holder can also face sudden freezes.
  • Move your salary, business money, and Gulf remittances to a different bank before your loan crosses 60 days of delay.

The bank can only freeze accounts that share your name and CIF. They cannot touch money belonging solely to your spouse or parents without a legal order. If they do, you can complain to the Banking Ombudsman.

6. Harassment Defense (BNS Code) & National Lok Adalat Compromise

Third-party recovery agencies often break RBI guidelines. If an agent threatens you, visits your home without permission, or calls your office, take these immediate steps:

1. Mandatory Verification & Time Limits:

Every recovery agent must carry an official ID card and authorization letter from Federal Bank. Agents can only call or visit between 8:00 AM and 7:00 PM.

2. Criminal Complaint under Bharatiya Nyaya Sanhita (BNS), 2023:

Abusive phone calls or threats constitute criminal offenses under Section 351 (Criminal Intimidation) and Section 356 (Defamation) of BNS, 2023. File an immediate police complaint and email a copy to Federal Bank's Principal Nodal Officer.

3. National Lok Adalat Judicial Decrees:

An award passed by a National Lok Adalat carries the force of a civil court decree under Section 21 of the Legal Services Authorities Act, 1987. It legally compounds all Section 138 NI Act or Section 25 PSS Act complaints permanently with zero court fees.

7. Sanction Audit, Direct CBS Remittance & 30-Day NDC SLA

Navigating a Federal Bank settlement from proposal to complete legal closure:

1. Formal Sanction Letter on Bank Letterhead

Never pay based on verbal promises or WhatsApp messages. Ensure your settlement letter is on official Federal Bank letterhead with a unique reference code, settlement amount, due date, and authorized AGM signature.

2. Direct CBS Account Remittance

Deposit funds directly into your loan account using NEFT, RTGS, or at the branch counter. Never pay cash to third-party recovery agents.

3. Statutory 30-Day NDC SLA (RBI/2023-24/60): Under RBI rules, Federal Bank must deliver your No Dues Certificate and return all original documents within 30 days of full payment. Any delay beyond 30 days entitles you to ₹5,000 daily compensation.

4. CIBIL Rebuilding Strategy Post-Settlement

After reporting as 'Settled' with ₹0 balance, rebuild your credit score above 750 within 18 to 24 months by maintaining a low-utilization secured credit card against a fixed deposit.

Tier 1Branch Manager & 24-Hour Contact Center
SLA: 7 Working Days

Authority: Frontline Customer Service

Contact: Toll-free: 1800-425-1199 / 1800-420-1199 | Email: contact@federalbank.co.in

Jurisdiction: Handles factual ledger balance errors, initial compromise requests, and branch service issues.

Tier 2Nodal Officer (Internal Escalation)
SLA: 7 - 10 Working Days

Authority: Nikhil A. (Associate Vice President)

Contact: 2nd Floor, Municipal Building, Aluva, Kerala - 683101 | Phone: 0484-2866511 | Email: grievanceescalations@federalbank.co.in

Jurisdiction: Reviews stalled OTS proposals, SARFAESI valuation disputes, and recovery agency violations.

Tier 3Principal Nodal Officer (PNO)
SLA: 15 Working Days

Authority: Biju K. (Executive Vice President)

Contact: Federal Towers, Aluva, Ernakulam, Kerala - 683101 | Phone: 0484-2866521 | Email: support@federalbank.co.in

Jurisdiction: Senior-most internal apex authority for third-party harassment, NRI lien disputes, and final compromise review.

Tier 4RBI Banking Ombudsman (Statutory Regulator)
SLA: 30 Days Post-PNO

Authority: Reserve Bank of India Consumer Education and Protection Cell

Contact: Portal: cms.rbi.org.in | Toll-Free: 14448 | Postal: CRPC, RBI, 4th Floor, Sector 17, Chandigarh - 160017

Jurisdiction: Binding statutory adjudication under the Reserve Bank - Integrated Ombudsman Scheme, 2021.

📝

1-Click Federal Bank PNO Harassment & OTS Template

Personalize the bracketed variables and email directly to support@federalbank.co.in.

Subject: URGENT: Illegal Recovery Harassment & Formal OTS Settlement Submission - Loan A/C [Your Account Number]

To:
The Principal Nodal Officer,
The Federal Bank Ltd, Federal Towers, Aluva,
Email: support@federalbank.co.in

Cc:
Nodal Officer: grievanceescalations@federalbank.co.in

Dear Sir,

I am writing regarding my Loan/Credit Card Account Number [Your Account Number] registered with Federal Bank [Branch Name].

Due to severe involuntary financial distress resulting from [State Reason: e.g., Serious Medical Crisis / Sudden Loss of Employment / Enterprise Involuntary Shutdown], I have suffered an acute breakdown in regular EMI servicing capacity. I have formally communicated my readiness to execute a legitimate One-Time Settlement (OTS) compromise reflecting my realistic financial means.

However, collection callers and recovery agents claiming to represent Federal Bank have violated RBI fair practice codes:
1. Contacting me outside the RBI-prescribed window (8:00 AM to 7:00 PM).
2. Threatening unlawful attachment of family NRE/NRO accounts and non-borrower assets.
3. Using coercive and threatening language in violation of the RBI Master Direction on Fair Practices Code.

Please note that these actions violate RBI guidelines and constitute an offense under Section 351 of the Bharatiya Nyaya Sanhita (BNS) for criminal intimidation.

I hereby formally demand:
1. Immediate cessation of all unauthorized collection visits and abusive telecalling.
2. Formal processing of my compromise settlement proposal under Federal Bank OTS guidelines.
3. Official written communication sent exclusively to my registered email address.

Yours faithfully,
[Your Name]
[Contact Number]
[City]

8. Frequently Asked Questions (Federal Bank Debt Settlement)

Can I settle an unsecured FedMobile digital personal loan?
Yes. FedMobile personal loans are completely unsecured. If you face job loss or financial loss, you can settle your loan. After 90 to 180 days of unpaid EMIs, your file moves to the Asset Recovery Department. Federal Bank often waives 100% of late fees and 35% to 55% of your principal amount.
How does Federal Bank enforce Section 171 Banker's Lien on NRI deposits?
Under Section 171 of the Indian Contract Act, 1872, the bank has a right called a banker's lien. If you default on a loan, Federal Bank can freeze money in your linked NRE or NRO accounts. They can also take funds from your fixed deposits under the same Customer Identification File (CIF). To protect your family savings, move them to another bank before you stop paying EMIs.
What is the role of Federal Bank Stressed Assets Recovery Branches (SARB)?
Branch managers cannot give big loan discounts. When your unpaid loan crosses 90 days, Federal Bank moves your file to a Stressed Assets Recovery Branch (SARB). Officers at SARB have the legal power to approve deep discounts. They can waive interest charges and approve your One-Time Settlement (OTS).
What percentage waiver can I expect on Federal Bank credit cards?
Federal Bank credit card interest can reach 41.9% per year. In a formal settlement, the bank waives 100% of these interest charges and late penalties. For the core principal balance, borrowers can usually negotiate a 40% to 60% discount based on genuine hardship.
Does settling with Federal Bank stop SARFAESI proceedings on housing loans?
Yes. But you must sign a settlement agreement before the property auction date. You usually have to pay an advance token of 10% to 25%. Once you pay the full settlement amount, Federal Bank cancels its Section 13(2) and Section 13(4) notices. They will release your house papers and give you a No Dues Certificate.
Can recovery agents harass family members in Kerala or other states?
No. RBI rules strictly ban recovery agents from calling your family or friends. Agents can only call or visit between 8:00 AM and 7:00 PM. They cannot use abusive language. If agents harass you, file a police complaint under Section 351 of Bharatiya Nyaya Sanhita (BNS). You should also complain to Federal Bank's Principal Nodal Officer.
How does National Lok Adalat facilitate Federal Bank settlements?
Federal Bank regularly takes cases to National Lok Adalat through NALSA and state bodies like KELSA. When you settle at Lok Adalat, the judge passes an award under Section 21 of the Legal Services Authorities Act, 1987. This order has the power of a civil court decree. It permanently closes all Section 138 cheque bounce and Section 25 NACH cases.
How long does Federal Bank take to issue the No Dues Certificate (NDC)?
Under RBI circular RBI/2023-24/60, Federal Bank must issue your No Dues Certificate within 30 days of full payment. They must also return all your original property or vehicle papers. If the bank delays past 30 days, they must pay you ₹5,000 for every day of delay.
Are debts with FedFina (Federal Bank Financial Services) settled together?
No. FedFina is a separate NBFC company. Even though Federal Bank owns a large share, FedFina has its own recovery team. You cannot settle a FedFina loan through Federal Bank branches. You must negotiate directly with FedFina officers.
How does a Federal Bank settlement impact my CIBIL credit score?
The bank reports your loan as 'Settled' to CIBIL and other credit bureaus. Your score will drop by 60 to 100 points initially. But you can rebuild it. Take a secured credit card against a small fixed deposit. Pay all monthly bills on time. Your credit score can cross 750 again in 18 to 24 months.

Find this content helpful?

If this guide has helped you navigate your settlement journey, consider showing some support to keep this platform running.