UPDATED: SEPTEMBER 2026
Branch International Loan Settlement & Default Resolution
Why Branch Denies OTS Waivers & How to Settle Dues
If you have missed payments on the Branch Personal Finance App, you need accurate facts. Unlike big banks, Branch does not offer 50% settlement discounts. This survival guide explains why Branch refuses haircuts, how to get 100% late fees waived, stop agent calls, and protect your credit score.
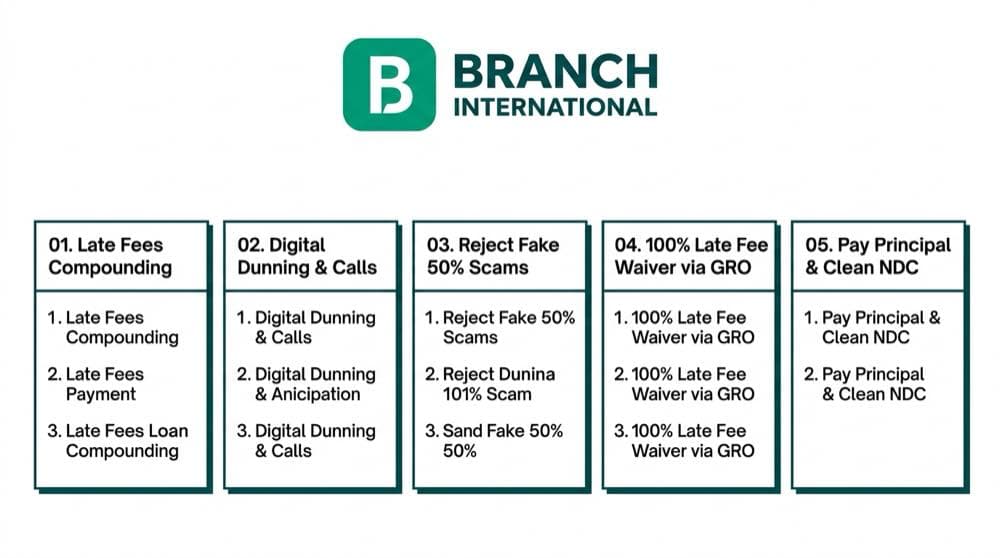
Visual Blueprint: The 5-stage Branch default roadmap: fees accumulate, agency dunning starts, reject fake 50% scams, secure 100% late fee waiver via GRO, and clear principal for clean closure.
Quick Answer SummaryBranch International strictly does not offer 50% One-Time Settlement (OTS) haircuts on principal debt. Because Branch is a digital NBFC funding micro-loans (₹1,000-₹50,000) without cheap public deposits, it cannot afford principal write-offs. However, under RBI Fair Lending Rules, you can negotiate a 100% waiver of late fees and penal interest directly with Grievance Redressal Officer Vishal Kaushik (gro@branch.co). Clear the borrowed principal to receive a clean No Dues Certificate and avoid credit damage.
1. Branch International Reality: Micro-Ticket Lending & Zero-OTS Policy
Branch International runs in India through Branch International Financial Services Private Limited. It is a licensed NBFC registered with the Reserve Bank of India.
Branch maintains a strict zero-settlement policy on personal loans. Unlike big commercial banks, Branch does not offer One-Time Settlement (OTS) haircuts. It sets aside zero funds for forgiving principal debt.
Statutory Corporate Registry Details:● Legal Name: Branch International Financial Services Private Limited
● Corporate Identification Number: U65929MH2017FTC296528
● RBI NBFC Registration: Non-Deposit Taking Systemically Important NBFC
● Registered Office: VIOS Towers, Antop Hill, Mumbai 400037
Branch customer care will not give you a 50% discount. Knowing this policy protects you from false hopes and fake settlement agents.
2. Balance Sheet Constraints: Why Small NBFCs Reject Principal Haircuts
Big banks approve loan settlements because their ticket sizes are huge. A bank personal loan is often ₹5 Lakh to ₹20 Lakh. Court cases cost banks over ₹50,000 in legal fees. Giving a discount saves them money.
Branch offers micro-ticket loans from ₹1,000 to ₹50,000. For an unpaid loan of ₹10,000, a 50% cut means losing ₹5,000. Branch uses cheap automated calls and app reminders. Their recovery costs are very small.
The Funding Structure Reality:Big banks hold public savings accounts paying low interest. Branch does not take public deposits. It borrows money from wholesale credit lines and venture funds.
Branch must repay its lenders 100% of the funds. It cannot afford principal write-offs. It demands 100% principal repayment from every borrower.
3. Why Section 171 Banker's General Lien Does NOT Apply to Branch NBFC
Section 171 of the Indian Contract Act gives regular banks a general lien. This law lets banks take money from your savings account to pay off debts.
This rule does not apply to Branch International. Branch is an NBFC, not a bank. It does not hold your savings or salary account.
Your Bank Account Rights:Branch cannot freeze your bank account. It cannot touch your monthly salary. It cannot block your UPI payments without a court order.
Any agent who threatens to freeze your bank account is lying. Such threats break RBI fair practice rules.
Branch can only present automated NACH mandate debits. If your account has no funds, the payment bounces. You only pay standard bank bounce fees.
4. The RBI Digital Lending Guidelines (DLG) Shield: Stopping Harassment
The Reserve Bank of India created strict Digital Lending Guidelines. These rules protect borrowers from rogue collection tactics. Branch and its partner agencies must follow these rules.
RULE 1: NO CONTACT LIST ACCESSLoan apps cannot read your phone contact list or gallery. Agents cannot call your family, friends, or boss about your loan.
RULE 2: STRICT CALL TIMINGSRecovery agents can only call between 8:00 AM and 7:00 PM. Calling early in the morning or late at night is illegal.
RULE 3: NO PUBLIC SHAMINGAgents cannot post on your social media or make WhatsApp groups. Your loan status is private by law.
If an agent breaks these rules, record the phone call. Save screenshots of all messages. Report them to the Branch Nodal Desk and the RBI Sachet portal.
5. Rebutting Unilateral Sole Arbitration Under Perkins Eastman & Section 12(5)
Defaulted borrowers often receive legal notices about online arbitration. These notices say a private arbitrator will pass an order against you.
The Supreme Court decided this issue in the TRF Ltd and Perkins Eastman cases. A lender cannot pick a sole arbitrator on its own. Under Section 12(5) of the Arbitration Act, one-sided appointments are illegal.
How to Reply to One-Sided Arbitration Notices:Do not panic over arbitration letters. Send an email objection to the lender and arbitrator stating:
“I object to this sole arbitrator under Section 12(5) and the Supreme Court Perkins Eastman ruling. Any award passed without my written agreement is null and void.”
After sending this formal email, the lender cannot enforce the award in an execution court.
6. The Third-Party Settlement Agency Trap: Exposing Fake 50% Haircut Scams
Fake debt relief firms target people who default on loan apps. They promise to settle Branch loans for 50% less. In return, they demand upfront fees of ₹3,000 to ₹10,000.
Beware of Private Settlement Scams:Branch International does not work with third-party debt settlement firms. Branch rejects all settlement requests from private agencies.
These firms take your money and send useless emails. Branch ignores their letters. Meanwhile, your unpaid loan keeps growing and ruins your credit score.
Never pay upfront money to any settlement agency. Always deal directly with Branch through official channels.
7. The Realistic Compromise: 100% Late Fee Waiver & Principal Repayment
Branch refuses principal discounts. But you can still get big savings on penalty charges.
When a loan is 90 days late, penalty fees can double your dues. Under RBI Fair Lending Rules, lenders cannot charge compound interest on penalties.
How to Settle with Zero Penalties:● Step 1: Check your loan account for the exact principal you borrowed.
● Step 2: Email the Grievance Officer (gro@branch.co) with proof of your job loss or medical emergency.
● Step 3: Offer to pay 100% of the principal if they waive all late fees and bounce charges.
● Step 4: Branch operations routinely approves 100% late fee waivers to close overdue accounts.
Paying the principal with a 100% fee waiver saves you money. It also keeps your credit score safe.
8. Deciphering Section 25 PSS Act & Section 138 e-NACH Bounce Summons
When an auto-debit bounces, lenders send notices under Section 25 of the Payment and Settlement Systems Act, 2007. They may also cite Section 138 of the Negotiable Instruments Act.
These laws deal with bounced banking payments. They are not criminal police offenses. The police cannot arrest you for an unpaid loan app EMI.
Your Rights Under Section 25 Notices:● 15-Day Notice Period: You have 15 days from receiving the notice to clear the dues or reply.
● Genuine Court Summons: Real court summons arrive by registered post, not over WhatsApp from agents.
● Bailable Offense: Section 25 offenses are compoundable. You get bail on the same day and can settle in court easily.
9. Countering Field Recovery Agents Under Bharatiya Nyaya Sanhita (Section 351 BNS)
Collection agents sometimes threaten house visits or police complaints. These aggressive actions break the law.
Under the Bharatiya Nyaya Sanhita (BNS) 2024, harassing borrowers is a criminal offense.
Key Criminal Protections (BNS 2024):● Section 351 BNS (Criminal Intimidation): Threatening your family or work reputation is a crime.
● Section 329 BNS (Criminal Trespass): Entering your home without official ID and papers is illegal.
● Section 352 BNS (Intentional Insult): Using bad words or abuse on phone calls is punishable by law.
If an agent visits your home, demand their employee card and written bank letter. If they threaten you, file a police complaint under Section 351 BNS.
10. Resolving Branch Dues Through National Lok Adalat Pre-Litigation Drives
National Lok Adalats are government-backed settlement courts held every three months. They are run by the National Legal Services Authority (NALSA).
For loans delayed past 180 days, Lok Adalat gives complete peace of mind. A judge helps you and the lender reach an affordable agreement.
Advantages of Lok Adalat Settlement:● Total Penalty Waiver: Judges routinely cancel 100% of late fees, bounce charges, and penal interest.
● Easy Monthly Installments: You can pay the principal in small monthly parts without extra interest.
● Final Court Order: A Lok Adalat award is equal to a civil court decree. No agency can ever ask for money again.
● Zero Court Fees: Lok Adalat is 100% free for all citizens.
11. Direct Grievance Escalation: Bypassing Chatbots to Reach GRO Vishal Kaushik
App chatbots and call center desks follow fixed scripts. They do not have the power to waive late fees or stop calls.
To solve your issue, bypass the chatbot and reach official grievance officers directly:
TIER 1: CUSTOMER CARE DESKEmail: india@branch.co | Phone: +91 8655937426. Ask for your loan account statement and fee details.
TIER 2: GRIEVANCE REDRESSAL OFFICEROfficer: Vishal Kaushik (Head of Operations) | Email: gro@branch.co | Phone: +91 8655937427. This desk has the power to waive late fees and stop agent calls.
TIER 3: RBI OMBUDSMANIf Branch does not fix your complaint in 30 days, file a case on the RBI portal (cms.rbi.org.in) or call 14448.
12. Forensic Settlement Letter Checklist: 7 Mandatory Checkpoints on Letterhead
Some recovery agents make fake settlement letters on phone apps to hit their monthly targets. Never pay money without checking these 7 items:
1. OFFICIAL LETTERHEAD:Must show Branch International Financial Services Private Limited with CIN U65929MH2017FTC296528.
2. CORRECT LOAN NUMBER:Must match the exact loan number shown in your Branch app.
3. EXACT WAIVER AMOUNT:Must list the principal amount, late fee waiver, and net payment clearly.
4. FULL AND FINAL CLOSURE:Must state that this payment settles the loan completely with zero balance left.
5. NOC DELIVERY DATE:Must promise to send your No Dues Certificate within 30 days.
6. OFFICER SIGNATURE:Must carry the name and employee code of an authorized operations manager.
7. OFFICIAL EMAIL SENDER:Must arrive from an official email ending in @branch.co, never Gmail or Yahoo.
13. Zero-Cash & Direct App Repayment: Avoiding Fraudulent QR & UPI Scams
A common scam in loan recovery happens when agents ask for money on personal UPI accounts or phone numbers.
Strict Zero-Cash Rule:Branch International never accepts physical cash. It never accepts money on personal UPI IDs of agents. Money sent to an agent will not reduce your loan balance.
Always pay directly inside the official Branch Personal Finance app. You can also pay directly to the verified bank account of Branch International Financial Services.
Never scan any QR code sent on WhatsApp. Always check your updated balance in the app immediately after paying.
14. Post-Resolution Credit Rebuilding: Upgrading CIBIL from Overdue to Closed
When a bank gives a large settlement discount, credit bureaus tag the loan as Settled. A settled mark drops your score by 75 to 100 points. It blocks you from getting fresh loans for several years.
Branch works through penalty fee waivers instead of loan haircuts. When you pay the full principal, your account status becomes clean Closed.
Steps to Rebuild a 750+ Credit Score:● Step 1: Collect your official No Dues Certificate from Branch within 30 days of payment.
● Step 2: Check CIBIL and Experian. Ensure your loan shows Closed with zero balance.
● Step 3: Get a secured fixed deposit credit card (like SBI, Kotak 811, or IDFC FIRST Bank) with a ₹10,000 deposit.
● Step 4: Use less than 30% of your limit and pay your bill on time every month. Your score will cross 750 in 6 to 12 months.