HomeAbout
BlogSoon
Bank specific setupSoon
LocationsSoon
WARNING: THIS IS NOT LEGAL ADVICE. THIS IS SURVIVAL ADVICE BASED ON REAL BORROWER EXPERIENCE.
UPDATED: SEPTEMBER 2026

Yes Bank Loan Settlement Process & JC Flowers ARC Rules

How to Settle Yes Bank Personal, Card & ARC Debt

Following its historic reconstruction and the landmark ₹48,000 crore bad-loan transfer to JC Flowers ARC, Yes Bank operates with private sector recovery agility. Learn how to negotiate substantial OTS waivers, defend against Section 171 banker's lien and Section 25 PSS notices, and secure binding Lok Adalat decrees.

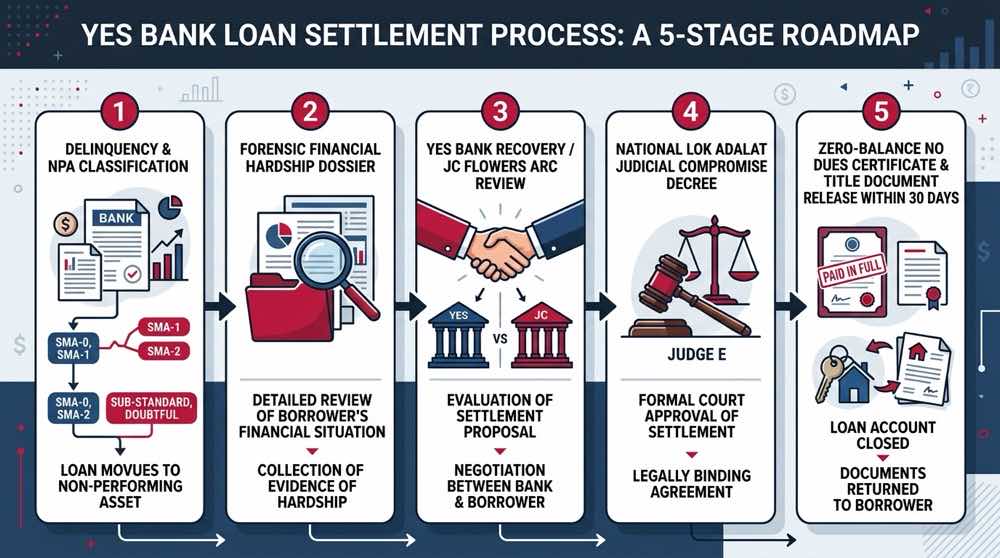
Yes Bank Loan Settlement Process, JC Flowers ARC Escalation and OTS Workflow

Figure 1: Official settlement hierarchy and compromise procedure across Yes Bank operations and JC Flowers ARC desks.

Quick Answer Summary

Yes Bank debts can be settled directly or through JC Flowers ARC (which acquired over ₹48,000 Cr of stressed assets at deep discount). Delinquent unsecured loans and credit cards can be settled for 40% to 65% of the ledger balance with Yes Bank, and up to 60% to 75% waiver with JC Flowers ARC. Settlements executed before the National Lok Adalat provide a binding judicial decree under Section 21 of the Legal Services Authorities Act, permanently extinguishing all Section 138 cheque bounce and Section 25 PSS proceedings.

⚡ Empirical CalculatorUNSECURED NPA

Yes Bank Settlement & Haircut Estimator

Calculate realistic One-Time Settlement (OTS) compromise ranges based on Yes Bank & JC Flowers ARC recovery norms.

Unsecured retail advance. Delinquent accounts past 180 DPD qualify for 100% penal interest waiver and up to 60% principal reduction.

₹3,50,000
₹25,000₹25,00,000₹50,00,000
Target Settlement Offer:50%–65% Haircut
Realistic Settlement Range:₹1,22,500₹1,75,000
Estimated Debt Forgiven:₹1,75,000₹2,27,500
*100% penal interest and late bounce charges waived under Yes Bank OTS policy.
⚠️
Yes Bank Recovery Caveat:Yes Bank retail stressed accounts past 180 DPD are actively negotiated by centralized recovery desks. Settle before secondary agency escalations.

1. Yes Bank Institutional Reality: Reconstruction Era Speed

Following the historic reconstruction scheme orchestrated by the Reserve Bank of India and a consortium of institutional lenders, YES BANK Limited fundamentally restructured its balance sheet. Under new institutional leadership, the bank embarked on aggressive bad loan purging to restore profitability and regulatory capital ratios.

For borrowers facing unpaid debt at Yes Bank, this commercial transformation offers immense tactical advantages. Unlike public sector banks that operate with bureaucratic paralysis under CVC and CAG audit scrutiny, Yes Bank operates with complete private sector agility. Credit committees have broad latitude to sanction deep compromise write-offs (often exceeding 50% to 65%) if an immediate lump-sum settlement eliminates bad loan provisions.

Commercial Loss Provision Cycles

Yes Bank operates on strict quarterly financial reporting cycles. Accounts overdue past 180 or 365 days (Doubtful D1/D2) require heavy capital allocation. Approaching recovery managers near the end of quarterly fiscal quarters (June, September, December, and especially March) yields maximum settlement concessions.

2. JC Flowers ARC Bad Loan Pool: SARFAESI Section 5 Assignment Protections

The single most decisive variable in resolving delinquent Yes Bank debt is determining whether your loan remains on the bank's live balance sheet or was transferred to J.C. Flowers Asset Reconstruction Private Limited (JC Flowers ARC). In a historic stressed-asset transaction, Yes Bank assigned an unprecedented ₹48,000 crore non-performing portfolio to JC Flowers ARC.

Why ARC Portfolios Yield Record 60% to 75% Waivers

When JC Flowers ARC acquired the ₹48,000 crore bad loan pool, they acquired the portfolio at a deep institutional discount, paying approximately 20 to 30 paise on the rupee. Because the ARC's cost basis is a fraction of the original ledger dues, their resolution managers are commercially empowered to sanction deep compromise haircuts ranging between 60% and 75% while still securing an internal financial return for the recovery trust.

When Yes Bank assigns a loan, the transfer is strictly governed by Section 5 of the SARFAESI Act, 2002 (Acquisition of rights or interest in financial assets). Under this statutory framework:

Statutory Borrower Protections Upon ARC Assignment

  • Mandatory Written Notice: Yes Bank and JC Flowers ARC must serve a formal written Notice of Assignment specifying the loan account number and transfer date.
  • Preservation of Equities & Defenses: All legal defenses, dispute history, and payment counterclaims valid against Yes Bank remain fully enforceable against JC Flowers ARC.
  • Prohibition of Arbitrary Alterations: The ARC cannot arbitrarily alter contractual terms, inflate interest rates retroactively, or levy unapproved collection surcharges beyond the original loan agreement.

3. Yes Bank & ARC Settlement Formula: How Waivers Are Calculated

Compromise haircuts are structured around asset aging, underlying security, and portfolio custody:

Delinquency VintagePortfolio CustodyStandard Compromise PolicyTypical Haircut Band
90 to 180 Days (NPA)Yes Bank Direct100% Principal + Waived Late Fees20% to 35% Waiver
180 to 365 Days (D1)Yes Bank DirectAggressive Unsecured Principal Cut35% to 50% Waiver
Over 1 Year (Doubtful)Yes Bank DirectDeep Loss Provision Compromise50% to 65% Waiver
Assigned Bad Loan PoolJC Flowers ARCDiscounted Cost Basis Settlement60% to 75%+ Waiver

4. National Lok Adalat: Judicial Compromise Decrees

Both Yes Bank and JC Flowers ARC regularly refer delinquent retail accounts to quarterly National Lok Adalats. Lok Adalats provide the ideal judicial shield for concluding debt compromise settlements.

Absolute Statutory Protection

An award signed during a National Lok Adalat functions as a decree of a civil court under Section 21 of the Legal Services Authorities Act, 1987. It is final, binding, and non-appealable. Executing an award at Lok Adalat legally terminates all pending Section 138 cheque bounce or Section 25 PSS proceedings and ensures the bank cannot pursue any future legal action.

5. Personal Loans & Retail Lines: Section 171 Banker's Lien

Yes Bank disburses extensive retail unsecured personal loans. When an account defaults, the bank's core banking systems take automated containment measures.

Automated Section 171 Banker's Lien

Under Section 171 of the Indian Contract Act, 1872, Yes Bank exercises a general lien over all credit balances maintained by the borrower. If you default on an unsecured loan, the bank will automatically freeze any savings account, salary account, or fixed deposit linked to your Customer ID.

To protect your living income and family subsistence funds:

  • Open an operative savings account with an unrelated banking institution before your loan crosses 60 DPD.
  • Redirect your salary credit mandate to the new external bank account.
  • Never leave emergency liquid savings in a Yes Bank account during compromise negotiations.

6. Yes Bank Credit Cards: Tackling 43.8% Compounded APR

Yes Bank credit cards (such as Prosperity, Marquee, BYOC, and ELITE) carry monthly finance charges up to 3.65%, which equals an annual percentage rate (APR) of approximately 43.8%. When combined with late fees and 18% GST, unpaid balances quickly spiral out of control.

Principal Dissection Negotiation Protocol

When negotiating a Yes Bank credit card settlement, request an itemized billing statement. Strip away all accumulated finance charges, interest levies, and late fees to identify the pure principal spend. Yes Bank settlement managers have standard authorization to waive 100% of accumulated interest charges, allowing you to settle the pure principal at a 35% to 50% discount.

7. ARC/Bank Sanction Letter Audit, Direct CBS Remittance & 30-Day NDC SLA

Because Yes Bank bad debts are often managed across dual entities-either the bank's internal special asset recovery unit or JC Flowers ARC-never remit funds based on informal communications or recovery agency slips.

Compromise Audit & Remittance Safeguards

  • ● Entity Origin Verification: Confirm whether the sanction letter is printed on official Yes Bank or JC Flowers ARC corporate stationery, signed by an authorized signatory with employee code, and includes an explicit full-and-final discharge clause.
  • ● Vehicle & Commercial Safeguards: For vehicle loans, statutory rules mandate a 14-day pre-sale notice and inventory list before any auction; for Yes Sambhav MSME facilities, demonstrate business closure to secure up to 60% principal waivers.
  • ● Direct CBS / Trust Remittance: Remit settlement proceeds strictly into your designated Yes Bank loan account via NEFT/RTGS using IFSC code YESB0..., or into the designated "JC Flowers ARC Trust A/C [Loan Number]" via crossed Account Payee Demand Draft. Never hand cash to collection agents.
  • ● Statutory 30-Day NDC SLA: Under RBI Circular RBI/2023-24/60, Yes Bank or JC Flowers ARC must issue the No Dues Certificate and return all title deeds or vehicle Form 35 documents within 30 days of full settlement payment. Any delay entitles the borrower to ₹5,000 compensation per day of delay.
  • ● CIBIL Rehabilitation: Verify at 45 days that the loan reflects ₹0 outstanding with status "Settled". Restore your credit rating past 750 over 18 to 24 months through disciplined usage of an FD-backed credit card.
Tier 1Branch Manager & Contact Center
SLA: 7 Working Days

Authority: Frontline Customer Service

Contact: Toll-free: 1800 1200 / 1860 210 1200 | Email: yestouch@yesbank.in

Jurisdiction: Handles account balance errors, initial compromise queries, and branch level disputes.

Tier 2Grievance Redressal Officer
SLA: 7 - 10 Working Days

Authority: Sangeeta P. (Head - Grievance Redressal)

Contact: YES BANK House, Santacruz East, Mumbai - 400055 | Phone: 022-50795173 | Email: head.grievanceredressal@yesbank.in

Jurisdiction: Reviews stalled OTS proposals, recovery agency misconduct, and billing disputes.

Tier 3Principal Nodal Officer (PNO)
SLA: 15 Working Days

Authority: Mr. Vikas Bindal (Principal Nodal Officer)

Contact: YES BANK House, Santacruz East, Mumbai - 400055 | Phone: 022-50795174 | Email: principal.nodalofficer@yesbank.in

Jurisdiction: Senior-most internal authority for third-party collection harassment, JC Flowers ARC coordination, and final OTS approvals.

Tier 4RBI Banking Ombudsman (Statutory Regulator)
SLA: 30 Days Post-PNO

Authority: Reserve Bank of India Consumer Education and Protection Cell

Contact: Portal: cms.rbi.org.in | Toll-Free: 14448 | Postal: CRPC, RBI, 4th Floor, Sector 17, Chandigarh - 160017

Jurisdiction: Binding statutory adjudication under the Reserve Bank - Integrated Ombudsman Scheme, 2021.

📝

1-Click Yes Bank PNO Harassment & OTS Template

Personalize the bracketed variables and email directly to principal.nodalofficer@yesbank.in.

Subject: URGENT: Third-Party Harassment & Formal OTS Settlement Submission - Loan A/C [Your Account Number]

To:
The Principal Nodal Officer,
YES BANK Limited, YES BANK House, Santacruz East,
Email: principal.nodalofficer@yesbank.in

Cc:
Grievance Head: head.grievanceredressal@yesbank.in

Dear Sir,

I am writing regarding my Loan/Credit Card Account Number [Your Account Number] registered with Yes Bank [or JC Flowers ARC Pool].

Due to severe involuntary financial distress resulting from [State Reason: e.g., Serious Medical Crisis / Sudden Unemployment / Enterprise Involuntary Liquidation], I have suffered an acute breakdown in EMI servicing capacity. I have formally communicated my readiness to execute a legitimate One-Time Settlement (OTS) compromise reflecting my realistic financial means.

However, collection callers and recovery agents claiming to represent Yes Bank have engaged in unlawful recovery intimidation:
1. Placing threatening and abusive phone calls outside the RBI-permitted window (8:00 AM to 7:00 PM).
2. Threatening unauthorized visits to my family and relatives who have zero privity of contract with the bank.
3. Using abusive language in violation of the RBI Master Direction on Fair Practices Code.

Please note that these actions violate RBI guidelines and constitute an offense under Section 351 of the Bharatiya Nyaya Sanhita (BNS) for criminal intimidation.

I hereby formally demand:
1. Immediate cessation of all unauthorized collection visits and abusive telecalling.
2. Formal processing of my compromise settlement proposal under Yes Bank / ARC settlement guidelines.
3. Official written communication sent exclusively to my registered email address.

Yours faithfully,
[Your Name]
[Contact Number]
[City]

8. Frequently Asked Questions (Yes Bank Loan Settlement)

How do I know if my Yes Bank loan was assigned to JC Flowers ARC?
Yes Bank executed a landmark transfer of approximately ₹48,000 crore in stressed debt to JC Flowers Asset Reconstruction Company (ARC). If your loan was assigned under Section 5 of the SARFAESI Act, you would have received a formal Notice of Assignment. Once assigned, all settlement negotiations and No Dues Certificates are executed directly by JC Flowers ARC.
Why do JC Flowers ARC loans qualify for deeper settlement discounts?
Asset Reconstruction Companies (ARCs) acquire stressed loan portfolios from banks at substantial discounts (often 20 to 30 paise on the rupee). Because their cost basis is significantly lower than book value, JC Flowers ARC can accept deep compromise haircuts ranging from 60% to 75% while still recording an internal financial profit.
Can Yes Bank freeze my savings account under Section 171?
Yes. Under Section 171 of the Indian Contract Act (Banker's General Lien), Yes Bank automatically places an internal debit freeze or lien on any active savings, current, or fixed deposit account linked to the same Customer Identification File (CIF). Borrowers facing default must open an independent bank account to protect essential living funds.
What percentage waiver is realistic on an unsecured Yes Bank personal loan?
On unsecured retail debt such as personal loans delinquent beyond 180 to 365 days, negotiated settlements routinely secure 40% to 60% write-offs against total outstanding ledger dues, with 100% cancellation of unbilled penal interest and finance charges.
What finance charges apply when Yes Bank credit cards default?
Yes Bank credit cards charge finance fees up to 3.65% per month, compounding to an annualized percentage rate (APR) of approximately 43.8%. In a compromise settlement, demand an itemized account statement, insist on a 100% waiver of accumulated finance charges, and settle the pure principal balance at a 35% to 50% discount.
How does National Lok Adalat help in settling Yes Bank debt?
Settling through National Lok Adalat provides a binding compromise award under Section 21 of the Legal Services Authorities Act, 1987. It legally dissolves all pending Section 138 cheque bounce or Section 25 PSS complaints and carries the finality of a civil court decree.
What should I do if third-party recovery agents use abusive language or make threats?
Record all phone calls and keep detailed logs of visits. File a criminal complaint under Section 351 of Bharatiya Nyaya Sanhita (BNS) for criminal intimidation, and escalate the violation directly to Yes Bank's Principal Nodal Officer (principal.nodalofficer@yesbank.in) and the RBI Banking Ombudsman.
Can Yes Bank seize my vehicle without a formal legal notice?
No. Supreme Court rulings (including ICICI Bank vs Prakash Kaur) strictly prohibit lenders from using musclemen or seizing vehicles without serving a statutory 14-day pre-sale notice and preparing a signed inventory sheet of all personal goods inside the vehicle.
How many days does Yes Bank have to issue my No Dues Certificate?
Under RBI circular RBI/2023-24/60, Yes Bank (and registered ARCs) must issue the No Dues Certificate (NDC) and return all original pledged documents within 30 days of receiving full settlement proceeds. Any unjustified delay mandates compensation of ₹5,000 per day.
How does a Yes Bank settlement affect my CIBIL credit score?
The loan is reported to credit bureaus as 'Settled' rather than 'Closed', which temporarily lowers your credit score by 50 to 100 points. However, by acquiring a secured credit card backed by a fixed deposit and maintaining spotless repayment records, you can rebuild your score above 750 within 18 to 24 months.

Find this content helpful?

If this guide has helped you navigate your settlement journey, consider showing some support to keep this platform running.