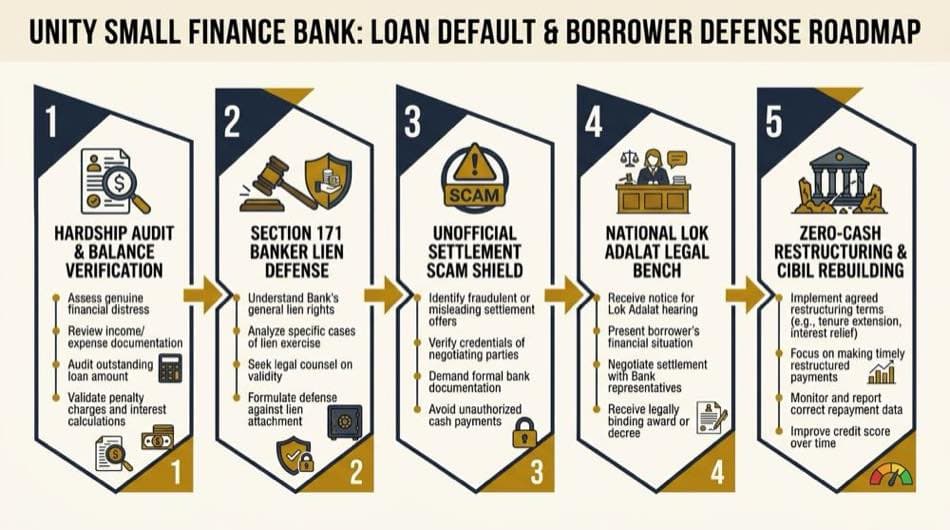
A guide to borrower rights and legal defense for defaulted Unity Small Finance Bank loans, BharatPe merchant credits, and legacy PMC Bank accounts.
Visual Blueprint: 5-stage roadmap from balance audit to Section 171 defense and Lok Adalat legal resolution.
Quick Answer Summary
Unity Small Finance Bank does not offer loan settlements or debt cuts. The bank demands 100% principal recovery to meet capital rules after taking over PMC Bank. Under Section 171 of the Contract Act, Unity SFB can freeze deposits held inside Unity Bank. However, it cannot touch your accounts in other banks without a court order. Beware of recovery agents offering verbal 50% discounts. Any money paid without an official bank sanction letter is booked as overdue interest.
Policy Analysis Tool100% PRINCIPAL RECOVERY
Unity SFB Policy & Recovery Reality Check
Understand why Unity Small Finance Bank currently denies OTS discounts and evaluate realistic resolution paths.
₹2,00,000
₹25,000₹5,00,000₹10,00,000₹15,00,000
Current Policy Status:OTS UNAVAILABLE
Bank Demand:100% Principal Amount
Early Settlement Haircut:0% Principal Haircut (100% Recovery Demanded)
Viable Restructuring Path:Restructure into extended 12 to 24 month installments with waiver of late payment penalties.
Long-Term Legal Window:Referral to National Lok Adalat after 2+ years of default enables 40% to 60% compromise decrees.
Scam Prevention Advisory:Reject verbal agent promises of 50% OTS discounts. Any deposit without a bank letter is applied to penal interest.
Grievance Escalation Hierarchy
Unity SFB 4-Tier Escalation Matrix
Do not waste time arguing with recovery telecallers. Escalate your dispute directly through these statutory tiers.
Tier 1: Centralized Customer CareSLA: 7 Days
Register your initial grievance ticket and request formal hardship review on your loan file.
Highest internal banking authority for regulatory violations, banker lien disputes, and restructuring.
Email: level3escalation@unitybank.co.inTelephone: 9152366104Address: Unit No. 2, First Floor, Central Plaza, 166, CST Road, Kalina, Santacruz East, Mumbai 400098
Tier 4: RBI Integrated OmbudsmanStatutory Forum
Lodge a formal central bank grievance if the bank fails to resolve your complaint within 30 days.
Portal: cms.rbi.org.inHelpline: 14448
Statutory Harassment Representation Notice
Copy and email this formal dispute representation directly to the Unity SFB Principal Nodal Officer.
01. Unity SFB Institutional Reality: Zero Settlement Fund Allocation
Unity Small Finance Bank maintains a strict zero settlement policy. This applies to all retail, MSME, and microfinance loans. Older banks often set aside funds each year for loan settlements. In contrast, Unity SFB demands 100% principal recovery on all overdue accounts.
The bank began operations on August 25, 2021. It was set up as a joint venture between Centrum Group (51%) and BharatPe (49%). On January 25, 2022, the bank took over the assets and debts of the troubled PMC Bank. The Reserve Bank of India and the Central Government approved this merger. The Supreme Court of India upheld the merger terms in 2026.
Unity SFB must repay PMC Bank depositors over a ten-year regulatory plan. Because of this heavy duty, the bank does not grant debt cuts to borrowers. Branch managers and customer care desks will reject any settlement request right away. Knowing this policy saves borrowers time and stops them from chasing false hopes.
Strict Zero Settlement Stance:Unity Small Finance Bank does not offer loan settlements or debt waivers. The bank demands 100% principal recovery. Do not trust third-party claims offering early settlement discounts with Unity SFB.
02. Why Unity SFB Denies Early OTS: Capital Adequacy & Audit Constraints
The refusal to grant settlements comes from strict banking rules. When Unity SFB took over PMC Bank, it inherited huge financial debts. It took on a net worth gap of nearly ₹6,000 crore and over ₹10,400 crore in deposit debts.
Under RBI rules, small finance banks must hold a capital adequacy ratio (CRAR) of at least 15%. Every rupee waived in a settlement reduces the bank's core capital. Because of this rule, the bank bars branch staff from granting debt cuts.
Unsecured business loans carry interest rates between 15.5% and 26%. Merchant advances via BharatPe carry rates between 17% and 36%. When payments stop, the banking system adds late fees and penal interest every day. Front-line staff cannot reduce the principal. However, borrowers in deep financial distress can apply for loan restructuring. You can request a waiver of late fees if you agree to pay back the full principal.
Institutional Balance Sheet Reality:
Post-merger capital rules prevent Unity SFB from taking debt cuts. Every settlement waiver hurts regulatory capital reserves. Standard settlement requests during early default (1 to 180 DPD) are rejected by policy.
03. The Fake Settlement Scam: How Rogue Recovery Agents Exploit Borrowers
Unity SFB demands 100% loan recovery. As a result, third-party recovery agents face heavy pressure to collect money. This pressure has led to many fake verbal settlement scams across the country.
Rogue recovery agents call borrowers or message them on WhatsApp. They offer fake discounts of 40% to 50% if the borrower pays right away. Worried borrowers often send money via UPI or cash to the agent. They think the loan is settled. But the bank treats this payment as overdue interest. The main loan remains in default.
You must follow a strict rule: never pay in cash. Never transfer money based on phone calls, text messages, or plain emails. Unity SFB does not accept informal agent deals. Any genuine loan relief requires an official sanction letter. The letter must be on bank letterhead, signed by an authorized manager, and verified by the head office in Kalina, Mumbai.
Beware Verbal Settlement Fraud:Collection agents cannot grant debt cuts for Unity SFB. Money paid without an official bank letterhead will be absorbed into penal interest. Your loan will remain in active default. Never transfer funds to personal UPI IDs or agent accounts.
04. Section 171 Banker's General Lien: The Real Danger to Your Savings
Under Section 171 of the Indian Contract Act, 1872, banks hold a general lien over customer funds. Unity SFB is a scheduled commercial bank licensed under Section 22(1) of the Banking Regulation Act, 1949. This gives the bank full legal right to exercise banker lien.
If you default on any loan or BharatPe credit, Unity SFB can freeze your deposit accounts. It can pull money from your savings, current, or fixed deposit accounts kept within Unity Bank. The bank does not need a court order to take this step. This makes banks different from NBFCs, which have no banker lien rights.
However, Section 171 applies only to accounts kept inside Unity Bank. The bank cannot touch, freeze, or debit your accounts at other banks. It cannot touch your money at SBI, HDFC Bank, ICICI Bank, or Bank of Baroda without a civil court decree. To protect your living expenses and business cash, move your income and banking to an outside bank before default begins.
Banker Lien Defense Protocol:Unity SFB can freeze accounts kept within Unity Bank under Section 171 of the Contract Act. It has no legal power over accounts in outside banks. Open an account at an unrelated bank right away to protect your funds.
05. Legacy PMC Bank Stressed Accounts: The 100% Recovery Mandate
Unity SFB took over PMC Bank on January 25, 2022. In doing so, it took on thousands of bad loans. These include old home loans, shop loans, and overdrafts left over from the PMC Bank collapse.
The Supreme Court confirmed the merger terms in 2026. Under this plan, Unity SFB must collect old loans to pay back PMC depositors over ten years. As a result, the bank's recovery teams use tough measures. They often send legal notices demanding compound interest added during the moratorium period.
If you hold an old PMC Bank loan, ask for a complete audited account statement. Under Indian banking law, lenders cannot add extra penal interest during a freeze ordered by regulators. If Unity SFB asks for inflated sums, challenge the bill with the Principal Nodal Officer. Offer to clear the true principal balance through a fair monthly plan.
Legacy PMC Debt Resolution Rule:Demand an audited account statement excluding compound penal interest added during the PMC Bank freeze. Unity SFB must verify the true base principal before starting legal steps on old loans.
06. BharatPe Merchant Credit & Daily QR Deduction Freeze
Many shop owners take loans through BharatPe QR codes and card swipe machines funded by Unity SFB. The bank collects these loans by taking automatic daily cuts from incoming UPI sales or NACH bank mandates.
If shop sales fall, these daily deductions can wipe out your cash flow. You may struggle to buy stock or pay shop rent. In distress, some shop owners swap their BharatPe QR for a personal QR code to stop the debits. But stopping payments triggers default clauses. The bank will send notice under Section 25 of the Payment and Settlement Systems Act, 2007.
Do not try to fix this issue using the BharatPe app chatbot. Chatbots cannot change legal loan terms. Instead, write a formal letter on your business letterhead to the Unity SFB SME Team. Explain your drop in sales. Ask the bank to convert daily cuts into a realistic monthly plan. Request a freeze on penal charges under RBI Fair Practices rules.
Merchant Deduction Defense:
Never rely on app chatbots to renegotiate loan terms. Send a written request directly to the Unity SFB SME Desk at Kalina Mumbai. Ask to convert daily deductions into monthly installments under RBI rules.
07. Microfinance (JLG) Pressure: Stopping Center Meeting Harassment
Unity SFB offers micro-loans to women through Joint Liability Groups (JLGs). In this model, four to ten women back each other for small business loans. When one member loses income and falls behind, recovery agents often use group pressure at weekly center meetings.
Under RBI Microfinance Directions 2022, lenders must not use force or threats. Central bank rules forbid agents from visiting homes outside 8:00 AM to 7:00 PM. Agents cannot use rude words or publicly shame members at group meetings.
Every borrower holds legal rights, even within a group loan. If recovery agents try to take household goods or insult your family, file a police complaint under Section 351 of the Bharatiya Nyaya Sanhita, 2024 for Criminal Intimidation. At the same time, email Unity SFB's Principal Nodal Officer to report the breach under Section 47A of the Banking Regulation Act, 1949.
RBI Microfinance Protection Shield:Under RBI MFI Directions 2022, recovery agents cannot publicly shame defaulting members or take household goods. Threatening visits violate rules and lead to fines against the lender.
08. SARFAESI Enforcement on Secured MSME Loans: Section 13 Defense
For loans backed by property or commercial assets, Unity SFB uses the SARFAESI Act, 2002. You must know your legal rights at each stage of this process to protect your property.
When an account is 90 days overdue, the bank marks it as a Non-Performing Asset (NPA). It then sends a demand notice under Section 13(2). This notice gives you 60 days to pay the dues. Under Section 13(3A), you have the legal right to file written objections during these 60 days. The bank must review your points and send a written reply within 15 days.
If the bank rejects your points, it may issue a Section 13(4) notice to take symbolic control of the asset. Even then, you keep the right to redeem the property under Section 13(8). You can clear the dues at any time before the bank publishes an auction notice in newspapers. Spotting errors in bank notices or challenging property valuations helps stop forced auctions.
SARFAESI Statutory Safeguards:
Section 13(2) Notice gives a 60-day cure window. Section 13(3A) requires the bank to answer objections within 15 days. Section 13(8) gives you the right to redeem property before the auction notice appears.
09. Deciphering Section 138 NI Act & Section 25 PSS Act Electronic NACH Notices
When loan installments or cheques bounce, Unity SFB can take legal action. It files cases under Section 138 of the Negotiable Instruments Act, 1881 for paper cheques. For bounced electronic NACH debits, it uses Section 25 of the Payment and Settlement Systems Act, 2007.
The bank must follow strict timelines to make a valid claim. It must send a written notice within 30 days of the bounce memo. You then get 15 days from receiving the notice to clear the due amount. The bank can only file a complaint in court if you do not pay within those 15 days.
These cases are bailable commercial offenses. The law aims to resolve debts, not send honest borrowers to jail. If you get a court summons, appear on the set date with a surety to secure same-day bail. Under Section 147 of the NI Act, these cases are compoundable. You can settle the matter amicably in court and close the case.
Quasi-Criminal Summons Reality:Section 138 and Section 25 offenses are bailable and compoundable. Never ignore a court summons. Appear on the scheduled date, get bail, and ask the court to refer your file to Lok Adalat for an agreed resolution.
10. Countering High-Intensity Recovery Harassment Under BNS 351
Because Unity SFB refuses loan haircuts, recovery agents face high pressure. Some agents resort to harsh collection tactics. However, RBI rules and the bank's Code of Conduct protect borrowers from harassment.
Collection agents can call or visit only between 8:00 AM and 7:00 PM. Agents must carry bank identity cards and written authorization letters. They cannot visit your home or workplace without proper badges. Calling your relatives, friends, or business partners to reveal your debt violates RBI privacy rules.
If an agent threatens you, tries to force entry, or sends fake legal notices on WhatsApp, take legal action. File a police complaint under Section 351 of the Bharatiya Nyaya Sanhita, 2024 for Criminal Intimidation. You can also cite Section 329 for Trespass. Send call recordings to Unity SFB's Principal Nodal Officer and file a report on the RBI Sachet portal (sachet.rbi.org.in).
Statutory Harassment Countermeasures:Calling hours are strictly 8:00 AM to 7:00 PM. Agents cannot call third parties. For abusive visits, cite Section 351 BNS for Criminal Intimidation and file a grievance with the Unity SFB PNO and RBI Sachet portal.
11. The Multi-Year Default Reality: When Can Unity SFB Debt Actually Settle?
Unity SFB rejects settlements during early default (up to 180 days). However, banking rules change as unpaid debt ages. When an unsecured loan stays unpaid for two to three years, RBI rules require the bank to mark it as a loss asset.
Once the bank writes off the loan on its books, holding the bad debt costs legal fees with no return. At this late stage, the bank may seek bulk resolutions. It may also sell overdue debt pools to Asset Reconstruction Companies (ARCs).
If you have no income, understand that early settlements are impossible. Do not panic under agent pressure. Focus on stabilizing your finances. Keep records of your job loss or medical hardship. Prepare to resolve the loan when the bank transfers it to an ARC or refers it to a Lok Adalat bench.
NPA Aging & Resolution Window:
Early default (0 to 180 DPD): Zero OTS allocation; 100% recovery demanded. Late stage (360+ DPD and Loss Asset): Writing off the debt allows compromise talks or ARC sales.
12. Resolving Deadlocks Through National Lok Adalat Benches
The best legal path to break a collection dispute with Unity SFB is the National Lok Adalat. The National Legal Services Authority (NALSA) organizes Lok Adalats every quarter across India. These benches help resolve disputes before or during court litigation.
A Lok Adalat panel includes a judge and an independent lawyer. Unity SFB sends senior officers with power to settle accounts. The goal of Lok Adalat is to clear bad debts peacefully without costly court battles. At these sessions, officers have the power to waive penal charges and agree on realistic payment plans.
An agreement made at Lok Adalat becomes a Consent Award under Section 21 of the Legal Services Authorities Act, 1987. This award holds the same weight as a civil court decree. It is final, requires zero court fees, and cannot be appealed. Once you fulfill the award, the bank closes all claims and court cases permanently.
Lok Adalat Legal Immunity:A Lok Adalat consent decree under Section 21 has the force of a final civil court decree. It is binding on both sides, requires no court fees, and bars Unity SFB from filing future recovery cases.
13. The 4-Tier Statutory Escalation Matrix: Bypassing Automated Helpdesks
If you face recovery abuse or need loan restructuring, bypass branch counters and app bots. Unity SFB has a four-tier grievance system set up under RBI consumer protection rules.
Level 1 is Customer Care. You can register your complaint by calling 1800-209-1122 or emailing care@unitybank.co.in. The bank has 7 working days to resolve Level 1 issues.
If you get no answer in 7 days, move to Level 2: Escalation Officer. Call 9152366105 or email level2escalation@unitybank.co.in. If unresolved after 14 days, escalate to Level 3: Principal Nodal Officer (PNO). Call 9152366104 or email level3escalation@unitybank.co.in. You can also write to the head office at Kalina, Santacruz East, Mumbai 400098. If the bank fails to resolve the issue within 30 days, file a complaint at Level 4 with the RBI Ombudsman at cms.rbi.org.in or call 14448.
A loan default with Unity SFB gets reported to all four RBI credit bureaus: CIBIL, Experian, Equifax, and CRIF High Mark. The bank marks the account as Default or Written Off. This can drop your credit score by 80 to 150 points and blocks new loan approvals.
When you resolve the account through a payment plan or Lok Adalat decree, the bank updates the bureau status to Settled or Closed. A Settled remark stays on your credit report for up to seven years. Even so, closing the loan stops penal interest and lets you begin repairing your credit profile.
Rebuilding your score past 750 takes 18 to 24 months of steady effort. Start by opening a fixed deposit of ₹25,000 to ₹50,000 at a bank. Get a secured credit card against this deposit. Use the card for small grocery bills each month. Keep your card usage below 30% of the limit. Always pay your bill in full before the due date. Timely payments will steadily rebuild your credit score across all bureaus.
18-Month Credit Rebuilding Blueprint:
Step 1: Get an official No Dues Certificate upon full payment. Step 2: Check bureau status updates within 30 days. Step 3: Open an FD-backed secured credit card. Step 4: Keep usage below 30%. Rebuilds your score to 750+ within 18 to 24 months.
Regulatory Knowledge Base
15. Unity Small Finance Bank Default & Settlement FAQs
Verified regulatory answers regarding Unity SFB zero-settlement reality, recovery agent boundaries, and credit bureau rehabilitation.
Does Unity Small Finance Bank currently offer One-Time Settlement (OTS) or loan haircuts?▼
No. Unity Small Finance Bank maintains a strict zero settlement policy for retail and MSME loans. The bank demands 100% principal repayment to meet capital rules after taking over PMC Bank.
Why do recovery agents claim they can settle my Unity SFB loan for a 50% discount?▼
Recovery agents make false verbal promises to collect quick fees. Unity SFB does not honor informal verbal deals. Any money paid without an official bank sanction letter is booked as overdue interest.
Can Unity Small Finance Bank legally freeze my bank accounts under Section 171 Banker's General Lien?▼
Yes. As a scheduled commercial bank, Unity SFB can place a lien on savings and deposit accounts kept inside Unity Bank. However, it cannot freeze accounts in other banks without a court order.
How does Unity Small Finance Bank handle legacy Punjab and Maharashtra Co-operative (PMC) Bank loans?▼
Unity SFB took over PMC Bank on January 25, 2022. Old loans are handled by dedicated recovery teams. The bank seeks 100% principal recovery to pay back PMC depositors over time.
Can I stop automated daily swipe deductions on my BharatPe merchant loan during business distress?▼
Yes. Send a written request to the Unity SFB SME Desk at Kalina Mumbai. Ask to convert daily deductions into monthly installments under RBI Fair Practices rules.
What legal defense protects women borrowers from recovery harassment in microfinance Joint Liability Groups?▼
Under RBI Microfinance Directions 2022, lenders cannot use harsh peer pressure or visit outside 8:00 AM to 7:00 PM. Agents cannot shame members in public. Violations can be reported under Section 351 of the Bharatiya Nyaya Sanhita.
What are my statutory rights if Unity Small Finance Bank issues a SARFAESI Section 13(2) notice?▼
You get 60 days to reply. Under Section 13(3A), you can file written objections that the bank must answer within 15 days. Under Section 13(8), you keep the right to redeem your property before the bank publishes an auction notice.
Is a court summons under Section 138 NI Act or Section 25 PSS Act a non-bailable criminal offense?▼
No. Both Section 138 and Section 25 are bailable and compoundable offenses. You can get same-day bail from the magistrate and settle the matter through the National Lok Adalat.
When can a defaulted Unity Small Finance Bank loan actually be resolved?▼
The bank denies early settlements. However, accounts overdue for more than two years become loss assets. These can be resolved through Lok Adalat benches or sales to debt reconstruction firms.
How do I file a formal complaint against abusive Unity SFB recovery agents?▼
Send a written complaint with call recordings to the Principal Nodal Officer at level3escalation@unitybank.co.in. If unresolved after 30 days, file a complaint on the RBI CMS portal at cms.rbi.org.in.