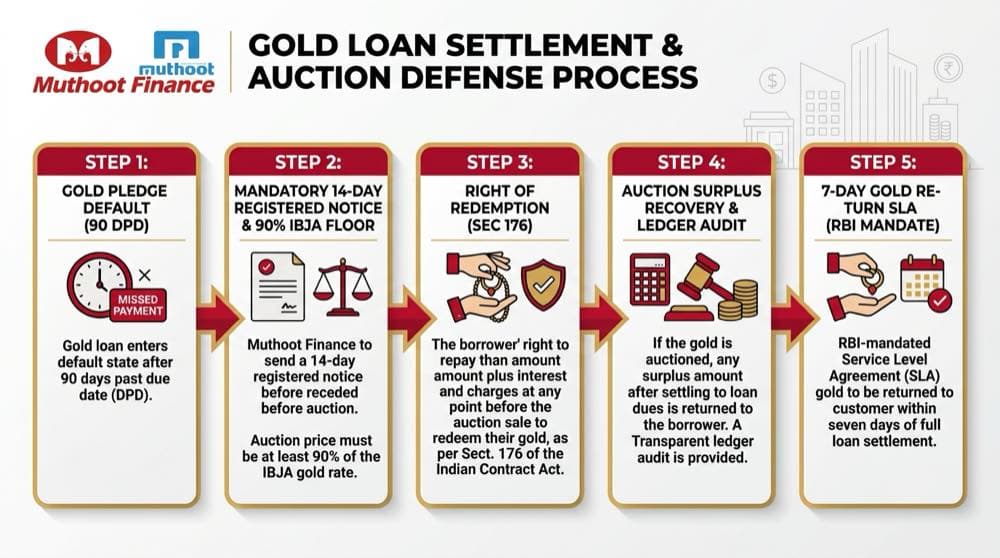
The definitive borrower defense manual for Muthoot Finance gold loans, Muthoot Money personal loans, and vehicle debt. Learn how to secure penal interest waivers, stop unauthorized gold auctions under Section 176, claim auction surplus, and settle unsecured debts.
Visual Blueprint: 5-stage procedural roadmap for Muthoot Finance gold default, penal interest waiver negotiations, statutory 14-day notice, Right of Redemption, and auction surplus recovery.
Quick Answer Summary: Muthoot Settlement Reality
Does Muthoot Finance offer loan settlements? Yes. While lenders like Navi, Kissht, and Si Creva strictly do not offer settlement, Muthoot Finance does provide settlement options. For gold loans, Muthoot regularly approves 100% penal interest and compounding charge waivers to enable borrowers to redeem their gold ornaments prior to auction, and legally must refund 100% of auction surplus under Section 176. For unsecured loans (Muthoot Money and vehicle shortfalls), borrowers can negotiate 35% to 50% OTS haircuts through written escalation to the Principal Nodal Officer or during quarterly National Lok Adalat sessions.
Understand realistic resolution possibilities based on Muthoot Finance's gold loan redemption rules, 100% penal interest waivers, and 30%–50% unsecured compromise settlements.
Pledged ornaments governed by Section 176 Contract Act. Muthoot demands principal repayment or auction with mandatory surplus refund, but waives 100% penal charges.
₹3,00,000
₹25K₹10 Lakh₹25 Lakh
Estimated Settlement Range:0% to 0% Haircut
Realistic Payoff Amount
₹3,00,000 - ₹3,00,000
Projected Savings
₹0 - ₹0
✓Penal Relief: 100% penal interest and compounding monthly rollover charges waived on lump-sum redemption.
✓Strategic Advice: Under Section 176, you hold a statutory Right of Redemption right up until the auction hammer falls. Muthoot cannot haircut gold principal.
⚠️ Section 174 Cross-Lien Defense:Under Section 174 of the Indian Contract Act, Muthoot Finance cannot legally hold back your redeemed gold ornaments for an unpaid personal loan with Muthoot Money or an auto loan with Muthoot Capital. Each loan agreement is a separate legal contract.
1. Muthoot Institutional Reality: Collateral Pledges vs. OTS Waivers
Muthoot Finance Limited is India's largest specialized gold financing Non-Banking Financial Company (NBFC). Unlike fintech apps such as Navi, Kissht, and Si Creva that refuse settlement entirely, Muthoot operates structured resolution processes across its collateralized and uncollateralized lending portfolios.
For gold loans, Muthoot relies on physical custody of ornaments inside branch vaults. While principal haircuts on gold are not given if the market value covers the debt, Muthoot routinely approves 100% waivers of compound penal interest and late rollover fees to facilitate lump-sum redemption before auction. For unsecured advances (Muthoot Money) and auto shortfall balances (Muthoot Capital), accounts past 180 DPD qualify for 35% to 50% One-Time Settlement (OTS) waivers.
Frontline telecallers and branch clerks frequently claim settlement is impossible to meet recovery targets. However, escalating directly to the Principal Nodal Officer or presenting your case at National Lok Adalat unlocks official compromise sanction letters.
Settlement Verification Rule:Muthoot Finance approves genuine settlements directly on official company letterhead with complete waiver details. Never pay cash to recovery agents who make unverified verbal promises.
2. Section 176 Pledge Law vs SARFAESI (Movable Gold)
A foundational legal reality that borrowers must understand is that gold jewellery is movable property governed strictly by Section 176 of the Indian Contract Act, 1872 (Pledge of Goods), not the SARFAESI Act, 2002.
The SARFAESI Act applies only to immovable real estate (such as residential houses and commercial plots). When recovery agents threaten you with SARFAESI notices or property attachment for an unpaid gold loan, they are using an unlawful bluff. Under Section 176, the lender (pawnee) has only two legal choices:
The Statutory Dual Choice Under Section 176:
Sue the Borrower in Civil Court: Muthoot can file a civil recovery suit while retaining the pledged gold as collateral security.
Sell the Pledged Gold on Reasonable Notice: Muthoot can sell the gold at a public auction, provided they give the pawnor (borrower) reasonable prior notice of the sale.
Crucially, under Indian law, any auction conducted without reasonable advance notice is illegal and constitutes a civil conversion of goods, making the company liable for damages.
Under Reserve Bank of India Master Directions for NBFCs, Muthoot Finance cannot quietly auction your family gold behind closed doors. The company is bound by strict procedural safeguards:
Mandatory 14-Day Registered Notice: Muthoot must serve a registered notice giving you a minimum of 14 clear calendar days from receipt to settle the loan dues or redeem your ornaments.
Tracking & Proof of Delivery: A simple SMS or automated WhatsApp notification does not satisfy the legal requirement. The lender must produce registered speed-post tracking proof showing valid service.
Public Newspaper Advertisements: RBI guidelines mandate that public auction details (date, town, auctioneer name, and lot numbers) must be published in at least two regional newspapers (one in vernacular language and one in English).
Prohibition on Private Sales: Muthoot cannot sell your gold jewellery across the counter to friendly local jewelers or company employees. Auctions must be transparent public events conducted by independent, board-approved auctioneers.
4. The 90% IBJA Reserve Price Floor & Surplus Recovery
A major risk in distressed gold auctions is undervaluation. In the past, corrupt auction rings would buy seized ornaments at artificially deflated prices, wiping out borrower equity. To eliminate this predatory practice, the Reserve Bank of India instituted the 90% IBJA Reserve Price Rule.
Under RBI norms, the minimum reserve floor price for any auctioned gold lot must be fixed at not less than 90% of the average closing price of 22-carat gold over the preceding 30 business days, as quoted by the India Bullion and Jewellers Association (IBJA).
Statutory Surplus Protection (Section 176):
If the auction sale proceeds exceed your total outstanding balance (loan principal + contracted interest), the entire surplus money belongs to you. Under Section 176, Muthoot must refund this surplus balance directly into your bank account within 30 days. If they fail to remit the surplus, you can file a complaint with the RBI Ombudsman demanding refund plus statutory interest.
5. Right of Redemption: Saving Gold Before Hammer Falls
One of the most potent protections under Indian jurisprudence is the Right of Redemption codified in Section 177 of the Indian Contract Act, 1872:
"If a time is stipulated for the payment of the debt, and the pawnor makes default in payment at the stipulated time, he may redeem the goods pledged at any subsequent time before the actual sale of them."
Even if your 14-day notice period has expired, and even if your gold ornaments have already been dispatched to the regional auction center, your right to redeem remains legally intact right up until the auctioneer strikes the hammer.
If you tender the settlement amount or overdue principal before the sale concludes, Muthoot is legally obligated to stop the auction and return your ornaments. Refusal to accept repayment before the hammer falls constitutes an illegal act.
6. The 24%–30% Renewal Trap & Interest Inflation
The standard business model of gold NBFCs relies on the "Renewal Trap". When a 6-month or 12-month gold loan matures and the borrower cannot afford the lump-sum principal payoff, branch agents convince them to pay only the accumulated interest and renew the loan under a new scheme.
These renewal schemes often carry compounding APRs ranging from 24% to 30% per annum, plus penal compounding interest of 2% to 3% per month for delayed renewals. Over two years, a borrower can pay more than 50% to 60% of the loan amount in interest alone, while the principal balance remains untouched.
To break this cycle, never sign blind renewal forms. Instead, demand a formal account ledger, seek a waiver of accumulated penal interest, or initiate a Takeover of Gold Loan (Balance Transfer) to a public sector bank (such as SBI or Canara Bank) where gold loan interest rates are capped around 8.5% to 9.5% per annum.
A high-pressure tactic frequently reported by borrowers involves illegal cross-collateralization. If you have an active gold loan with Muthoot Finance, but you have defaulted on an unsecured personal loan from Muthoot Money or a two-wheeler loan from Muthoot Capital, the branch may refuse to release your gold even after the gold loan is 100% paid off.
This practice is explicitly unlawful under Section 174 of the Indian Contract Act:
Section 174 Statutory Presumption: Under Section 174 of the Contract Act, a pawnee cannot retain goods pledged for any debt or promise other than that for which they were specifically pledged, unless a clear contract to the contrary exists.
Separate Corporate Entities: Muthoot Finance Ltd, Muthoot Money Ltd, and Muthoot Capital Services Ltd are legally distinct corporate entities. One company cannot seize collateral pledged to another entity without an explicit court order.
If the branch refuses to release your gold after full repayment, issue a formal demand notice citing Section 174 and file a complaint on the RBI CMS portal. The Ombudsman regularly orders immediate return of the ornaments plus delay compensation.
8. Gold Vault Weighing & Stone Deduction Discrepancies
A major point of conflict during gold loan default and settlement is the appraiser's valuation of gross versus net weight. When you initially pledge ornaments, branch appraisers frequently deduct 15% to 25% of the total weight for stones, enamel, and wax (lac) filling, artificially lowering the sanctioned principal while keeping interest high.
If Muthoot threatens to auction your gold or calculates a shortfall, demand an immediate forensic audit of your original Pledge Receipt (Form 1):
Appraiser Audit & Weight Verification Rules:
No Unilateral Re-Valuation: Under RBI Master Directions on Gold Lending, Muthoot cannot unilaterally alter the net gold weight or carat purity recorded at the time of pledge without your physical presence and signature.
Karatmeter Dispute Right: If the branch claims your gold is 18-carat instead of 22-carat to justify a reduced auction credit, demand that testing be conducted on the branch electronic Karatmeter in your presence and recorded in writing.
Damage Compensation: If ornaments are returned broken or with missing stones, do not sign the discharge voucher. File an on-the-spot objection on the branch complaint register and demand compensation at prevailing market rates.
9. Unsecured Muthoot Money & Capital Shortfall: 35% to 50% OTS & Lok Adalat
Beyond physical gold pawning, the group issues unsecured personal credit via Muthoot Money and two-wheeler loans through Muthoot Capital Services Ltd. When these advances default, or when an auctioned vehicle leaves an outstanding deficiency balance, recovery dynamics shift from collateral auction to standard compromise settlement.
Unlike secured gold pledges where the physical collateral secures the debt, Muthoot Money unsecured personal loans and vehicle deficiency balances are eligible for formal One-Time Settlement (OTS). Borrowers facing verified financial hardship can negotiate waivers of 35% to 50% on accumulated interest and principal, especially when escalated to the Principal Nodal Officer or during Lok Adalat benches.
Legitimate compromise settlements with 35% to 50% waivers provide full account closure and a formal No Dues Certificate (NDC). Always obtain written sanction on Muthoot Finance letterhead prior to transferring any settlement funds.
Unsecured Debt Resolution Rule:Under Section 174 of the Contract Act, Muthoot cannot hold your pledged gold hostage for an unsecured loan shortfall. Settle unsecured deficits with 35% to 50% OTS waivers through formal written approval or Lok Adalat pre-litigation benches.
Redeeming your gold after a negotiated settlement or full payment requires following a strict physical verification protocol inside the branch manager's cabin:
Inspect Sealed Security Packets: Ensure the tamper-evident plastic packet holding your ornaments bears the exact unbroken security seal number printed on your original pledge ticket.
Weigh Ornaments on Branch Scale: Re-weigh every single piece on the branch electronic scale to verify that gross and net weights match your original receipt to the milligram before signing any ledger.
Statutory 7-Day Handover SLA: Under RBI regulations, the branch must physically return your ornaments within seven (7) working days of account closure.
Enforce ₹5,000/Day Delay Fine: If the branch manager claims the vault key is missing or ornaments were sent to a regional zonal vault and delays release beyond 7 days, submit a formal grievance. The lender is legally bound to pay ₹5,000 compensation for each day of delay.
One of the most widespread abuses in retail gold lending is lenders keeping the surplus money generated when pledged gold is auctioned. Because gold prices consistently appreciate over time, an auction often yields substantially more capital than the borrower's principal plus normal interest.
Under Section 176 of the Indian Contract Act, 1872, and RBI Master Directions:
Surplus Recovery Protocol:
Mandatory 30-Day Surplus Refund: Muthoot is legally obligated to credit the net surplus balance directly to your bank account within 30 days of the auction concluding.
Demand Full Auction Ledger: Issue a registered letter demanding the itemized auction sheet: gross hammer price, winning bidder details, GST invoice, and exact interest adjustment.
Ombudsman Escalation: If Muthoot fails to refund your surplus funds or claims inflated auction expenses, escalate to the RBI Integrated Ombudsman (cms.rbi.org.in). The Ombudsman routinely directs full surplus refund with 9% statutory interest.
12. Frequently Asked Questions (Verbatim Parity)
Does Muthoot Finance offer loan settlement or One-Time Settlement (OTS)?▼
Yes! While fintech lenders like Navi, Kissht, and Si Creva strictly do not offer settlement, Muthoot Finance does offer loan settlement solutions. For gold loans, Muthoot routinely grants substantial waivers on compound penal interest and compounding monthly rollover charges to allow borrowers to redeem their pledged ornaments, or refunds 100% auction surplus under Section 176. For unsecured personal loans (Muthoot Money) and auto loan shortfalls, Muthoot approves 35% to 50% OTS waivers once an account is delinquent and escalated to the Principal Nodal Officer or at Lok Adalat.
Can Muthoot Finance auction my gold without sending a prior notice?▼
No. Under RBI Master Directions for NBFCs and Section 176 of the Indian Contract Act, Muthoot Finance is legally mandated to serve at least 14 days prior written notice via registered post or speed post before initiating an auction. In addition, the auction must be publicly advertised in at least two local newspapers (one in vernacular and one in English). If your gold was auctioned without verifiable proof of notice delivery, the auction can be challenged before the Consumer Forum or High Court.
Can I stop a Muthoot gold auction on the day of the auction?▼
Yes. Under Section 176 of the Indian Contract Act, 1872, you retain your statutory Right of Redemption until the auction hammer falls and the sale is officially completed. If you or your representative reach the branch or auction venue and tender the required payment to regularize or settle the account, the manager is legally bound to stop the auction and return your ornaments.
What happens to the surplus money if my gold sells for more than my loan balance?▼
Under Section 176 of the Indian Contract Act, any surplus money fetched from the gold auction above your outstanding principal, legitimate interest, and reasonable auction expenses belongs 100% to you. Muthoot Finance is legally required to refund this surplus to your registered bank account within 30 days. You have the right to demand a certified itemized auction account sheet showing the winning bid and deductions.
Can Muthoot Finance withhold my gold for an unpaid personal loan or vehicle loan?▼
No. Under Section 174 of the Indian Contract Act, a pledge of goods is presumed to be contracted solely for that specific loan unless a separate cross-collateralization agreement was explicitly signed. Muthoot Finance cannot arbitrarily freeze or withhold your redeemed gold ornaments to recover an unsecured personal loan from Muthoot Money or an auto loan from Muthoot Capital.
What is the minimum reserve price for a Muthoot gold auction?▼
Under RBI regulations, the reserve price for auctioned gold jewellery must be set at not less than 90% of the average closing price of 22-carat gold for the preceding 30 days, as quoted by the India Bullion and Jewellers Association (IBJA). This statutory floor protects borrowers against below-market distress sales to insider jewellers.
What is the Muthoot Finance Renewal Trap and how can I escape it?▼
The renewal trap happens when borrowers repeatedly pay only the accrued interest every 3 to 6 months at high interest rates (24% to 30% APR) to avoid auction, without reducing the loan principal. After two years, you may end up paying 60% of the gold value in interest while still owing the full original loan amount. To escape, negotiate a formal One-Time Settlement (OTS) with a waiver on penal interest or execute a clean takeover by a public sector bank offering 8.5% to 9.5% interest.
What if the branch appraiser deducted excessive stone weight from my gold ornaments?▼
Appraiser Audit Defense: If the branch claims stone or wax weight deductions of 15% to 25% that reduce your net gold value, demand a certified re-appraisal using the branch digital Karatmeter and compare it against the original gross and net weight explicitly recorded on your pledge ticket (Form 1). Under RBI norms, lenders cannot alter weight records post-pledge without written borrower consent.
Why does Muthoot Finance reject early settlement requests on personal and shortfall loans?▼
Because Muthoot Finance allocates zero budget for early loan haircuts, central collections demands 100% repayment. Outside recovery agents face heavy collection targets since they cannot grant fee cuts, resulting in intense calling. Compromise settlements are only sanctioned for multi-year non-performing loans referred to National Lok Adalat.
How long does Muthoot Finance have to physically return my gold jewellery after payment?▼
Under RBI circular guidelines, NBFCs must release and physically return pledged gold ornaments to the borrower within seven (7) working days of receiving the full settlement or payoff amount. Any unjustified delay beyond 7 days entitles the borrower to compensation of ₹5,000 per day of delay payable by the lender.
Can recovery agents from Muthoot Finance harass my family or visit after 7 PM?▼
No. Under the RBI Fair Practices Code for NBFCs and Section 351 of the Bharatiya Nyaya Sanhita (BNS, 2024), recovery agents are strictly prohibited from calling before 8:00 AM or after 7:00 PM, visiting family members, or using abusive language. Violations can be reported immediately to the Muthoot Principal Nodal Officer and escalated to the RBI Integrated Ombudsman.
Follow the statutory protocol when local branch managers threaten quick auctions or recovery telecallers breach RBI conduct rules.
Tier 1Branch Manager & Vault Custodian
SLA: 7 Days
Jurisdiction: Home Branch where Gold or Loan was Processed
Channel: In-person Written Letter / Registered Post / Branch Receipt
Action: Submit written application asserting statutory Right of Redemption under Section 176 of Indian Contract Act. Demand itemized interest ledger separating base principal from penal charges.
Channel: Formal Representation via Registered AD / Regional Office Visit
Action: Escalate if local branch manager refuses settlement, fails to provide 14-day auction notice proof, or attempts illegal cross-lien seizure of gold under Section 174.
Tier 3Principal Nodal Officer (PNO)
SLA: 30 Days Statutory SLA
Jurisdiction: Muthoot Finance Head Office, Kochi, Kerala
Action: Formal grievance against scheduled gold auctions, recovery agent harassment outside 8 AM to 7 PM, refusal to return surplus funds, or delay in returning gold after full payoff.
Tier 4RBI Integrated Ombudsman
SLA: 30+ Days Post-PNO
Jurisdiction: Reserve Bank of India (Statutory Authority)
Channel: Online via cms.rbi.org.in | CRPC Chandigarh (Toll-Free 14448)
Action: Statutory arbitration for regulatory violations, unauthorized gold auction without 14-day notice, failure to adhere to 90% IBJA reserve price, or delay compensation of ₹5,000/day.
Pre-Drafted Nodal Dispute Notice (Sec 176 & 174)
Click the button above to copy this formal representation letter. Fill in your bracketed details and dispatch it directly to grievance@muthootgroup.com to create an unassailable legal audit trail.
To: The Principal Nodal Officer, Muthoot Finance Limited
Muthoot Chambers, Opposite Saritha Theatre Complex,
Banerji Road, Kochi, Kerala - 682018
Email: grievance@muthootgroup.com
Phone: 1800 313 1212

Subject: Urgent Grievance - Loan Account No: [INSERT LOAN ACCOUNT NUMBER] / Exercise of Right of Redemption (Section 176) & Objection to Unlawful Auction

Respected Sir/Madam,

I am a borrower with Muthoot Finance, [INSERT BRANCH NAME], holding Loan Account Number [INSERT ACCOUNT NUMBER]. Due to unforeseen financial distress arising from [BRIEFLY STATE REASON: medical crisis, job loss, business downturn], regular repayments were temporarily disrupted.

I have approached the branch to regularize or settle my loan dues, but I am facing the following critical regulatory and statutory violations:
1. The branch has issued an auction notice without providing the mandatory 14-day prior notice via Registered Post as mandated by RBI Master Directions and Section 176 of the Indian Contract Act.
2. [IF APPLICABLE]: The branch manager is refusing to allow me to exercise my statutory Right of Redemption under Section 176 before the auction concludes.
3. [IF APPLICABLE]: Muthoot is illegally withholding my pledged gold ornaments for an unrelated unsecured loan or third-party affiliate debt, in direct violation of Section 174 of the Indian Contract Act.
4. Third-party recovery agents representing Muthoot Finance have violated the RBI Fair Practices Code and Section 351 of the Bharatiya Nyaya Sanhita (BNS) by [DESCRIBE HARASSMENT: calling outside 8 AM to 7 PM / contacting family / threatening physical visits].

I hereby request your immediate intervention to:
a. Stay any scheduled auction of my pledged ornaments immediately.
b. Provide an official ledger bifurcation showing actual principal disbursed, legitimate interest, and total penal levies.
c. Facilitate an amicable One-Time Settlement (OTS) with full waiver of compounding penal interest.
d. Enforce strict compliance with the RBI mandate requiring physical handover of gold ornaments within 7 working days of payoff.

Sincerely,
[YOUR NAME]
[YOUR MOBILE NUMBER]
[YOUR REGISTERED EMAIL]
Official Statutory Grievance Portals & Regulatory Sources: