MAS Financial Services Loan Default: Zero OTS Reality & Defense
MAS Finance & MRHMFL Borrower Legal Defense Guide
MAS Financial Services refuses one-time loan compromises. The NBFC insists on recovering all principal dues in full. Do not trust outside agents promising unofficial waivers.
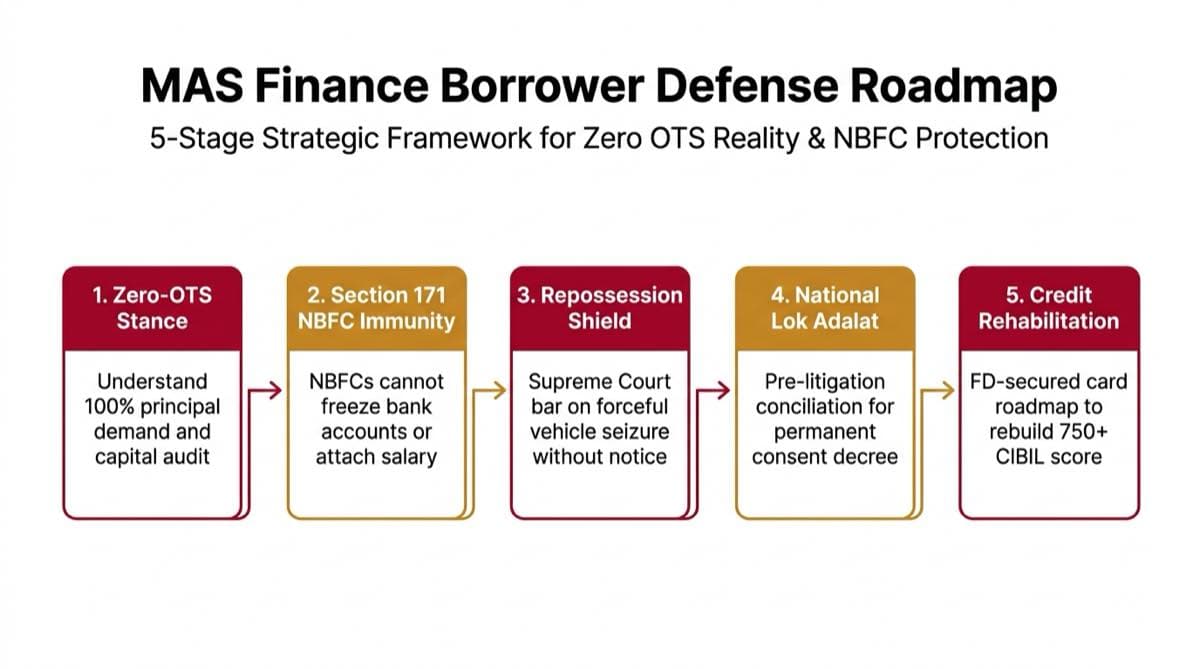
01. MAS Financial Services Corporate Reality: Listed NBFC Zero-Settlement Stance
MAS Financial Services is an RBI-registered NBFC based in Ahmedabad. It began operations in May 1995. The company is listed on the BSE and NSE under the ticker MASFIN. It is led by founders Kamlesh Gandhi and Mukesh Gandhi.
The company provides loans to small traders, shop owners, and two-wheeler buyers. It also offers home loans through its housing arm, MRHMFL. MAS Finance is a listed firm that reports to shareholders every quarter. Because of this, its management demands 100% principal recovery across all loan desks.
Public banks sometimes offer loan settlement schemes during festival seasons. MAS Finance sets aside no money for debt cuts on active loans. Branch staff in Gujarat, Maharashtra, Rajasthan, and Madhya Pradesh will reject any early settlement plea. Knowing this rule saves borrowers from wasting money on fake agents.
02. Micro-Enterprise Loans (MEL) & SME Debt: Working Capital Crisis & Recovery Mandates
Small business loans are the core of MAS Finance's book. The company lends between ₹50,000 and ₹50,00,000 to shop owners and small firms. These loans are backed by sales, cash flows, and personal guarantees.
When sales drop or raw material costs rise, paying high monthly installments becomes difficult. If you miss a payment, the bank software adds penal interest and late fees. It also adds charges for bounced NACH debits. These fees quickly inflate your total debt balance.
Branch staff work under strict recovery targets. They have no power to cut your principal loan amount. While early settlements are barred by company policy, business owners facing hardship can take another route. You can write directly to the Zonal Credit Committee in Ahmedabad. Ask the committee to stop extra penal charges and stretch your loan tenure into affordable monthly installments under RBI Fair Practices rules.
MAS Finance branch managers cannot reduce your debt. If your business is struggling, gather your GST records and tax returns. Write directly to the Ahmedabad Zonal Committee to ask for more time and a waiver of late fees.
MAS Finance Policy & Recovery Reality Check
Understand why MAS Financial Services currently denies OTS discounts and evaluate realistic resolution paths.
Important Notice: Branch managers possess zero authority to discount debt. Reject unauthorized telecaller claims offering instant 50% discounts.
03. Two-Wheeler & Commercial Vehicle Repossession: Supreme Court Legal Rules
MAS Finance finances two-wheelers, light trucks, and commercial vehicles. These vehicle loans are registered under Section 51 of the Motor Vehicles Act, 1988. The lender holds a charge over the vehicle until you pay the last installment.
If you miss payments for 60 to 90 days, recovery agents may try to seize the vehicle. Some agents threaten to tow vehicles or snatch bikes from outside homes. These strong-arm tactics violate Supreme Court rulings and RBI fair practice rules.
The Supreme Court gave landmark rulings in ICICI Bank v. Prakash Kaur and Shanti Devi Sharma. The court held that lenders and NBFCs cannot use musclemen or private agents to grab vehicles by force. MAS Finance must follow strict legal steps before taking a vehicle. It must send a written notice with the exact amount due. It must give you time to pay. If taking possession, agents must prepare an inventory signed by independent witnesses. Finally, the lender must send a pre-sale valuation notice so you can pay your dues before any auction.
04. LAP & Housing Finance Defaults: Countering SARFAESI Section 13 Notices
Mortgage loans and housing credit from MRHMFL carry registered liens recorded in the CERSAI registry. When an account remains unpaid for 90 days, the lender classifies it as a bad loan under central banking rules.
Next, the housing firm uses the 2002 SARFAESI law. You get a demand notice under Section 13(2). It gives you two full months to clear the debt. Do not ignore this letter. If you do not reply in time, the firm can take paper control of the home under Section 13(4).
Borrowers have clear rights under Section 13(3A). You can write a detailed objection letter within those two months. Explain your business losses and show bank statements. Point out any wrong late charges and offer fixed monthly payments. MAS Finance must review your points and reply in writing within 15 days. Also, under Section 13(8), you can save your property. You can clear the real dues at any time before auction notices appear in print.
Filing written objections under Section 13(3A) requires MAS Finance to reply within 15 days. If the lender ignores your points, you can challenge the action before the Debts Recovery Tribunal (DRT).
05. Section 171 Banker Lien: Why MAS Finance CANNOT Freeze Your Accounts
Section 171 of the Contract Act gives lien rights only to licensed banks. MAS Financial Services is an NBFC. It does not hold a commercial bank charter. Courts across India agree that non-bank finance firms hold zero banker lien powers.
MAS Finance cannot freeze or touch your savings balances at institutions like State Bank of India, Axis Bank, or Kotak Bank. Their only route to take money was through your monthly NACH mandate. Under central bank rules, you can visit your home branch and ask them to stop or cancel that mandate at once.
06. Stopping Sole Arbitration Under Perkins Eastman & Section 12(5)
When loan dues stay unpaid past 90 days, MAS Finance often sends an arbitration notice from Ahmedabad. The company picks a sole arbitrator on its own to issue a money claim against the borrower.
Picking an arbitrator without both sides agreeing breaches Section 12(5) of the 1996 Arbitration Act. Under the Supreme Court ruling in Perkins Eastman, a lender cannot select an arbitrator alone. Any nominee picked without your consent has no power to hear the dispute.
If you receive an arbitration notice, send a written objection at once. Cite Perkins Eastman and Section 12(5). State clearly that you reject the arbitrator. Warn that you will contest any one-sided order in court under Section 34.
Under Supreme Court rulings, MAS Finance cannot appoint a sole arbitrator without your consent. One-sided awards violate Section 12(5) of the Arbitration Act and cannot be enforced in court.
07. Electronic NACH Bounces Under Section 25 & Section 138 Defense
If auto-debit payments fail due to low funds, MAS Finance sends notice under Section 25 of the 2007 Payment Systems Act. For unpaid paper cheques, it files cases under Section 138 of the 1881 Cheque Act.
The lender must follow clear time rules. It must issue a legal notice within 30 days of the bank memo. You then get 15 days to clear the unpaid sum. The lender can only file a court case if you fail to pay within those 15 days.
These matters are bailable debt disputes. The law aims to recover money, not put people in jail. If a court summons arrives, go to court with a lawyer to get bail on the same day. Because these matters allow mutual settlement, judges urge both sides to work out a plan.
08. Stopping Recovery Agent Harassment Under BNS 351
When loan installments go unpaid, collection staff may cross the line. Common abuses include sudden home visits, threats of public shame, odd-hour phone calls, and fake legal notices sent over WhatsApp.
These harsh acts violate RBI Fair Practice rules for NBFCs. RBI rules limit calling hours strictly between 8 AM and 7 PM. Agents must never curse, threaten your family, or enter your house without an ID card and bank badge.
Under the new Indian penal code, the Bharatiya Nyaya Sanhita (BNS) 2024, abusive debt recovery is a crime. Threats of harm count as Criminal Intimidation under Section 351 BNS. Sending fake court notices is Cheating under Section 319 BNS. Entering your home by force violates Section 329 BNS. Save all phone recordings and text messages. File a police complaint and post an alert on the RBI Sachet website at sachet.rbi.org.in.
09. The Fake Verbal Settlement Scam: Rejecting Unauthorized Telecaller Deals
Recovery telecallers face strict collection targets from head office. To collect quick money, some agents use fake verbal settlement offers.
Agents call or send WhatsApp messages promising discounts of 40% to 50% if you pay right away. Many borrowers transfer money via UPI, thinking their loan is closed. But MAS Finance books this money toward overdue penal interest and bounce charges. The main principal remains unpaid, and you remain in default.
Never pay based on verbal promises or direct UPI links. MAS Finance does not recognize informal agent deals. Any real settlement requires an official sanction letter on company letterhead. The letter must have a reference number verified by the head office in Ahmedabad.
10. The Multi-Year Default Reality: When Can MAS Finance Loans Actually Settle?
During the first six months of default, MAS Finance rejects all requests for debt cuts. But balance sheet rules change as bad loans grow older. RBI rules state that unsecured loans unpaid for two years must be listed as loss assets.
When bad debt gets written off on company books, running field recovery costs too much money. At this later stage, MAS Finance often sells groups of bad loans to asset reconstruction firms. Or it brings old cases to Lok Adalat benches to close the file.
If your business collapsed, do not take high-interest street loans to pay penal fees. Keep proof of your business losses. Save your core living money until your account moves to Lok Adalat or an asset firm.
Early default (0-180 DPD): Zero OTS allocation with 100% recovery push. Late stage (360+ DPD loss asset): Writing off bad loans opens the door for Lok Adalat deals or ARC sales.
11. Resolving MAS Finance Delinquencies via National Lok Adalat Benches
The safest way to resolve unpaid debt with MAS Finance is at the National Lok Adalat. The National Legal Services Authority runs Lok Adalats four times a year in local court halls. These benches work under the 1987 Legal Services Act.
You or the lender can ask to list your loan case at the next Lok Adalat. At the table, MAS Finance sends legal officers with settlement power. The goal is to settle bad debts calmly without long trials. Officers often drop penalty charges and set simple monthly terms for the real balance.
Any agreement signed at Lok Adalat becomes a Consent Award under Section 21. This order holds the exact power of a civil court order. It is final and cannot be appealed. The process costs zero court fees and stops all collection calls, vehicle seizures, and arbitration claims.
12. The 4-Stage Redressal Hierarchy: Bypassing Local Branch Desks
If you face agent harassment or need loan restructuring, arguing with branch staff will not help. MAS Finance has a four-tier grievance system set up under RBI consumer protection rules.
Start at Level 1 by contacting Customer Care. Call 1800-202-5555 or 079-41106500. You can also send a WhatsApp message to +91-9537067290 or email mfsl@mas.co.in. The company must register your complaint and reply within 7 working days.
If you get no resolution in 7 days, move to Level 2: Grievance Officer Ms. Preksha Bharucha at 079-41106751 or email mfsl@mas.co.in. If unresolved after 15 days, escalate to Level 3: Principal Nodal Officer Mr. Bharat Mori at 079-41106500 or email pno@mas.co.in. Both sit at Narayan Chambers, Ashram Road, Ahmedabad. If the company fails to resolve your issue within 30 days, file a complaint at Level 4 with the RBI Ombudsman at cms.rbi.org.in or call 14448.
Level 1: Central Desk (18002025555, mfsl@mas.co.in) -> Level 2: GRO Preksha Bharucha (079-41106751) -> Level 3: PNO Bharat Mori (pno@mas.co.in, 079-41106500) -> Level 4: RBI Ombudsman (cms.rbi.org.in | 14448).
MAS Financial Services 4-Tier Escalation Matrix
Do not waste time arguing with recovery telecallers. Escalate your dispute directly through these statutory tiers.
Register your initial grievance ticket and request formal hardship review on your loan file.
Escalate unresolved Level 1 complaints and report illegal recovery harassment or vehicle seizure threats.
Statutory senior escalations for severe regulatory non-compliance and unaddressed disputes.
If MAS Financial Services fails to resolve your grievance within 30 days, file an official statutory complaint under the Reserve Bank - Integrated Ombudsman Scheme, 2021.
Send this notice via registered email to pno@mas.co.in and mfsl@mas.co.in if facing unlawful recovery harassment or seeking loan restructuring.
To,
The Principal Nodal Officer & Grievance Redressal Cell,
MAS Financial Services Limited,
6 Ground Floor, Narayan Chambers, Behind Patang Hotel,
Nehru Bridge Corner, Ashram Road, Ahmedabad, Gujarat 380009.
Email: pno@mas.co.in
CC: mfsl@mas.co.in

Subject: FORMAL GRIEVANCE NOTICE - UNLAWFUL RECOVERY HARASSMENT, SECTION 171 INAPPLICABILITY & REQUEST FOR RESTRUCTURING / LOK ADALAT REFERRAL
Loan Account Number: [YOUR_MAS_FINANCE_ACCOUNT_NO]
Product: Micro-Enterprise Loan / SME Facility / Two-Wheeler / Commercial Vehicle Advance

Dear Sir or Madam,

I write this formal grievance notice regarding my credit account with MAS Financial Services Limited. Empanelled recovery contractors and collection telecallers have engaged in unlawful and coercive collection practices in direct violation of the RBI Master Direction on NBFC Fair Practices Code and Section 351 of the Bharatiya Nyaya Sanhita, 2024.

1. Vehicle Repossession Injunction Under Supreme Court Precedents: Recovery personnel have issued unlawful threats to forcibly seize or tow my hypothecated vehicle without due process. Under binding Supreme Court rulings in ICICI Bank v. Prakash Kaur (2007) and Shanti Devi Sharma (2008), lenders cannot use force or musclemen to repossess assets. Any repossession without statutory pre-seizure notice, signed inventory certification, and post-seizure valuation memo constitutes an actionable criminal offense.
2. Section 171 Banker Lien Inapplicability: Recovery callers have issued false threats claiming MAS Financial Services will invoke Section 171 of the Indian Contract Act, 1872 to freeze my commercial current account or personal savings. MAS Financial Services Limited is an NBFC, not a licensed banking company. Section 171 applies exclusively to banks. MAS has zero statutory authority to freeze outside bank accounts or attach salary without a final civil court decree.
3. Perkins Eastman Arbitration Defense: Unilateral notices threatening sole arbitration proceedings violate Section 12(5) of the Arbitration and Conciliation Act, 1996, and Supreme Court rulings in TRF Ltd and Perkins Eastman. I do not consent to any unilaterally appointed arbitrator.
4. Severe Commercial Hardship: Due to verified business disruption and severe cash flow distress, I cannot service compounding late fees, penal interest, and recurring NACH bounce charges.
5. Formal Relief Request: Under the RBI Fair Practices Code, I request immediate cessation of third-party recovery harassment, waiver of accumulated penal interest, and conversion of my overdue principal into an extended term restructuring, or formal referral of this file to the upcoming National Lok Adalat for an agreed consent decree under Section 21 of the Legal Services Authorities Act, 1987.

Please acknowledge this statutory notice within 7 working days with a formal grievance tracking number. If unlawful harassment persists, I will escalate this matter directly to the Reserve Bank of India Integrated Ombudsman on the CMS portal (cms.rbi.org.in).

Sincerely,
[Your Full Legal Name]
[Your Registered Business / Mobile Number]
[Your City, State]
13. MAS Corporate Sanction Letter Audit: 7 Fraud Prevention Safeguards
If MAS Finance ever considers an exceptional settlement, never pay based on phone calls or WhatsApp messages. Rogue agents often forge settlement letters to steal money that never reaches your account.
Before paying any money, insist on an official sanction letter from MAS Financial Services. Verify the letter against these seven safety checks:
- Corporate Letterhead Authenticity: Official letterhead showing company details, including CIN L65910GJ1995PLC026064 and RBI Registration Number B.01.00241.
- Verifiable Reference Number: A clear file reference number and date matching records at the Ahmedabad head office.
- Precise Account Particulars: Exact match of your full name, PAN, business details, and loan account number.
- Itemized Ledger Breakdown: A clear table showing total dues, waivers of penal fees, and the agreed final payment amount.
- Direct Corporate Bank Escrow: Payment instructions requiring payment only into MAS Financial Services' official company bank account.
- Credit Bureau Clearance Terms: A written promise to report the account as Settled or Closed to credit bureaus within 30 days.
- Corporate Signatory Seal: The signature and designation stamp of an authorized MAS officer, or a verified digital signature.
14. Credit Profile Rebuilding (750+ CIBIL Roadmap)
Missing loan payments with MAS Finance leads to bad marks at all four credit bureaus: CIBIL, Experian, Equifax, and CRIF. The loan gets marked as NPA or Default. This cuts your credit score by 100 or more points and halts new loans.
When you finish paying under a payment plan or Lok Adalat order, MAS Finance marks the loan as Settled or Paid. That note stays on your file for a few years, but closing the loan stops extra fees and lets you rebuild your score.
Rebuilding a 750 score takes 18 to 24 months of steady work. First, get an official No Dues letter and check bureau records after one month. Next, place a fixed deposit of ₹25,000 to ₹50,000 in a bank to get a secured credit card. Use the card to pay small utility bills. Keep spending below 30% of the limit. Always pay the full bill before the due date. On-time payments each month will raise your score.
Step 1: Get an official No Dues letter. Step 2: Check bureau updates after 30 days. Step 3: Open an FD-backed credit card. Step 4: Keep card spending under 30%. Rebuilds your score to 750+ within 18 to 24 months.
15. MAS Financial Services Default Defense: Frequently Asked Questions
Authoritative answers to critical legal and recovery questions regarding MAS Finance loan defaults.
Does MAS Financial Services currently offer One-Time Settlement (OTS) or loan haircuts?▼
No. MAS Financial Services maintains a strict zero-settlement policy for retail and SME loans. The company demands 100% principal recovery and provides no budget for early loan write-downs.
Can MAS Financial Services recovery agents legally seize my two-wheeler or commercial vehicle without notice?▼
No. Under Supreme Court rulings, lenders cannot use musclemen to take vehicles. Seizing a vehicle requires advance written notice, a signed inventory memo, and a formal valuation notice.
Can MAS Financial Services legally freeze my bank account under Section 171 Banker's General Lien?▼
No. Section 171 banker lien applies only to licensed banks. MAS Financial Services is an NBFC. It has no legal power to freeze outside bank accounts or attach your salary without a court order.
What should I do if MAS Financial Services issues a SARFAESI Section 13(2) notice on my property?▼
File a written objection under Section 13(3A) within 60 days. Detail your financial hardship and dispute unfair charges. MAS Finance must reply in writing within 15 days before taking possession.
Can MAS Financial Services enforce an award passed by a unilaterally appointed sole arbitrator?▼
No. Under Supreme Court rulings in Perkins Eastman, lenders cannot choose a sole arbitrator on their own. Appointing an arbitrator without your consent violates Section 12(5) of the Arbitration Act and is void.
Is a court summons under Section 25 PSS Act or Section 138 NI Act for bounced payments a non-bailable offense?▼
No. Both Section 25 and Section 138 are bailable and compoundable offenses. Borrowers can get same-day bail from the magistrate and settle the dispute peacefully through National Lok Adalat.
Why do recovery telecallers offer a 50% discount on MAS Finance loans over phone calls?▼
Telecallers make false verbal promises to earn collection commissions. MAS Finance does not honor verbal deals. Any money paid without an official sanction letter is booked as overdue penal charges.
When can a defaulted MAS Financial Services loan actually be resolved through a compromise?▼
The company denies early settlements. However, accounts overdue for more than two years become loss assets. These can be resolved through Lok Adalat benches or transfers to debt reconstruction firms.
What are the mandatory checkpoints to verify an authentic MAS Financial Services settlement letter?▼
A valid letter must be on official letterhead with CIN L65910GJ1995PLC026064. It must show your loan number, payment terms, and an authorized officer signature.
How do I file a formal complaint against abusive MAS Financial Services recovery agents?▼
Send a written complaint to Principal Nodal Officer Bharat Mori at pno@mas.co.in. If unresolved after 30 days, file a complaint with the RBI Ombudsman at cms.rbi.org.in.
Facing Vehicle Seizure or Court Summons from MAS Finance?
Our legal team helps borrowers stop vehicle seizures, answer SARFAESI notices, and resolve debts at National Lok Adalat benches.
Get Free Legal Strategy ConsultationFind this content helpful?
If this guide has helped you navigate your settlement journey, consider showing some support to keep this platform running.