FlexSalary Credit Line Default: Zero OTS Stance & Borrower Defense
FlexSalary & Vivifi Loan Default Protection Handbook
Actionable consumer rights and procedural defense handbook for delinquent FlexSalary lines of credit, Vivifi India Finance recovery protocols, and statutory notice rebuttals.
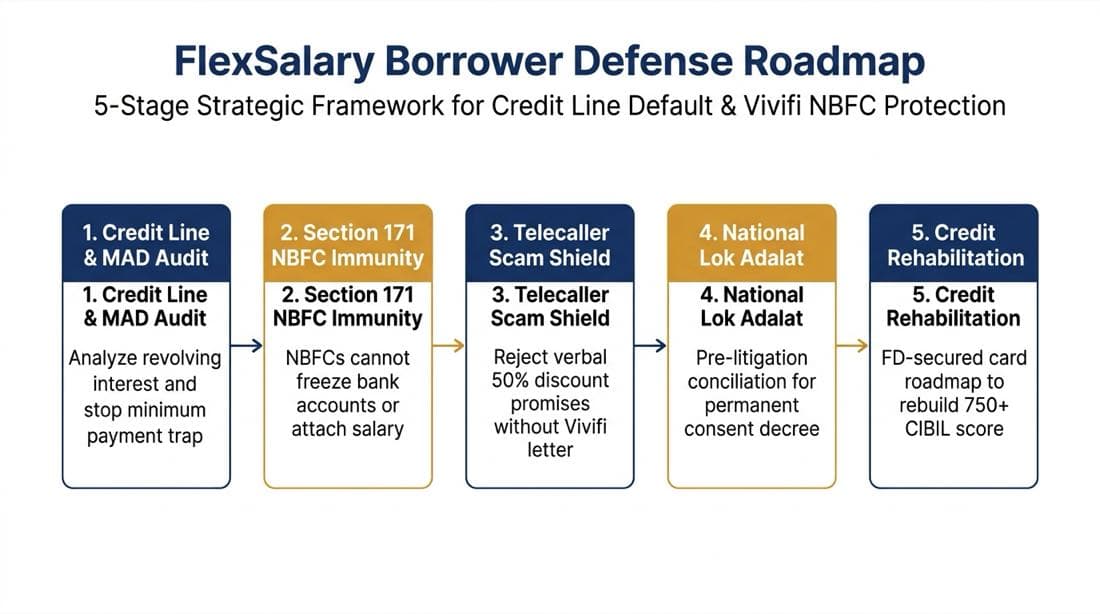
Figure 1.0: 5-stage legal defense guide for handling defaulted FlexSalary credit lines and Vivifi collection calls.
FlexSalary Policy & Recovery Reality Check
Understand why Vivifi India Finance currently denies OTS discounts and evaluate realistic resolution paths.
01. FlexSalary Company Reality: Vivifi India Finance NBFC Rules
FlexSalary operates under Vivifi India Finance Private Limited. Vivifi is an RBI-registered NBFC (Certificate of Registration N-09.00447). The firm started on June 22, 2016 (CIN U65923TG2016PTC110767). Its head office is in Hyderabad at MJR Magnifique in Raidurgam.
The app gives credit lines up to ₹3,00,000 to salaried staff. Automated computer risk models review every user. Vivifi requires 100% repayment of all borrowed money. The firm allocates no budget for debt write-offs on active accounts.
Banks sometimes run loan settlement schemes. Vivifi does not offer debt cuts on active loans. If you ask customer support for an early discount, your request will be denied. Knowing this rule saves you from fake collection agents.
02. The Revolving Credit Line & Minimum Amount Due (MAD) Trap
FlexSalary works as a revolving line of credit. It is not a standard term loan. Users get a credit limit and can make multiple cash withdrawals. Annual interest rates range from 18% to 42%. Additional charges include processing fees and monthly service costs.
The biggest trap is the Minimum Amount Due. Each month, the bill shows a small minimum sum. Many borrowers pay only this amount. They think it cuts their debt. In truth, this payment covers only interest, fees, and taxes. Zero rupees go toward your loan principal.
If you pay only the minimum for several months, unpaid principal keeps growing. You may pay ₹40,000 on a ₹1,00,000 limit and still owe the full ₹1,00,000. To escape this debt trap, stop making fresh withdrawals and ask for fixed monthly installments.
Paying the minimum due covers only interest and fees. Zero rupees go to your loan principal. Paying only the minimum traps you in growing debt.
03. Why FlexSalary Denies Early OTS: Automatic Recovery Rules
Vivifi India Finance refuses loan haircuts for active defaults under 180 days. Automated computer rules enforce this policy.
As an NBFC, Vivifi funds its loans through banks and institutional partners. Its credit models assume salaried workers have steady jobs and bank accounts. When an account defaults, automated systems send daily payment reminders and legal notices instead of offering discounts.
Customer support staff have zero power to change your loan terms. Asking for an OTS waiver during the first six months will always fail. However, under the RBI Fair Practices Code, you can request tenure extensions and penalty fee waivers if you face job loss or medical crises.
04. Recovery Agent Fraud: How Rogue Agents Exploit Borrowers
Vivifi demands 100% recovery of all borrowed funds. This pressure causes recovery agencies to try deceptive collection tactics.
Callers often contact defaulted borrowers on phone or WhatsApp. They promise verbal 50% discounts if you pay right away via UPI. Borrowers pay, thinking the loan is closed. In reality, Vivifi books the money only toward unpaid late fees and interest. The principal remains unpaid.
Never pay money based on phone calls or WhatsApp chats. Vivifi does not honor verbal deals. Any real settlement needs an official sanction letter from Vivifi management in Hyderabad.
05. Section 171 Banker Lien: Why FlexSalary CANNOT Freeze Your Accounts
Recovery callers often threaten to freeze your bank account or salary under Section 171 of the Indian Contract Act, 1872. This threat is false and illegal.
Section 171 banker lien rights apply only to licensed banks. Vivifi India Finance is an NBFC, not a bank. The Supreme Court has ruled that NBFCs cannot use banker lien powers.
FlexSalary cannot freeze or touch accounts at SBI, HDFC, ICICI, or other banks. Its only debit tool is your electronic NACH mandate. Under RBI rules, you can ask your bank to cancel this auto-debit mandate at any time.
06. RBI Digital Lending Rules: Stopping Phone Harassment
The RBI Digital Lending Guidelines protect borrowers who take loans on mobile apps like FlexSalary. Lending apps and recovery teams cannot access your phone contacts, photos, or location data.
Agents who call your family, friends, or boss break central bank privacy rules. Debt issues may only be discussed with the borrower. Also, collection calls are allowed only between 8:00 AM and 7:00 PM.
If recovery agents harass your contacts, save the evidence. Record the calls and take screenshots of chats with phone numbers. Send a complaint to Vivifi's Principal Nodal Officer in Hyderabad and file a report on the RBI Sachet portal.
Loan apps cannot read your phone contacts or call other people. Calling hours are strictly 8:00 AM to 7:00 PM. Calling friends or your boss breaks RBI rules.
07. Stopping Sole Arbitration Under Perkins Eastman & Section 12(5)
When a FlexSalary account defaults past 90 days, Vivifi often sends notices threatening online arbitration. Emails may claim a sole arbitrator will pass an ex-parte money order.
Under Section 12(5) of the Arbitration Act, an interested lender cannot pick its own sole arbitrator. The Supreme Court confirmed this rule in the Perkins Eastman and TRF Limited cases. A lender needs your consent to pick an arbitrator.
Do not let digital arbitration notices scare you. Reply in writing. Cite the Perkins Eastman ruling. State that you do not consent to the arbitrator and that any unilateral order is void under Section 12(5).
08. Electronic NACH Bounces Under Section 25 & Bail Defense
If auto-debit payments fail due to low balance, Vivifi sends notices under Section 25 of the Payment and Settlement Systems Act, 2007. This law treats bounced NACH debits like bounced cheques under Section 138 of the NI Act.
Vivifi must follow strict legal steps. It must send a written notice within 30 days of the debit bounce. You then get a 15-day window to pay the dues. Only after 15 days can Vivifi file a court case before a magistrate.
Section 25 cases are bailable matters. The law seeks debt recovery, not jail. If a summons arrives, go to court with a lawyer to get bail. Courts support fair settlements and close cases once a plan is filed.
A bounced NACH payment is a bailable dispute. Never ignore court summons. Get same-day bail through a lawyer and ask the court to send the file to Lok Adalat.
09. Stopping WhatsApp Threats Under BNS 351
Because Vivifi denies debt haircuts, recovery telecallers often try aggressive scare tactics. They send fake police notices on WhatsApp, threaten home visits to shame you before neighbors, or claim arrest warrants have been issued.
Under the Bharatiya Nyaya Sanhita, 2024, abusive actions are crimes. Threatening you is Criminal Intimidation under Section 351 BNS. Sending fake notices is Cheating under Section 319 BNS. Entering your home without consent is Trespass under Section 329 BNS.
Save all phone recordings and chat logs. File a police complaint under Section 351 BNS at your local station. Also send the proof to the National Cybercrime Portal and the RBI Sachet portal.
10. Default Timelines: When Can Vivifi Accounts Settle?
Vivifi rejects settlements during early default (up to 180 days). But bad debt rules change over time. Under RBI norms, loans unpaid past two years become loss assets on company books.
Once a loan is fully provisioned, paying field collection teams yields low returns. FinTech lenders often bundle old debts for sale to Asset Reconstruction Companies (ARCs) or send them to Lok Adalat settlement benches.
Borrowers in severe hardship should not take fresh high-cost loans to pay interest. Protect family needs, keep proof of job loss or illness, and wait for formal resolution through statutory Lok Adalat benches.
Early Default (0-180 DPD): Zero-OTS policy; full payment demanded. Old Default (360+ DPD): Bad debt write-downs allow settlements through Lok Adalat or ARC transfers.
11. Resolving FlexSalary Delinquencies via Statutory Lok Adalat Conciliation
The safest way to settle old Vivifi debts is through the National Lok Adalat. Organised quarterly across India by NALSA and state legal authorities, Lok Adalats help settle pre-litigation disputes peacefully.
If your loan goes to Lok Adalat, Vivifi sends officers with power to settle. Lok Adalats clear bad debts without long trials. Officers often waive all late fees and accept monthly principal payments.
A Lok Adalat settlement creates a Consent Award under Section 21 of the Legal Services Authorities Act, 1987. This award has the full power of a civil court decree. It is final, non-appealable, and stops all future recovery actions.
12. The 4-Tier Vivifi Escalation Matrix: Bypassing In-App Chatbots
If you face recovery harassment or need loan restructuring, in-app bots are useless. You must escalate through Vivifi's official four-tier system under RBI rules.
Tier 1: Contact Central Support at support@flexsalary.com or call 040-46175151. They must log your ticket and reply within 7 days.
Tier 2: If unresolved, contact Principal Nodal Officer Prakash Rajan at pno@vivifin.com or call +91-91211-96333.
Tier 3: Escalate to Director Srinath Kompella at srinath@vivifin.com.
Tier 4: If the firm fails to resolve your issue within 30 days, file an online complaint with the RBI Integrated Ombudsman at cms.rbi.org.in or call 14448.
Level 1: Customer Care -> Level 2: PNO Prakash Rajan (pno@vivifin.com) -> Level 3: Management Review -> Level 4: RBI Integrated Ombudsman (cms.rbi.org.in).
Vivifi & FlexSalary 4-Tier Escalation Matrix
Do not waste time arguing with recovery telecallers. Escalate your dispute directly through these statutory tiers.
Register your initial grievance ticket and request formal hardship review on your loan file.
Escalate unresolved Level 1 complaints and report illegal recovery harassment or third-party contact calling.
Direct escalation to the Whole-time Director if the Grievance Cell fails to redress severe collection violations.
If Vivifi India Finance fails to resolve your grievance within 30 days, file an official complaint under the RBI Integrated Ombudsman Scheme.
Copy this legally vetted notice, insert your loan details, and email it to pno@vivifin.com to create an official paper trail against illegal collection tactics.
To,
The Principal Nodal Officer & Grievance Redressal Cell,
Vivifi India Finance Private Limited,
Unit A, 9th Floor, MJR Magnifique, Survey No 75 & 76,
Khajaguda X Roads, Raidurgam, Hyderabad, Telangana 500008.
Email: pno@vivifin.com
CC: support@flexsalary.com, support@vivifin.com, srinath@vivifin.com

Subject: FORMAL GRIEVANCE NOTICE - RECOVERY AGENT HARASSMENT & REQUEST FOR RESTRUCTURING / LOK ADALAT REFERRAL
Loan Account Number: [YOUR_FLEXSALARY_ACCOUNT_NO]
Product: FlexSalary Revolving Credit Line / Personal Advance

Dear Sir or Madam,

I write this formal grievance notice regarding my credit account with Vivifi India Finance Private Limited (FlexSalary). Empanelled recovery telecallers and collection personnel have engaged in unlawful and coercive collection practices in direct violation of the RBI Digital Lending Guidelines 2022 and Section 351 of the Bharatiya Nyaya Sanhita, 2024.

1. Unlawful Contact Access & Third-Party Harassment: Collection agents have repeatedly called or messaged third-party phone contacts, family members, and workplace supervisors to disclose my loan default. Under the RBI Master Direction on Digital Lending (2022), lending applications and recovery personnel are strictly barred from accessing contact lists or contacting unrelated individuals.
2. Section 171 Banker Lien Inapplicability: Recovery callers have issued false threats to freeze my salary account or attach external bank savings. Vivifi India Finance is an NBFC, not a licensed bank. Under Section 171 of the Indian Contract Act, 1872, banker general lien powers apply strictly to banks. Vivifi has zero legal authority to freeze external accounts without a competent court decree.
3. Perkins Eastman Arbitration Defense: Unilateral notices threatening sole digital arbitration violate Section 12(5) of the Arbitration and Conciliation Act, 1996, and Supreme Court rulings in TRF Ltd and Perkins Eastman. I do not consent to any unilaterally appointed arbitrator.
4. Severe Financial Distress: Due to documented financial hardship and verified loss of income, I cannot service compounding late fees and Minimum Amount Due revolving interest charges.
5. Formal Relief Request: In accordance with the RBI Fair Practices Code, I request the immediate cessation of unauthorized third-party harassment, waiver of accumulated daily penal charges, and conversion of my outstanding principal into an affordable fixed-term installment plan, or formal referral of this account to the upcoming National Lok Adalat for an agreed consent decree under Section 21 of the Legal Services Authorities Act, 1987.

Please acknowledge this statutory notice within 7 working days with a formal grievance tracking number. If unlawful harassment persists, I will escalate this matter directly to the Reserve Bank of India Integrated Ombudsman on the CMS portal (cms.rbi.org.in).

Sincerely,
[Your Full Name]
[Your Registered Mobile Number]
[Your City, State]
13. Forensic Settlement Letter Checklist: 7 Mandatory Checkpoints
If Vivifi agrees to a settlement, never pay based on calls or chats. Scam callers often send fake letters to steal money.
Before paying any money, check these seven points on the letter:
- Company Letterhead: Must show Vivifi India Finance Private Limited, CIN U65923TG2016PTC110767, and RBI CoR N-09.00447.
- Reference Number: A unique settlement code and date matching company records.
- Correct Details: Your full legal name, PAN, and exact FlexSalary account number.
- Balance Breakdown: A table showing total dues, waived fees, and the agreed settlement amount.
- Official Bank Account: Instructions to pay directly to Vivifi's official bank account, never a personal UPI.
- Credit Bureau Clause: A promise to report the loan as 'SETTLED' or 'CLOSED' to CIBIL within 30 days.
- Officer Signature: A physical or digital signature from an authorized Vivifi officer.
14. Post-Default Credit Rehabilitation: Rebuilding a 750+ CIBIL Score
Defaulting on FlexSalary damages your credit score across CIBIL, Experian, Equifax, and CRIF High Mark. After 90 days of missed payments, the account is marked as 'NPA' or 'DEFAULT'. This drops your score by 90 to 180 points.
When you finish an agreed settlement, Vivifi reports the status as 'SETTLED' or 'CLOSED'. While a 'SETTLED' mark stays on bureau files for seven years, closing the loan stops monthly default reporting and halts balance growth.
Rebuilding a 750 score takes 18 to 24 months. First, get a No Dues Certificate and check bureau updates. Next, open a fixed deposit to get a secured credit card. Use the card for small bills. Keep usage below 30%. Pay your bill in full on time every month to rebuild your credit.
Step 1: Obtain formal NDC. Step 2: Verify bureau update after 30 days. Step 3: Open an FD-secured credit card. Step 4: Maintain low credit utilization below 30%.
15. FlexSalary & Vivifi Default Defense: Frequently Asked Questions
Authoritative answers to critical legal and recovery questions regarding FlexSalary defaults.
Does FlexSalary currently offer One-Time Settlement (OTS) or loan principal haircuts?▼
No. FlexSalary currently maintains a strict zero-settlement stance. The lender demands 100% principal recovery. It does not budget for early loan write-downs.
Why do recovery telecallers claim they can settle my FlexSalary debt for a 50% discount?▼
Telecallers make verbal promises to earn collection fees. Vivifi does not honor verbal deals. Any money paid without an official sanction letter is booked as late fees.
Can FlexSalary legally freeze my savings bank account under Section 171 Banker's General Lien?▼
No. Section 171 banker lien rules apply only to banks. Vivifi is an NBFC. It has zero legal right to freeze outside bank accounts or salary.
What is the Minimum Amount Due (MAD) trap on the FlexSalary revolving credit line?▼
Paying only the minimum due covers interest and taxes. Zero rupees reduce your borrowed principal. Compounding daily interest then traps you in debt.
What legal defense protects borrowers if FlexSalary recovery agents call their phone contacts or employer?▼
The RBI Digital Lending Directions bar apps from accessing contact lists. Harassing friends or relatives is illegal under Section 351 BNS.
Can FlexSalary enforce a digital arbitration award passed by a unilaterally appointed arbitrator?▼
No. Under Supreme Court rulings in Perkins Eastman and TRF Ltd, lenders cannot pick a sole arbitrator alone. Unilateral awards are void under Section 12(5).
Is a court summons under Section 25 PSS Act for a bounced NACH auto-debit a non-bailable offense?▼
No. Section 25 PSS Act is a bailable commercial offense. Borrowers can get same-day bail from the magistrate and resolve the dispute peacefully in Lok Adalat.
When can a defaulted FlexSalary loan actually be resolved through a compromise?▼
Early settlements are denied by company policy. But loans overdue past two to three years become loss assets. These can be settled in National Lok Adalat.
What are the mandatory checkpoints to verify an authentic Vivifi India Finance sanction letter?▼
A valid letter needs Vivifi letterhead with CIN U65923TG2016PTC110767, your loan number, exact settlement figures, and an authorized officer signature.
How do I file a formal complaint against abusive FlexSalary recovery telecallers?▼
Send a written complaint with call recordings to PNO Prakash Rajan at pno@vivifin.com. If unresolved after 30 days, file an online complaint with the RBI Ombudsman at cms.rbi.org.in.
Facing Aggressive Recovery or Contact Harassment from FlexSalary?
Our specialized team helps borrowers stop illegal recovery calls, counter unauthorized telecaller threats, and navigate formal Lok Adalat dispute resolution.
Get Free Defense GuidanceFind this content helpful?
If this guide has helped you navigate your settlement journey, consider showing some support to keep this platform running.