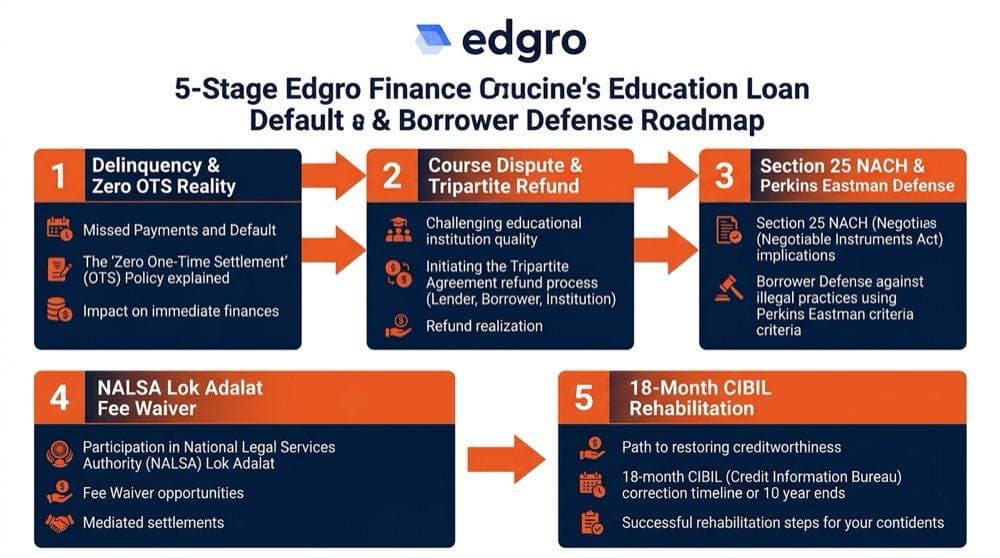
Visual Roadmap: The 5-stage Edgro default defense journey: Delinquency and Zero OTS Reality, Tripartite Course Refund, Section 25 NACH and Perkins Eastman Defense, NALSA Lok Adalat Fee Waiver, and 18-Month CIBIL Rehabilitation.
Quick Answer SummaryNo, you cannot settle an Edgro Finance loan for a 50% discount. As a specialized education NBFC, Edgro borrows wholesale capital from senior banks and securitizes retail loan cash flows into Pass-Through Certificates (PTCs). Frontline managers have zero legal power to waive loan principal. However, Edgro CANNOT freeze your outside bank savings (Section 171 applies only to banks). If you are struggling with payments, apply for a 12 to 24 month tenure extension or an official 3 to 6 month job-hunt moratorium. For disputed bootcamps, demand an institutional refund under the Consumer Protection Act, 2019.
1. Edgro Finance Reality: NBFC-ICC Structure & Zero Settlement Stance
Edgro Finance Private Limited is an RBI-registered finance company (NBFC-ICC Reg No: N-02.00357). It is owned by Bluebear Technology Private Limited. Bluebear operates the Propelld digital loan app. Edgro gives loans for college degrees, coding bootcamps, and exam coaching.
The Zero-Settlement Policy:Edgro Finance does not offer One-Time Settlement (OTS) discounts. Borrowers who ask for a 50% haircut face strict refusal. Edgro demands full principal repayment on all active loans. Staff members hold zero power to forgive your debt.
This strict rule comes from how education lenders fund their operations. Knowing these facts helps you protect your family and credit score.
2. The Monoline Education Lending Trap: Why Small NBFCs Deny Haircuts
Big banks like HDFC or SBI sell credit cards, home loans, and car loans. If a personal loan fails, they cover losses from other profits. Big banks use special recovery units to take deep haircuts.
Capital Limits in Small Finance Firms:- Single Loan Market: Edgro lends only for education. It has no other profit lines to cover loan losses.
- Capital Protection: Giving 50% discounts destroys equity capital. It causes rules breaches with the Reserve Bank of India.
- Batch Default Risk: Edgro funds groups of students in the same class. If one student gets a discount, other students stop paying too.
Because of these limits, loan officers cannot cut your loan amount. Every request for a debt discount gets rejected by senior management.
3. Securitization & Pass-Through Certificates: Pledged Cash Flows
Edgro Finance does not take public savings deposits. Instead, Edgro borrows money from large commercial banks. Credit rating agencies like India Ratings rate these credit lines as IND BBB Stable.
How Pass-Through Certificates (PTCs) Work:Edgro pools student loans into trusts rated by CRISIL. These trusts sell bonds to institutional funds. Monthly EMI payments from students belong to these outside funds. Edgro only acts as a collection agent. If Edgro waives your loan balance, it must pay the difference from its own pocket.
When loans sit inside a securitized pool, debt discounts become legally impossible. Borrowers must ask for tenure extensions instead of debt cuts.
4. Coaching Institutes & Bootcamps: Scaler, Masai & Tripartite Disputes
Many students take Edgro loans through coding bootcamps and coaching centers. Students join under job-offer promises. Many students later find that an NBFC loan was booked in their personal name.
Step-by-Step Course Dispute Steps:- Collect Bad Service Proof: Save emails showing missing classes, poor mentors, or fake placement records.
- Send Course Drop Notice: Write a formal course exit email to the school head. Copy Propelld and Edgro Finance.
- Demand Direct School Refund: Under the Consumer Protection Act, 2019, schools cannot keep cash for unused classes. Demand that the school return the cash to Edgro.
- File Consumer Forum Complaint: Lodge a case on consumerhelpline.gov.in naming both the training institute and Edgro Finance.
Fixing the school dispute is the only legal way to lower your loan dues. Ignoring the lender ruins your credit profile.
5. Section 171 Banker Lien Inapplicability: Outside Accounts Are Safe
Under Section 171 of the Indian Contract Act, 1872, banks hold a General Banker Lien. This rule lets banks like SBI or HDFC take cash from your savings account to clear an unpaid loan.
Legal Protection for Your Bank Account:Section 171 applies only to licensed banks. Edgro Finance is an NBFC, not a bank. Edgro has no savings accounts and holds zero lien powers. Edgro cannot freeze or touch your salary account at any bank.
Any agent who threatens to freeze your bank account is breaking the law. Your salary and family savings remain completely safe.
6. Section 25 PSS Act & Section 138 NI Act: Electronic NACH Bounces
When you took the loan via Propelld, you set up an electronic NACH auto-debit. If your bank account lacks funds on the due date, the payment fails. Edgro then sends formal demand notices.
Facts About Payment Bounce Notices:- Section 25 PSS Act, 2007: Covers digital bank mandate bounces. It works like cheque bounce rules for electronic debits.
- Section 138 NI Act, 1881: Applies if physical paper cheques were handed over and dishonoured.
- 15-Day Reply Time: The legal notice gives you fifteen days to reply or pay the due EMI.
- Bailable Civil Matter: Loan default is a civil contract dispute. Police cannot arrest you for an unpaid student EMI.
Send a polite email explaining your job search or income delay. Offer a fresh payment date to show your honest intent.
7. Supreme Court Arbitration Bar: Halting Perkins Eastman Notices
Digital loan contracts often contain arbitration terms setting Bengaluru as the dispute location. Defaulted students often get letters stating that a private arbitrator has taken up their case.
The Supreme Court Protection:In TRF Ltd. and Perkins Eastman, the Supreme Court ruled that a lender cannot pick an arbitrator alone. Under Section 12(5) of the Arbitration Act, an arbitrator chosen without your written consent is illegal.
If an arbitrator contacts you, send a written objection citing Perkins Eastman. Such one-sided proceedings have no standing in court.
8. RBI Digital Lending Guidelines & Section 351 BNS: Harassment Defense
Under RBI Digital Lending Guidelines, Edgro and Propelld must oversee all recovery agents. Recovery staff must treat borrowers with dignity and follow strict rules.
Your Rights Under Reserve Bank Rules:- No Contact Access: Lenders cannot look at your phone contacts, gallery, or social media pages.
- No Relative Calling: Agents cannot call your parents or friends unless they signed as joint borrowers.
- Calling Hours: Recovery calls are allowed between 8:00 AM and 7:00 PM only. Night calls are illegal.
- Section 351 BNS: Under Section 351 of the BNS 2024, abusive words or threats count as criminal acts.
Record rude phone calls and take screenshots of messages. Send this proof to the Edgro grievance officer and the Reserve Bank ombudsman.
9. The Fake Verbal Settlement Trap: Rejecting Telecaller WhatsApp Deals
When an account is three months late, collection callers begin reaching out. Callers often claim on WhatsApp that paying 40% will clear the loan.
How Collection Caller Traps Work:Callers earn fast commissions by bringing in cash. They promise fake discounts to get you to pay. If you send money through UPI, Edgro treats it as interest and late fees. The principal balance stays open, and new callers call you next week.
Never pay without an official letter sent from an @edgrofin.com email. Make sure the letter shows your full loan number and closure terms.
10. Late-Stage Default Reality: When Can Edgro Debts Actually Resolve?
Edgro refuses debt cuts during the first year of missed payments. But after two years of default, loan books follow different rules.
Loan Aging and Settlement Timelines:- 1 to 89 Days Late: Early stage. Customer care asks for full payment. Zero discount possible.
- 90 to 365 Days Late: NPA stage. Strong collection pressure. Restructuring offered; haircuts denied.
- 365+ Days Late: Loss asset stage. The lender writes off the debt on its books.
- Final Resolution: Once marked as a loss, Edgro may waive late charges and penal interest to recover base cash.
Waiting for loss asset status damages your CIBIL profile. If you have temporary money trouble, ask for loan restructuring right away.
11. National Lok Adalat Resolution: Eliminating Penal Charges
National Lok Adalats are government-backed settlement courts held every three months. They offer a safe way to settle overdue loans without paying court fees.
Power of Lok Adalat Court Orders:Under Section 21 of the Legal Services Authorities Act, a Lok Adalat order works like a final civil court decree. No party can file an appeal. Judges routinely ask NBFCs to drop all late fees, bounce fines, and penal interest. The student then pays the base principal in affordable monthly parts.
You can ask your local District Legal Services Authority to list your Edgro loan file at the next Lok Adalat bench.
12. Genuine Restructuring Pathways: Moratoriums & EMI Downsizing
Because Edgro denies debt discounts, loan restructuring is the safest way to avoid default. Restructuring protects students from recovery harassment and court notices.
Restructuring Options at Edgro Finance:- Tenure Extension: Extending your loan by 12 to 24 months cuts your monthly EMI in half.
- Job-Hunt Pause: Asking for a 3 to 6 month payment break while looking for work or clearing interviews.
- Step-Up Payments: Paying small token amounts now and higher amounts after landing a full-time job.
- Penalty Waiver: Asking Edgro to cancel unpaid bounce fines if you restart regular EMI payments.
Write to info@edgrofin.com with copies of your resume, job rejection letters, or medical bills to prove your hardship.
13. The 4-Tier Escalation Hierarchy: Reaching the RBI Ombudsman
Chatbots and call center desks follow strict collection scripts. When facing unfair collection practices, move your complaint through formal legal channels.
● Step 1 (Customer Support): Email info@edgrofin.com or call +91-7412812312. Share your loan number and get a ticket number. Wait 7 days.
● Step 2 (Grievance Officer): Email Mr. Guru Prasad, Grievance Redressal Officer, at gro@edgrofin.com at Bengaluru. Wait 14 days.
● Step 3 (Propelld App Nodal): For loan app errors or bootcamp disputes, email nodal.officer@propelld.com. Wait 7 days.
● Step 4 (Reserve Bank of India): If Edgro fails to resolve your issue within 30 days, file a case on cms.rbi.org.in or call 14448.
Keeping email proof of these steps creates a strong record if collection agents cross legal boundaries.
14. Credit Bureau Rehabilitation: The 18-Month 750+ CIBIL Roadmap
When an education loan defaults, credit bureaus like CIBIL and Experian drop your score by 100 points. A low credit score makes it hard to rent homes or get cards.
Four Steps to Rebuild Your Credit Score:- Collect Closure Letter: Get an official No Dues Certificate from Edgro after clearing dues.
- Check Bureau Reports: Check your CIBIL report after 45 days to make sure the loan shows zero balance.
- Get an FD Credit Card: Open a fixed deposit credit card for ₹20,000 with a bank. Use less than 30% limit.
- Pay Bills on Time: Pay card bills in full every month. Your score will climb past 750 within 18 months.
A past default does not stop your career. Careful credit use repairs your score and brings back your financial freedom.